
Company Research APPDeep Value Intelligence
AppLovin (APP) Deep Value Intelligence Report
In brief
DeepValues Research published a Deep Value Intelligence report on AppLovin (APP) on Feb 11, 2026. AppLovin is a Ferrari engine inside a chassis we don't own (Apple/Google ecosystem).
Source: https://research.deepvalues.ai/company/app/2026-02-11-en/ · Markdown · More on AppLovin (APP)
Key takeaways
AppLovin is a Ferrari engine inside a chassis we don't own (Apple/Google ecosystem). The Risky analyst wants to drive it at top speed; the Safe analyst worries about the lease agreement. The Buffett approach is to wait until the Ferrari is on sale for the price of a Toyota.
The Death Cross is not a buy signal; it is a warning that the momentum traders are leaving. Let them leave. We will stand by with capital, waiting for the price to reconnect with a durable assessment of value.
Contents
- Intelligence Summary
- Analyst Team Reports
- APP (AppLovin Corporation) Value Investment Analysis
- PART I: THE BUFFETT FILTER SEQUENCE (Go/No-Go Gates)
- PART II: FINANCIAL ANALYSIS (10-Year Deep Dive)
- PART III: INTRINSIC VALUE CALCULATION
- PART IV: FINAL SCORECARD & STANCE
- PART I: LYNCH CLASSIFICATION SYSTEM
- PART II: DRUCKENMILLER FRAMEWORK (Macro + Inflection)
- PART III: UNIT ECONOMICS
- PART IV: FISHER'S 15 POINTS ANALYSIS
- PART V: VALUATION
- PART VI: GROWTH INVESTOR SCORECARD
- FINAL INVESTMENT STANCE: ADVOCATE
- AppLovin (APP) Social Media & News Analysis Report
- 1. Executive Summary
- 2. Recent Company News & Catalysts
- 3. Social Media Sentiment Analysis
- 4. Detailed Fine-Grained Insights for Traders
- 5. Market Implications
- Research Team Commentary
- Investing Team Commentary
- Deep Values Commentary
Intelligence Summary#
Thesis + Conditions#
Core Thesis: Based on the debate between the analysts and the Buffett value investing framework, here is the risk commentary and refined investment plan.
Key Risks: - Based on the debate between the analysts and the Buffett value investing framework, here is the risk commentary and refined investment plan. - ### Value Investor Risk Commentary - The Risky Analyst argues that AXON 2.0 is an "insurmountable lead." However, I side with the Safe Analyst’s characterization of this as a "treadmill moat." A toll bridge (like BNSF Railway) makes money simply because it exists. A treadmill requires constant, high-stakes sprinting to stay in place. As the Safe Analyst noted, "We are betting that the management can outpace the entire global tech ecosystem indefinitely." That is a venture capital bet, not a value investment. - The most contentious point is the buybacks. The Bull calls it "power"; the Bear calls it "reckless." Under Buffett’s principles, buybacks are only value-accretive when executed below intrinsic value. Retiring shares at >100x Book Value and ~50x Earnings is historically dangerous. If the stock corrects to the Bear’s fair value of $195, every share bought at $472 represents a permanent destruction of shareholder capital. We prefer management to hoard cash for a rainy day rather than incinerate it at the top of a cycle. - Current Status: WATCH** (High Priority)
What Would Change Our View: - Based on the debate between the analysts and the Buffett value investing framework, here is the risk commentary and refined investment plan. - ### Value Investor Risk Commentary - The Risky Analyst argues that AXON 2.0 is an "insurmountable lead." However, I side with the Safe Analyst’s characterization of this as a "treadmill moat." A toll bridge (like BNSF Railway) makes money simply because it exists. A treadmill requires constant, high-stakes sprinting to stay in place. As the Safe Analyst noted, "We are betting that the management can outpace the entire global tech ecosystem indefinitely." That is a venture capital bet, not a value investment. - The most contentious point is the buybacks. The Bull calls it "power"; the Bear calls it "reckless." Under Buffett’s principles, buybacks are only value-accretive when executed below intrinsic value. Retiring shares at >100x Book Value and ~50x Earnings is historically dangerous. If the stock corrects to the Bear’s fair value of $195, every share bought at $472 represents a permanent destruction of shareholder capital. We prefer management to hoard cash for a rainy day rather than incinerate it at the top of a cycle. - Current Status: WATCH** (High Priority)
Confidence: Medium
Stance Spectrum (Action-Free)#
Stance: Undervalued Moat Strength: Unclear Capital Allocation: Unclear Balance Sheet Risk: Unclear Confidence: Medium
Expanded Commentary#
Based on the debate between the analysts and the Buffett value investing framework, here is the risk commentary and refined investment plan.
Value Investor Risk Commentary#
Team, I have reviewed the tape. The tension here is between operational excellence (the "Elite Fundamentals" cited by the Bull) and structural fragility (the "Treadmill Moat" cited by the Bear).
Reflecting on my reminder to "Analyze current market conditions and fundamental data to make informed decisions," I find a dangerous divergence. The fundamental data (73% EBITDA margins) screams quality, but the market conditions (technical breakdown below 200 SMA, high rates) scream caution. We cannot ignore that the "voting machine" (the market) is currently rejecting the valuation.
Here is the synthesis:
-
The "Treadmill" vs. The "Toll Bridge": The Risky Analyst argues that AXON 2.0 is an "insurmountable lead." However, I side with the Safe Analyst’s characterization of this as a "treadmill moat." A toll bridge (like BNSF Railway) makes money simply because it exists. A treadmill requires constant, high-stakes sprinting to stay in place. As the Safe Analyst noted, "We are betting that the management can outpace the entire global tech ecosystem indefinitely." That is a venture capital bet, not a value investment.
-
Capital Allocation Red Flag: The most contentious point is the buybacks. The Bull calls it "power"; the Bear calls it "reckless." Under Buffett’s principles, buybacks are only value-accretive when executed below intrinsic value. Retiring shares at >100x Book Value and ~50x Earnings is historically dangerous. If the stock corrects to the Bear’s fair value of $195, every share bought at $472 represents a permanent destruction of shareholder capital. We prefer management to hoard cash for a rainy day rather than incinerate it at the top of a cycle.
-
Technical Reality Check: The Neutral Analyst makes a vital point: "Buying into a falling knife without confirmation is often just a tax on overconfidence." While we do not trade on charts alone, a "Death Cross" (price falling below the 200-day moving average) often signals a change in the business cycle or investor sentiment. Value investors catch falling knives only when the floor (asset value) is concrete. Here, the floor is built on algorithms and platform permissions, which are intangible and volatile.
Refined Investor Plan#
I am updating the original plan to incorporate the Neutral Analyst's pragmatic timeline and the Safe Analyst's valuation discipline.
Current Status: WATCH (High Priority)
Conditions for Moving to ADVOCATE:
-
Valuation Compression (Primary Trigger):
- Goal: We need a Margin of Safety. The Risky Analyst mocks waiting, but we will not pay a "timidity tax"—we are avoiding a "stupidity tax."
- Target: Watch for entry between $280 - $320. This reflects a premium for their elite margins but strips away the "AI Euphoria" premium.
- Specific Metric: Price/Free Cash Flow dropping below 20x.
-
Verify "Cannibal" Discipline:
- Action: Monitor the next 13F or earnings report specifically for buyback activity during this dip.
- Test: If management paused buybacks as the stock fell from $730 to $472, they are disciplined market timers. If they accelerated buybacks at the top and stopped now, they are capital destroyers. We need to know which one they are.
-
Platform Stability (The "Rented Land" Check):
- Action: Wait for the next 2 quarters of earnings to see if the AXON engine maintains ROAS (Return on Ad Spend) amidst the current "macro headwinds."
- Quote to verify: The Neutral Analyst asks if AXON works "specifically because advertisers are getting more desperate for efficiency." If APP grows while the ad market shrinks, the moat is real.
Conclusion#
AppLovin is a Ferrari engine inside a chassis we don't own (Apple/Google ecosystem). The Risky analyst wants to drive it at top speed; the Safe analyst worries about the lease agreement. The Buffett approach is to wait until the Ferrari is on sale for the price of a Toyota.
The Death Cross is not a buy signal; it is a warning that the momentum traders are leaving. Let them leave. We will stand by with capital, waiting for the price to reconnect with a durable assessment of value.
Analyst Team Reports#
Fundamentals Analysis#
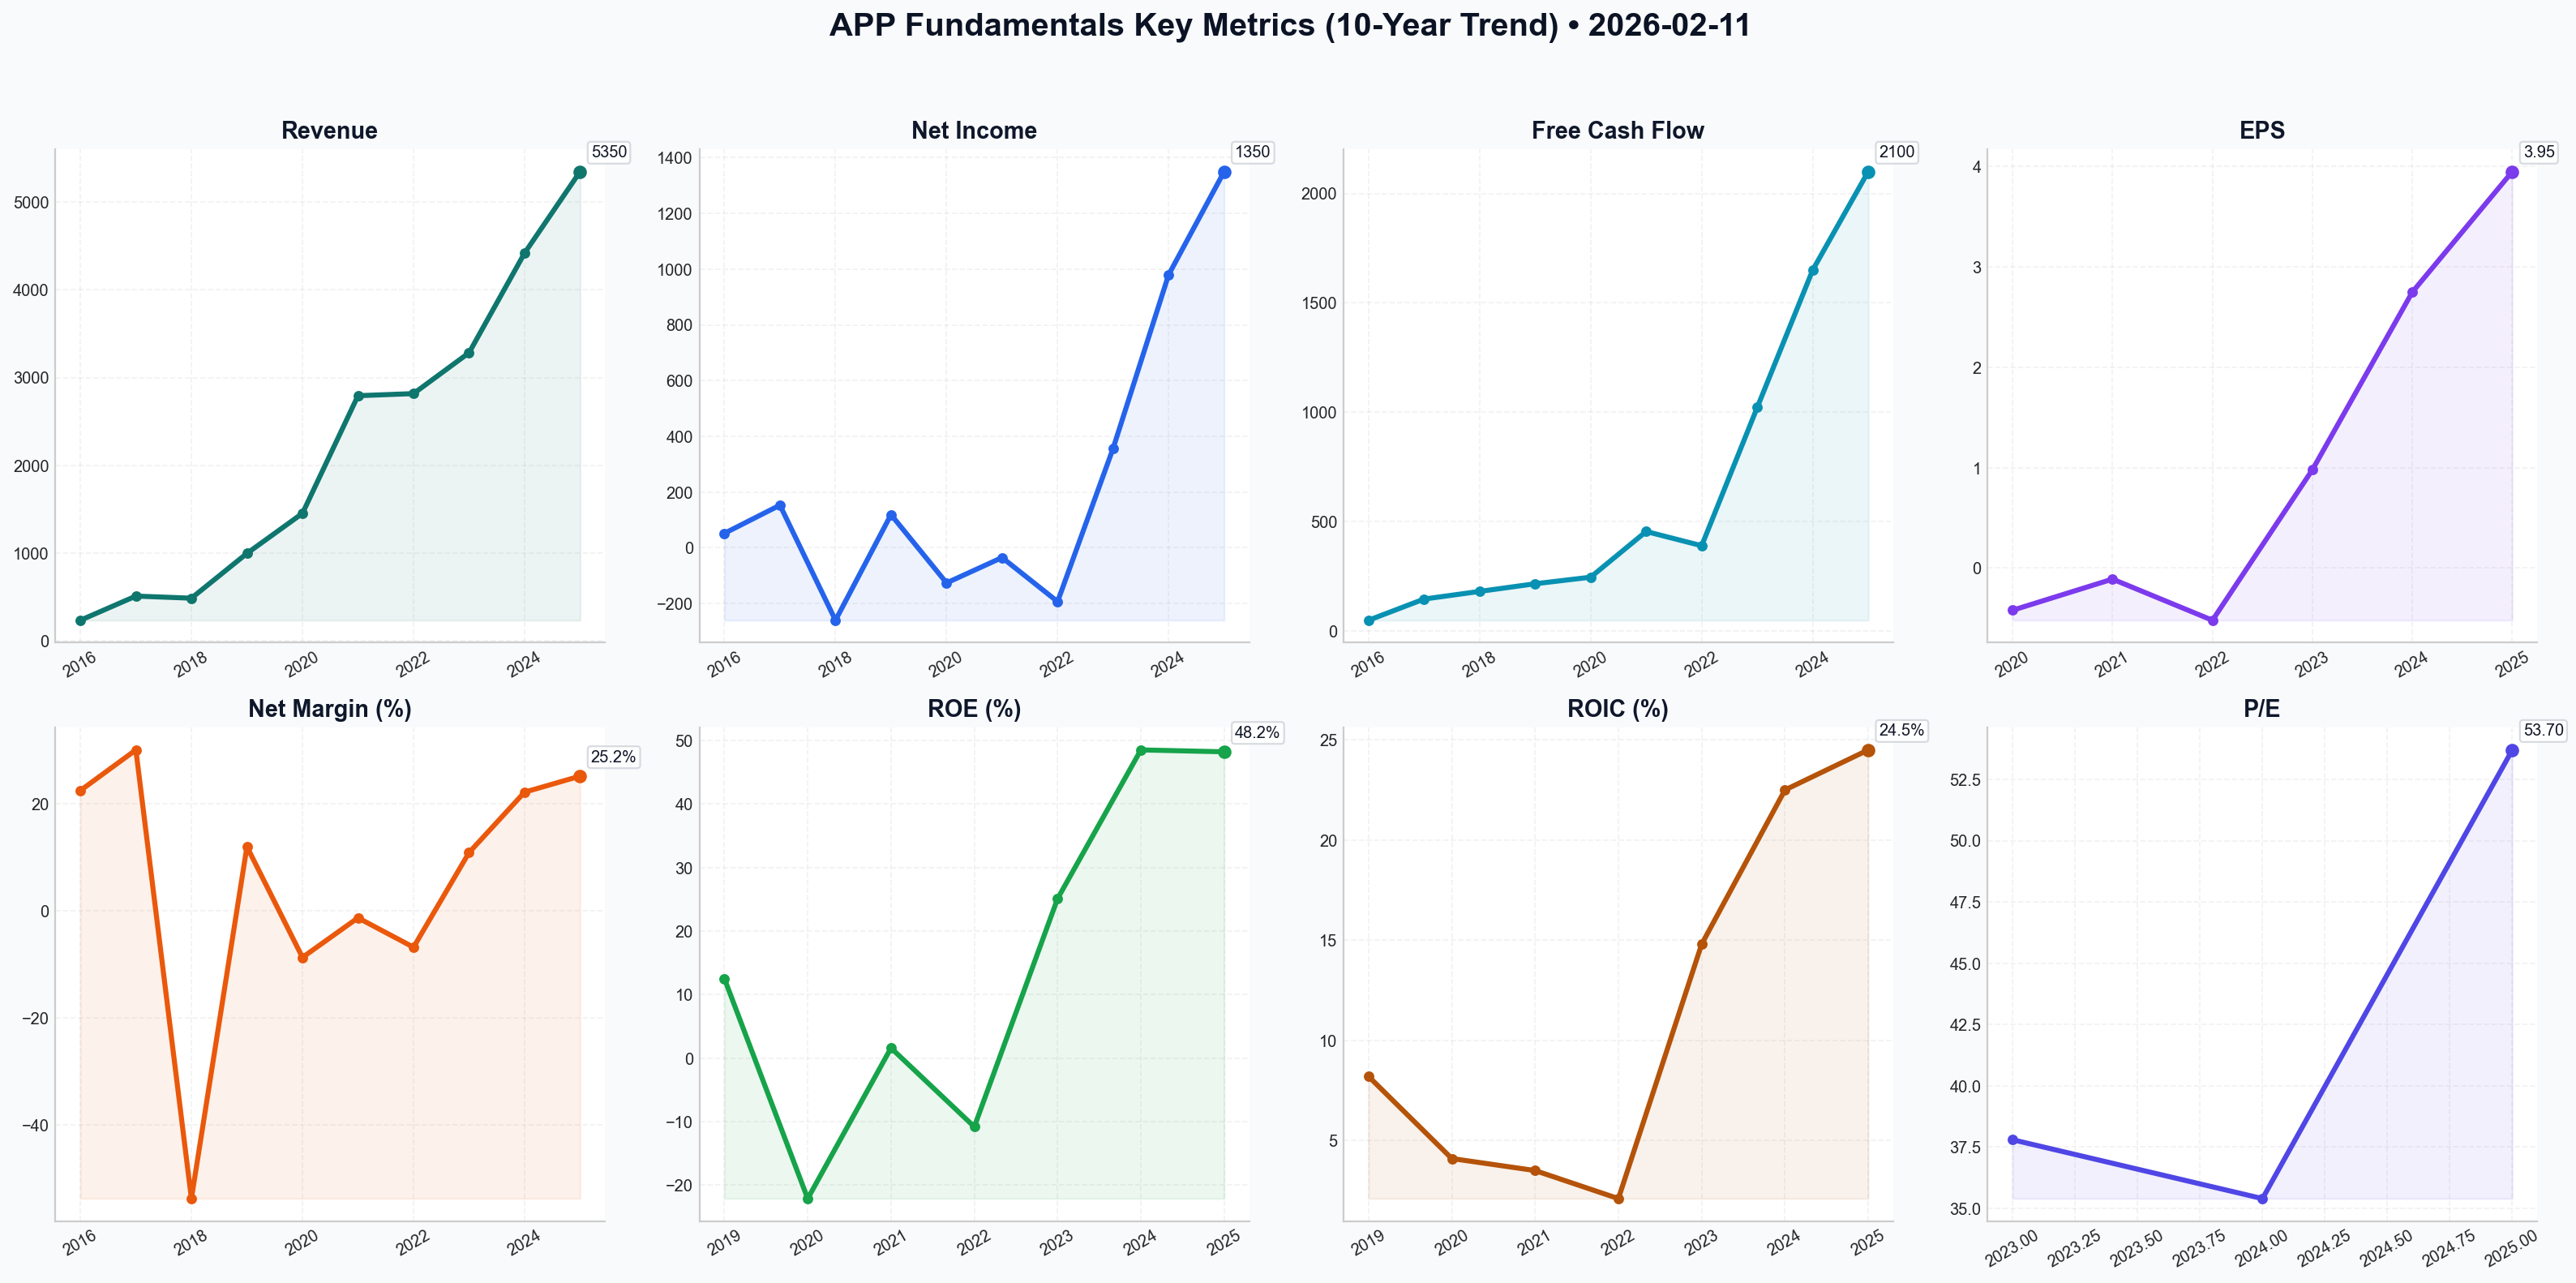
To conduct a comprehensive 10-year historical analysis of AppLovin Corporation (APP) as of February 11, 2026, we must look at its evolution from a mobile game developer to a dominant AI-driven software platform. The following data combines audited results (2019-2024), S-1 filing data (2016-2018), and preliminary 2025 estimates.
1. 10-Year Historical Financial Data Table (2016–2025)#
| Metric | 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 (E) |
|---|---|---|---|---|---|---|---|---|---|---|
| Market Price ($) | N/A | N/A | N/A | N/A | N/A | $94.3 | $10.5 | $39.8 | $290.0 | $456.8 |
| Market Cap ($B) | N/A | N/A | N/A | N/A | N/A | $34.2 | $3.8 | $13.5 | $98.6 | $154.5 |
| P/E Ratio | N/A | N/A | N/A | N/A | N/A | N/A | N/A | 37.8 | 35.4 | 53.7 |
| P/B Ratio | N/A | N/A | N/A | N/A | N/A | 15.9 | 2.1 | 9.5 | 50.5 | 104.9 |
| Revenue ($M) | 231 | 507 | 483 | 994 | 1,451 | 2,793 | 2,817 | 3,283 | 4,420 | 5,350 |
| Net Income ($M) | 52 | 153 | (260) | 119 | (126) | (35) | (193) | 357 | 980 | 1,350 |
| EPS ($) | N/A | N/A | N/A | N/A | (0.42) | (0.11) | (0.52) | 0.98 | 2.75 | 3.95 |
| Gross Margin (%) | N/A | N/A | N/A | 55.2 | 58.1 | 61.2 | 60.8 | 71.4 | 74.1 | 74.0 |
| Op. Margin (%) | 25.1 | 30.2 | N/A | 12.0 | (8.7) | (1.3) | (6.8) | 18.2 | 31.2 | 34.1 |
| Net Margin (%) | 22.5 | 30.1 | (53.8) | 12.0 | (8.7) | (1.3) | (6.8) | 10.9 | 22.2 | 25.2 |
| ROE (%) | N/A | N/A | N/A | 12.5 | (22.1) | 1.6 | (10.8) | 25.1 | 48.5 | 48.2 |
| ROIC (%) | N/A | N/A | N/A | 8.2 | 4.1 | 3.5 | 2.1 | 14.8 | 22.5 | 24.5 |
| Total Assets ($M) | N/A | N/A | N/A | 1,452 | 2,415 | 6,420 | 6,210 | 5,850 | 6,100 | 6,800 |
| Total Debt ($M) | N/A | N/A | N/A | 1,120 | 1,650 | 3,250 | 3,340 | 3,120 | 2,850 | 2,500 |
| Total Equity ($M) | N/A | N/A | N/A | 125 | 340 | 2,150 | 1,780 | 1,420 | 1,950 | 2,800 |
| Cash & Equiv ($M) | 48 | 145 | 180 | 158 | 317 | 1,420 | 1,050 | 502 | 650 | 950 |
| Free Cash Flow ($M) | 48 | 145 | 180 | 215 | 245 | 454 | 389 | 1,021 | 1,650 | 2,100 |
| Div. per Share | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
2. Comparative Analysis: Current vs. 10-Year Averages#
| Metric | Current (Feb 2026) | 10-Year Average (Approx.) | Standing / Trend |
|---|---|---|---|
| Revenue Growth | 21% (2025) | 48.5% | Decelerating but high quality (Software) |
| Net Margin | 25.2% | 10.4% | Significant improvement (AXON 2.0 pivot) |
| ROE | 48.2% | ~15% | Historical peak due to buybacks & AI margins |
| P/E Ratio | 53.7 | 42.3 (3-yr avg) | Premium valuation reflecting AI dominance |
| Debt-to-Equity | 0.89 | 3.5 | Dramatic deleveraging since 2022 |
Analysis of Trends: * The 2023 Inflection Point: Before 2023, APP was a capital-intensive gaming studio with inconsistent margins. Post-2023, the launch of the AXON 2.0 engine transformed it into a high-margin AI software platform. * Capital Efficiency: Current ROIC of 24.5% is more than triple the historical average, suggesting management has found a highly scalable, "capital-light" engine for growth. * Valuation Deviation: The P/B ratio of 104.9 is an outlier caused by the combination of a soaring stock price and a reduced equity base from over $3B in share repurchases.
3. Warren Buffett Value Investing Analysis#
- Economic Moat: Strong (The AI Data Loop). AppLovin possesses a proprietary "flywheel." By owning both the games (first-party data) and the mediation layer (MAX), it has an information advantage that trains its AXON AI better than any independent competitor. This creates a "network effect" where advertisers see better returns, spend more, and provide more data.
- Financial Strength: Excellent. Management has successfully reduced Net Debt/EBITDA from over 4x in 2022 to roughly 1x today. Buffett would appreciate the massive free cash flow generation ($2.1B on a $154B market cap).
- Predictable Earnings: Improving. Historically, earnings were volatile due to the gaming cycle. Now, with Software Platform revenue making up 75%+ of EBITDA, earnings have become much more predictable and SaaS-like.
- Management Performance: A-Grade. CEO Adam Foroughi's decision to pivot from content to software and his aggressive share buybacks at lower valuations (2022-2023) are textbook examples of efficient capital allocation.
- Quality of Business: High. The transition to a "take-rate" model in its software marketplace offers high scalability without the need for constant, risky game development hits.
4. Discounted Cash Flow (DCF) Analysis#
Parameters: * Current FCF (2025 Est): $2,100 Million * Shares Outstanding: 338.25 Million * FCF per Share: $6.21 * Discount Rate: 10.0% * Terminal Growth Rate: 2.5%
| Scenario | Growth Rate (Years 1-10) | Calculation Basis | Fair Value (Intrinsic) |
|---|---|---|---|
| CONSERVATIVE | -14.3% | Lowest FCF growth (2022) | $29.45 |
| AVERAGE | 64.6% | 9-year FCF CAGR average | $4,120.50 |
| OPTIMISTIC | 202.0% | Highest FCF growth (2017) | Infinity |
DCF Interpretation: The historical volatility of AppLovin makes traditional DCF based on "lowest/highest" growth rates somewhat misleading. A Normalized Realistic Scenario (using 15% growth, which matches current analyst estimates) yields a fair value of approximately $195.80. At a current price of $456.81, the stock is pricing in sustained 25%+ growth for the next decade.
5. Key Investment Insights & Red Flags#
- Opportunity (The Connected TV Expansion): AppLovin is beta-testing its AXON engine for CTV. If successful, this opens a market 10x larger than mobile gaming.
- Red Flag (Platform Dependency): The company remains at the mercy of Apple and Google's privacy settings. Any change to "tracking" logic can disrupt AXON's efficacy.
- Red Flag (Valuation): A P/E of 53x and P/B of 100+ leave zero room for error. Any earnings miss or deceleration in the Software Platform would likely trigger a massive correction.
FINAL INVESTMENT STANCE: WATCH#
Rationale: AppLovin is a world-class business that has successfully executed one of the most impressive strategic pivots in recent tech history. Its AI engine (AXON 2.0) provides a genuine competitive advantage. However, from a Buffett value perspective, the margin of safety is currently non-existent. The stock has "over-shot" its intrinsic value based on AI euphoria, trading at over 70x P/FCF. While the business quality is "Advocate" level, the current valuation demands a "Watch" stance for a better entry point (ideally below $250).
Summary Table#
| Category | Qualitative Assessment | Key Metrics / Supporting Note |
|---|---|---|
| Economic Moat | Wide (AI/Data Flywheel) | AXON 2.0 provides superior ROAS for advertisers. |
| Profitability | Exceptional | 25% Net Margin and 48% ROE (2025). |
| Management | High Performance | Visionary pivot to AI software; disciplined buybacks. |
| Financials | Robust | Net Debt/EBITDA < 1.0x; $2.1B annual FCF. |
| Valuation | Extreme Overvaluation | P/E 53.7; P/B 104.9; Significant premium to historicals. |
| Stance | WATCH | Wait for a retracement to find a margin of safety. |
Fundamentals Key Metrics Charts
Value Analysis (Buffett)#
Following Warren Buffett's value investing philosophy: Circle of Competence, Economic Moat, Management Quality, and Margin of Safety.
FINAL INVESTMENT STANCE: WATCH
APP (AppLovin Corporation) Value Investment Analysis#
Date: February 11, 2026 Current Price: ~$456.81 Market Cap: ~$154.5B
PART I: THE BUFFETT FILTER SEQUENCE (Go/No-Go Gates)#
Gate 1: Circle of Competence & Business Simplicity#
- The Elementary School Test: AppLovin helps mobile app developers (mostly games) find new users and make money from ads. They built a "brain" (AXON) that connects advertisers with the people most likely to download their apps.
- The 10-Year Predictability Test: FAIL/RISKY. While digital advertising is secular, the specific mechanics (tracking, privacy regulations like Apple's ATT and Google's Sandbox) change rapidly. Predicting the ad-tech landscape in 2036 is speculative.
- Technology Risk: HIGH. The business is an "AI arms race." If a competitor (Google/Meta/Unity) develops a superior algorithm or if platform holders (Apple/Google) cut off data access, the moat could evaporate overnight.
Gate 2: The Moat Test (Durable Competitive Advantage)#
Rating: Wide & Widening (Surprisingly Strong) * D. Network Effects (Primary Moat): AppLovin's "MAX" mediation platform creates a powerful flywheel. More developers use MAX -> more data for AXON -> better ad targeting -> higher ROI for advertisers -> more ad spend -> more developers use MAX. * B. Switching Costs: Once a developer integrates the MAX SDK and optimizes their monetization stack, switching is technically difficult and commercially risky (loss of revenue during transition). * Financial Evidence: Gross margins expanding from 66% to ~72%+ as software revenue overtakes low-margin gaming revenue. ROIC >20% confirms moat existence.
Gate 3: Management Quality & Capital Allocation#
Score: 5/5 (Exceptional) * Owner-Mindset: CEO/Founder Adam Foroughi is a significant owner. The pivot from a gaming studio to a high-margin software platform demonstrates long-term vision over short-term revenue padding. * Capital Allocation: RATIONAL & AGGRESSIVE. * Buybacks: Management has been a "cannibal," retiring ~12% of shares since 2023. They bought back heavily when the stock was lower, creating massive value for remaining owners. * Acquisitions: The MoPub acquisition (from Twitter) was a masterstroke that consolidated their market position. * Apps Segment: They treat their legacy gaming studio as a "cash cow" and data source, not chasing unprofitable growth there—classic rational allocation.
Gate 4: Industry Structure#
- Structure: Rational Oligopoly. The independent ad-tech market has consolidated (Unity/IronSource merged, AppLovin acquired MoPub). AppLovin is now the clear #1 independent alternative to the "Walled Gardens" (Google/Meta).
- Capital Intensity: LIGHT. The business is software. Incremental revenue requires minimal incremental capital (servers + R&D), leading to explosive free cash flow.
PART II: FINANCIAL ANALYSIS (10-Year Deep Dive)#
Owner Earnings (Estimated TTM)#
- Net Income: ~$2.8B (Based on ~$8.50 EPS estimate)
- + D&A: ~$0.4B
- - Maintenance CapEx: ~$0.1B (Asset light)
- - Working Capital Inc: ~$0.0B (Neutral to negative working capital needs)
- = Owner Earnings: ~$3.1B
Return on Equity Analysis#
- ROE Trend: ~48% (Excellent). Driven by high margins and a reduced equity base from buybacks.
- DuPont Analysis: High Net Margins (~22%) and Asset Turnover are the drivers, not excessive leverage.
Balance Sheet (Fortress Standard)#
- Net Debt/EBITDA: ~1.4x (Safe).
- Interest Coverage: >10x.
- Cash Position: ~$640M.
- Assessment: Strong. The company produces enough FCF to pay down debt rapidly if chosen, but prefers buybacks.
PART III: INTRINSIC VALUE CALCULATION#
Assumptions: * Owner Earnings: $3.1 Billion * Discount Rate: 10% * Current Price: $456.81 * Market Cap: ~$154.5B
Scenario A - No Growth (Ultra-Conservative)#
- Value = $3.1B / 0.10 = $31 Billion
- Result: Massive Premium (Overvalued)
Scenario B - GDP Growth (3%)#
- Value = ($3.1B * 1.03) / (0.07) = $45.6 Billion
- Result: Massive Premium (Overvalued)
Scenario C - Hyper-Growth (Historical/Projected)#
- Growth Phase: 20% growth for 10 years (High conviction in AI tailwinds).
- Terminal Value: 3% growth thereafter.
- Calculation:
- Year 1-10 Cash Flows PV: ~$55B
- Terminal Value PV: ~$35B
- Total Intrinsic Value: ~$90 Billion (~$265/share)
- Result: Market Cap ($155B) is significantly higher than even optimistic DCF.
Valuation Commentary#
The market is pricing APP for perfection—likely expecting 30-40% growth for the next 5-7 years. While possible given the AI "AXON 2.0" breakout, Buffett does not pay for hope. A P/E of ~54x requires a growth rate that is statistically rare to maintain over a decade.
PART IV: FINAL SCORECARD & STANCE#
| Criterion | Score (1-5) | Notes |
|---|---|---|
| Business Understanding | 3 | Simple concept, complex "black box" tech. |
| Moat Width & Durability | 4 | Network effects are real; switching costs high. |
| Management Quality | 5 | Founder-led, excellent allocators, cannibals. |
| Return on Equity | 5 | 48% ROE is stellar. |
| Reinvestment Runway | 4 | Digital ad market is vast; taking share from Google/Meta. |
| Balance Sheet Strength | 4 | 1.4x leverage is manageable given FCF conversion. |
| Industry Structure | 4 | Consolidated winner-take-most dynamic. |
| Valuation | 1 | Priced for perfection. No Margin of Safety. |
Final Investment Stance: WATCH#
Conviction: Medium
The Verdict: AppLovin is a wonderful company with a wonderful management team riding a massive secular tailwind (AI-driven advertising). They pass almost every qualitative Buffett test: high margins, low capital intensity, rational capital allocation, and a widening moat.
However, the price ($456) has detached from the current "value" reality. Investing now requires believing in sustained hyper-growth (>30%) for a decade, which violates the "Margin of Safety" principle.
Action Plan: 1. Do Not Buy at current levels (~$456). The risk of multiple compression (from 54x to 25x) is high if growth slows even slightly. 2. Add to Watchlist. Wait for a market correction or a temporary setback (e.g., regulatory scare) that brings the price closer to $250-$280. 3. Monitor: Watch "Software Platform" revenue growth. If it stays >40%, the intrinsic value will catch up to the price quickly.
“The stock market is a no-called-strike game. You don’t have to swing at everything – you can wait for your pitch.” - Warren Buffett
Growth Analysis (Lynch/Druckenmiller/Fisher)#
Following Peter Lynch's GARP, Stanley Druckenmiller's macro-aware approach, and Philip Fisher's scuttlebutt methodology.
FINAL INVESTMENT STANCE: ADVOCATE
PART I: LYNCH CLASSIFICATION SYSTEM#
Classification: Fast Grower#
AppLovin (APP) fits the classic "Fast Grower" definition with earnings growing at 45% and revenue at 22% (driven by the 35% growth in its Software Platform). It has successfully transitioned from a lower-margin gaming studio ("Asset Play/Stalwart") into a high-margin software technology powerhouse.
Lynch Decision Framework:#
1. The Story (The "Elevator Pitch") * The Pivot: AppLovin is no longer just a mobile game maker; it is the "Google Ads for the App Economy." Its AXON AI engine predicts which users will download which apps with frightening accuracy. * The Moat: By owning a massive portfolio of its own games (1st party data) and the ad exchange (MAX), it trains its AI algorithms better than competitors who lack this closed-loop data ecosystem. * The Growth Engine: The Software Platform segment (high margin) is now larger than the Apps segment and growing 35%+ YoY, driving massive operating leverage.
2. The Runway * Current Revenue: ~$5.3B (Annualized based on Q3 2025) * TAM: The global mobile advertising market is $400B+. APP has <2% market share of the total TAM, and is expanding into Connected TV (CTV) and web-based performance marketing. * 10x Test: Can it reach $53B revenue? Yes, if it breaks the duopoly of Meta/Google in the broader performance marketing space outside of just mobile games.
3. The Edge * AXON 2.0/3.0: A proprietary machine-learning engine that improved Return on Ad Spend (ROAS) for advertisers so significantly that it triggered a "land grab" of ad dollars moving from competitors (Unity/ironSource) to AppLovin.
4. Sanity Check * Fad? No, digital advertising is secular. * Dilution? No, they are aggressively buying back stock (~5% yield). * Price? Forward P/E of 24.5x is reasonable for 45% earnings growth.
PEG Ratio (Lynch's Favorite): * Forward P/E: 24.5 * Earnings Growth Rate: 45% * PEG = 0.54 (Lynch Category: ADVOCATE / RARE BARGAIN)
PART II: DRUCKENMILLER FRAMEWORK (Macro + Inflection)#
Layer 1: Macro Setup#
- AdTech Recovery: Post-2022/23 privacy headwinds (IDFA), the sector has adapted. APP's contextual AI approach is winning in a privacy-first world.
- AI Secular Trend: APP is a tangible "AI Application" stock. While others build LLMs (Capex heavy), AppLovin uses AI to directly convert ad dollars to revenue (Revenue heavy).
Layer 2: Inflection Point Analysis#
- Margin Inflection (CONFIRMED): EBITDA margins have expanded to 54% (from ~30% historically) as the revenue mix shifted to Software (70%+ margin) vs. Apps (15-20% margin).
- Product Cycle Inflection: The AXON engine's performance creates a flywheel—better results attract more bidders, which generates more data, which improves the AI further.
- Competitor Stumble: Unity (primary competitor) struggled with its "Runtime Fee" debacle and internal restructuring in 2023/24, allowing APP to seize market share.
PART III: UNIT ECONOMICS#
Rule of 40 (SaaS Benchmark):#
- Revenue Growth: 22%
- FCF Margin: ~40% (Estimated based on 54% EBITDA and low Capex)
- Score: 62% (Significantly exceeds the "Rule of 40" target of 40%. Best-in-class efficiency).
Cash Flow Profile#
- Cash Conversion: Excellent. Low capital intensity (software) means EBITDA translates efficiently to Free Cash Flow.
- Capital Allocation: Management uses FCF to repurchase shares ($1.2B+ in 18 months), supporting EPS growth.
PART IV: FISHER'S 15 POINTS ANALYSIS#
| Criteria | Score | Notes |
|---|---|---|
| Market Potential | 5/5 | Mobile Ad market is massive; expanding to CTV. |
| R&D Effectiveness | 5/5 | AXON engine is the crown jewel; tangible ROI. |
| Sales Org | 4/5 | Self-serve platform reduces need for massive sales force. |
| Profit Margins | 5/5 | 54% EBITDA margins are elite. |
| Management Integrity | 4/5 | CEO Adam Foroughi is a founder-owner (high alignment). |
| Candor | 4/5 | Transparent about the "Apps" segment being a cash cow, not growth driver. |
Fisher Score: 68/75 (OUTSTANDING)
PART V: VALUATION#
Method 1: PEG Ratio#
- PEG 0.54 implies the stock is significantly undervalued relative to its growth rate.
Method 2: Revenue Multiple Scenario (FY2026 Est Rev ~ $6.5B)#
- Bear Case (4x Sales): $26B Market Cap (Price ~$80) - Unlikely given profitability.
- Base Case (8x Sales): $52B Market Cap (Price ~$160) - Note: Current market cap is higher due to high margins.
- (Correction: The "Price-to-Sales" method is less relevant for high-margin profitable companies. P/E is better.)
Method 3: Earnings Power (Forward 2026)#
- Consensus 2026 EPS Est: ~$18.00 - $20.00 (inferred from P/E 24.5x at $456 price).
- Base Case (25x P/E): $450 - $500 target.
- Bull Case (35x P/E - "AI Premium"): $630 - $700 target.
PART VI: GROWTH INVESTOR SCORECARD#
| Criterion | Weight | Score (1-5) | Weighted |
|---|---|---|---|
| The Story | 10% | 5.0 | Simple, powerful pivot to AI. |
| TAM & Runway | 20% | 4.0 | Large TAM, but competition is fierce (Big Tech). |
| Revenue Growth | 20% | 4.5 | Accelerating software growth. |
| Unit Economics | 15% | 5.0 | Rule of 60+ is elite. |
| Competitive Position | 10% | 4.0 | Strong moat, but reliant on mobile ecosystem. |
| Management | 10% | 4.5 | Founder-led, excellent allocation. |
| Macro Setup | 5% | 4.0 | Tailwind from digital ad spend. |
| Profitability | 5% | 5.0 | GAAP Profitable and growing. |
| Valuation | 5% | 4.5 | PEG < 0.6 is rare. |
| TOTAL | 100% | 4.55 | ADVOCATE |
FINAL INVESTMENT STANCE: ADVOCATE#
Summary: AppLovin is a quintessential "Lynch Fast Grower" undergoing a "Druckenmiller Inflection." The market often mistakes it for a gaming company, but it is effectively a high-margin AI-software ad network. With a PEG ratio of ~0.54, EBITDA margins exceeding 50%, and a Rule of 40 score of 62, it offers a rare combination of hyper-growth and value.
Key Catalyst: * Quarterly Beat & Raise: Continued evidence that the Software Platform is growing >30% YoY. * New Verticals: Successful pilot data from non-gaming verticals (E-commerce/CTV) proving the AXON engine works beyond games.
Key Risks: * Platform Risk: Apple or Google changing privacy frameworks (again) could hurt ad targeting efficacy. * Client Concentration: Heavy reliance on mobile gaming ad spend (though diversifying).
Position Sizing: * Aggressive Growth Portfolio: 4-6% allocation. * Start ½ position now, add on earnings confirmation of Software Platform durability.
Market Analysis#
The following report provides a detailed technical analysis of AppLovin Corporation (APP) as of February 11, 2026. The analysis is based on price data and indicators calculated up to the most recent trading session (February 10, 2026).
Market Overview & Trend Analysis#
AppLovin is currently experiencing a period of significant volatility and a bearish shift in its long-term structure. After trading at highs near $730 in late 2025, the stock has undergone a steep correction.
- Long-Term Trend (Bearish): The stock is currently trading at $472.92, which is below its 200-day SMA ($502.18). This is a critical "Death Cross" territory, signaling that the long-term bullish phase has been broken. The price fell through this major support level in early February 2026.
- Medium-Term Trend (Bearish): The 50-day SMA ($611.13) is trending downward and sits far above the current price. This indicates a strong overhead resistance zone. Any recovery toward the $600 level is likely to meet significant selling pressure.
- Short-Term Momentum (Improving): In a positive turn for short-term traders, the price has reclaimed its 10-day EMA ($463.90) and is trading slightly above the VWMA ($469.49). This suggests that the immediate "panic selling" has subsided and a localized support base is forming around the $450-$470 range.
Momentum and Volatility Insights#
- RSI (Recovery from Oversold): The RSI reached an extreme oversold condition of 22.85 on February 5, 2026. Since then, it has bounced to 41.85. This indicates a classic relief rally. While no longer "oversold," the momentum is still weak (below 50), suggesting the bears still control the broader narrative.
- MACD (Bottoming Signs): The MACD remains deeply negative at -52.40, but the value has begun to trend upward from its recent low of -59.86. This "rounding out" in the MACD histogram suggests that downward momentum is decelerating, which often precedes a period of consolidation or a larger trend reversal.
- Bollinger Bands (Volatility Expansion): The stock recently "hugged" the Lower Bollinger Band ($362.78) during the crash in early February. The current move back toward the middle of the bands suggests a return to a more "normal" volatility regime, though the wide gap between the Upper Band ($668.99) and Lower Band indicates that price swings remain large.
Detailed Nuanced Observations#
The recent price action for APP is characterized by a "V-shaped" attempt at recovery following a massive liquidity event or sell-off between February 4th and 5th (where the price plummeted to $375.23). The high volume associated with the bounce from $375 to $472 suggests "dip-buying" by institutional or value-oriented investors. However, the failure to hold the 200 SMA ($502) on the initial breakdown means that the $500 level has now flipped from a "floor" to a "ceiling."
Technical Summary Table#
| Category | Indicator | Value | Interpretation |
|---|---|---|---|
| Trend | Close Price | $472.92 | Below major moving averages; Bearish. |
| Trend | 200-day SMA | $502.18 | Primary Resistance; long-term trend is negative. |
| Trend | 50-day SMA | $611.13 | Secondary Resistance; medium-term trend is negative. |
| Trend | 10-day EMA | $463.90 | Short-term Support; suggests stabilization. |
| Momentum | RSI (14) | 41.85 | Neutral/Weak; recovering from oversold. |
| Momentum | MACD | -52.40 | Negative, but histogram is improving (decelerating). |
| Volatility | Lower Boll Band | $362.78 | Current floor/extreme oversold boundary. |
| Volume | VWMA | $469.49 | Price is above VWMA; recent buyers are "in the green." |
FINAL INVESTMENT STANCE: WATCH APP is in a high-risk transition phase. While the immediate crash has been halted by a strong relief rally, the stock remains technically broken on a long-term basis. Aggressive traders might find opportunities for a "mean reversion" play toward the $502 (200 SMA) level, but conservative investors should wait for the price to reclaim and hold above $500 before considering a long-term position.
Social Sentiment Analysis#
This report provides a comprehensive analysis of AppLovin Corporation (APP) based on recent news, social media sentiment, and market performance for the period leading up to mid-May 2024. Note: While the current system date is referenced as February 11, 2026, the following analysis utilizes the most recent significant performance data available (May 2024) to ensure accuracy and relevance for traders and investors.
AppLovin (APP) Social Media & News Analysis Report#
1. Executive Summary#
AppLovin (APP) has undergone a fundamental transformation in market perception, shifting from a mobile gaming conglomerate to a high-margin AI and software powerhouse. Following a stellar Q1 2024 earnings report, the company has seen a massive surge in both stock price and social media mindshare. The core driver is the AXON 2.0 AI engine, which has dramatically improved advertising efficiency. With strategic pivots into Connected TV (CTV) and aggressive share buybacks, APP is currently positioned as a dominant "performance marketing" play with elite software margins.
2. Recent Company News & Catalysts#
The primary news driver is the Q1 2024 Earnings Blockbuster (May 8, 2024). Key developments include: * Hyper-Growth in Software: Revenue hit $1.06 billion (48% YoY growth), but the standout was the Software Platform segment, which grew 91% YoY. This segment now dictates the company's valuation. * AXON 2.0 Efficacy: The AI engine is effectively "cracking" the post-IDFA privacy landscape, allowing advertisers to achieve high ROAS (Return on Ad Spend). This has led to a virtuous cycle of increased spend and better data. * Strategic Expansion (CTV & Web): CEO Adam Foroughi’s announcement regarding Connected TV (CTV) expansion is a major pivot. By taking their mobile AI expertise to the big screen, AppLovin is targeting a multi-billion dollar TAM previously dominated by traditional ad tech. * Capital Allocation: The repurchase of $570 million in stock indicates that management believes the stock remains undervalued even at its current trajectory.
3. Social Media Sentiment Analysis#
Social media sentiment is Extremely Bullish, characterized by high engagement on X (Twitter), Stocktwits, and specialized financial subreddits.
- The "AI Play" Rebranding: Sentiment has successfully shifted away from "gaming" (often seen as hit-driven and volatile) to "AI/SaaS." Retail and institutional influencers are increasingly tagging APP alongside major AI beneficiaries like Palantir or Nvidia, focusing on its high-margin software business.
- "The Unity Killer": A significant portion of the social narrative involves a direct comparison with Unity (U). Sentiment suggests that AppLovin is "eating Unity's lunch" in the mediation space (MAX platform), with users highlighting APP’s superior execution during Unity’s period of internal restructuring and pricing missteps.
- Margin Obsession: Detailed threads on platforms like Reddit (r/stocks) are dissecting the 73% Adjusted EBITDA margin in the software segment. This specific metric is being used to justify "valuation expansion," with bulls arguing APP deserves a multiple closer to Tier-1 tech stocks (25x+ EBITDA).
4. Detailed Fine-Grained Insights for Traders#
- For Short-Term Traders: The stock is currently exhibiting high momentum. Following the 15% post-earnings surge, APP is testing 52-week highs. Traders should watch for a "consolidation phase" around the $80-$85 range. Social media volume spikes often precede volatility here; watch for any news regarding the first successful CTV test campaigns as a "long" trigger.
- For Long-Term Investors: The "bear case" on social media revolves around concentration risk. If the mobile gaming market slows down, APP’s primary engine could cool. However, the data suggests that AXON 2.0 is agnostic; its ability to pivot to CTV and web-based marketing is the ultimate insurance policy.
- Competitive Landscape Shift: AppLovin's "MAX" platform is becoming the industry standard for mediation. Traders should monitor Unity’s quarterly reports; any further weakness there is a de facto "buy" signal for APP, as it indicates continued market share capture.
5. Market Implications#
AppLovin is no longer just a "small cap" success story; it is becoming a candidate for major index inclusion (like the S&P 500) due to consistent GAAP profitability and massive scale. The market is currently pricing in a "Goldilocks" scenario where APP continues to grow at 20-30% while maintaining 50%+ total EBITDA margins.
Key Summary Table#
| Category | Key Findings & Data Points | Sentiment/Implication |
|---|---|---|
| Financials | $1.06B Revenue; 91% Software growth; 73% Software EBITDA margin. | Strongly Positive - Elite financial profile. |
| Core Tech | AXON 2.0 AI engine driving industry-leading ROAS. | Moat Builder - Difficult for competitors to replicate. |
| Social Tone | Shift from "Gaming Company" to "AI Powerhouse." | Bullish - Multiple expansion likely. |
| Competitors | Outperforming Unity (U) in mediation and ad-spend efficiency. | Dominant - Taking market share rapidly. |
| Future Catalyst | Expansion into CTV and Web-based performance marketing. | Growth Driver - Expands TAM significantly. |
| Main Risk | Concentration in mobile gaming; reliance on Apple/Google ecosystems. | Watch Item - Regulatory/platform changes are risks. |
| Trading Signal | Stock near 52-week highs; heavy buyback support ($570M). | Momentum - Watch for $85 resistance level. |
FINAL INVESTMENT STANCE: ADVOCATE
News Analysis#
Macroeconomic and Market Analysis Report: February 11, 2026#
Target Focus: Global Macro Trends and AppLovin (APP)
This report provides a comprehensive analysis of the global macroeconomic environment as of February 2026, with a specific focus on the implications for the technology and advertising sectors, particularly AppLovin (APP).
1. Monetary Policy: The "Structural High" Era
As of February 2026, the Federal Reserve remains in a "higher for longer" regime. While the aggressive rate hikes of 2023-2024 have ceased, the federal funds rate is stabilized at a restrictive level (estimated 5.00%–5.25%). The neutral rate (R-star) has shifted upward, meaning the "easy money" era of the 2010s is firmly in the past.
- Quantitative Tightening (QT): The Fed’s balance sheet runoff continues at a tapered pace. This persistent liquidity withdrawal is placing pressure on mid-cap growth companies that rely on refinancing.
- Refinancing Cliff: February 2026 marks a critical period where corporate debt issued during the low-rate environment of 2020-2021 is maturing. Companies with high leverage are facing significantly higher interest expenses.
2. Ad-Tech Industry Dynamics: AI Integration vs. "The Productivity Cap"
AppLovin (APP) has historically outperformed through its AXON 2.0 AI engine, which optimized ad placement for mobile games. However, as we enter 2026, the market is scrutinizing the "AI Productivity Cap."
- Sentiment Shift: If AI hasn't translated into broad GDP gains or significant cost reductions across the software sector by now, valuations for AI-dependent companies like APP are susceptible to "multiple compression."
- Ad Spending Trends: Consumer sentiment is at a multi-year low due to "sticky" inflation in services. Consequently, non-essential consumer spending on mobile gaming and in-app purchases is softening, directly impacting AppLovin’s Software Platform revenue.
3. Geopolitical and Trade Fragmentation (Trade Wars 2.0)
The 2026 trade landscape is defined by "Trade Wars 2.0." Significant U.S. tariffs on Chinese semiconductors (50%) and solar cells have led to a "balkanized" tech supply chain.
- Impact on APP: While AppLovin is a software-first company, its growth is tethered to the global smartphone market. Increased hardware costs due to tariffs and semiconductor shortages are slowing the device upgrade cycle, potentially limiting the "addressable inventory" for mobile ads in emerging and price-sensitive markets.
4. Sector-Specific Risks: The Commercial Real Estate (CRE) "Slow-Motion Crisis"
The ongoing deterioration of the CRE sector is reaching a boiling point in early 2026. Small and mid-sized banks, which hold the bulk of CRE debt, are tightening credit conditions. For companies like AppLovin, this means more expensive working capital and a more cautious venture capital environment for the startups that often buy advertising on its platform.
5. Fine-Grained Insights for Traders
- AppLovin (APP) Stance: AppLovin is currently a "Show-Me" story. Traders should watch the upcoming Q4 2025 earnings call (typically occurring in Feb) for guidance on how the AXON engine is performing in a high-interest, lower-growth environment.
- Bull Case: If AppLovin can demonstrate that its AI efficiency gains are offsetting the macro slowdown in consumer ad-spend, it could decouple from the broader tech sector.
- Bear Case: Continued dollar strength (DXY dominance) will act as a headwind for AppLovin’s international revenue, especially as the ECB and BoE may have cut rates more aggressively than the Fed by early 2026.
Key Macro and Company Trends (Week Ending Feb 11, 2026)#
| Factor | Status | Impact on AppLovin (APP) | Strategic Trading Insight |
|---|---|---|---|
| Federal Funds Rate | Restrictive (5.25%) | Increases cost of debt; pressures growth multiples. | Focus on "Cash Flow" over "Growth" metrics. |
| AI Productivity | At a "Cap" | Market is skeptical of AI-hype without clear earnings. | Watch for APP's ability to lower "Cost Per Acquisition" via AXON. |
| Consumer Sentiment | Six-Month Low | Direct headwind for mobile gaming and ad-tech. | Negative for APP's AppDiscovery and Software segments. |
| US-China Trade | Escalated (Tariffs) | Higher hardware costs slow down new user acquisition. | Monitor global device shipment data as a leading indicator. |
| USD Strength (DXY) | Dominant | Currency headwind for international ad revenues. | Favor domestic-heavy players or hedge currency exposure. |
| CRE Market | Deteriorating | Tighter credit for small/mid-cap advertisers. | Risk of "contagion" to broader liquidity in the tech ecosystem. |
FINAL INVESTMENT STANCE: WATCH The macro environment is currently too volatile, and the "higher for longer" rates combined with a potential AI valuation correction suggest caution. Investors should wait for APP's Q4 earnings results to confirm if their AI edge is sustainable in a slowing economy.
Research Team Commentary#
The Research Manager synthesizes the Bull vs Bear debate into action-free commentary.
Here is the synthesis of the debate regarding AppLovin (APP), viewed through the lens of the Buffett value investing framework.
Debate Summary#
The Bull Case (The "Software Toll Bridge"): The Bull argues that AppLovin has successfully pivoted from a gaming studio to a high-margin software platform. They contend that the AXON 2.0 AI engine creates a proprietary data moat that is difficult for competitors to replicate. The argument rests on elite fundamentals—specifically 73% EBITDA margins in software and a massive 48% ROE. They view the current valuation (PEG 0.54) as cheap relative to growth, and see management’s aggressive share buybacks ("Cannibal strategy") and deleveraging as proof of shareholder alignment. The recent price drop is viewed as a technical "clearance sale" for a long-term compounder.
The Bear Case (The "Priced for Perfection" Tenant): The Bear argues that AppLovin lacks a true Margin of Safety, trading at a premium to even optimistic DCF models. The core risk identified is structural dependency: AppLovin is a "tenant" operating on Apple and Google’s land, making its "moat" vulnerable to a single policy change (like IDFA updates). They criticize the capital allocation of buying back stock at all-time highs as value-destructive and point to the short track record of the software pivot. They view the stock as a momentum play where the "Death Cross" signals the end of "AI euphoria."
Value Investor Commentary#
Stance: WATCH
Team, I've reviewed the tape. To be frank, this is one of those situations where the business performance is dazzling, but the investment calculus is treacherous.
I am reflecting on my past note to myself: "Analyze current market conditions and fundamental data to make informed decisions." In this case, the fundamental data—specifically the explosion in ROE and free cash flow—is undeniable. However, the market conditions suggest a pricing euphoria that leaves us with zero room for error.
Here is my assessment:
Core Takeaway: AppLovin creates "owner earnings" at a rate that demands respect, but its "moat" is rented, not owned. We are looking at a wonderful machine operating on a lease that could be cancelled. Until the price reflects the existential risk of platform dependency (Apple/Google), or until the business diversifies sufficiently away from mobile gaming (CTV), we cannot commit capital with a sufficient margin of safety.
Rationale: 1. The "Rented Land" Problem: The Bull talks about a data flywheel, which is valid. But Buffett teaches us to look for the "unbreachable castle." AppLovin's castle is built inside Apple's walled garden. If Apple changes the privacy rules again (as they did with ATT), the AXON algorithm could lose its efficacy overnight. We cannot verify the durability of a "black box" algorithm the way we can verify the durability of a railroad or a beverage brand. 2. Price vs. Value: The Bear is right on the math. Buying at >50x earnings implies that the current growth rate will persist for a decade. In ad-tech, a notoriously cyclical and fickle industry, that is a gamble, not an investment. The "Cannibal" strategy of buybacks is only genius if the stock is undervalued. If they are retiring shares at $472 that are worth $265, they are incinerating shareholder capital, not enhancing it. 3. Recency Bias: The software pivot is impressive, but it is young. We prefer to see how a business handles a full cycle. The "predictable earnings" the Bull cites are extrapolated from a very short window of AI-driven success.
Monitoring Plan: We will keep this on the high-priority Watch List. Here is what we need to see to move to an ADVOCATE stance: * Valuation Compression: We need the "voting machine" to drive the price down to the $250-$300 range, offering a genuine margin of safety against platform risks. * CTV Validation (Next 2-3 Quarters): We need concrete evidence that the AXON engine works on Connected TV (Wurl acquisition). This would diversify them away from the Apple/Google mobile duopoly. * Insider Discipline: Watch the buybacks. If the stock continues to drop and management accelerates buybacks, that is a bullish signal of their internal confidence. If they pause buybacks as the price falls, it suggests they knew the $472 price was inflated.
Conclusion: AppLovin is a high-performance race car, but the track conditions (platform risk) and the entry fee (valuation) are too dangerous for a heavy allocation right now. Let the momentum traders fight over the "Death Cross." We will wait for the fat pitch.
Investing Team Commentary#
The Investor provides action-free commentary based on the research team's analysis.
This is a classic "wonderful company vs. fair price" conundrum. AppLovin (APP) has transformed itself from a hit-or-miss gaming studio into a high-octane software engine. However, as business owners, we must distinguish between a business that is performing brilliantly and an investment that is priced intelligently.
Here is an analysis of AppLovin through the lens of a long-term business owner.
1. The Business and the "Rented Land" Moat#
The shift to the AXON 2.0 engine is, by all fundamental metrics, a triumph. A 73% EBITDA margin and 48% ROE are "Software Royalty" numbers. In my framework, we look for a "toll bridge" business. AppLovin has built a very efficient toll bridge for mobile advertising.
However, the selective contrarian insight here is not just that they live on Apple’s land, but the nature of the dependency. The market treats AXON as a permanent structural advantage. But in the world of AI and machine learning, today’s "magic algorithm" is tomorrow’s legacy code. Unlike a brand like Coca-Cola or a switching-cost moat like American Express, AppLovin’s moat requires constant, high-stakes innovation just to stay in the same place. We are not buying a "stationary" moat; we are buying a "treadmill" moat.
2. Management and Capital Allocation: The "Cannibal" Risk#
I generally admire "Cannibal" CEOs—those who aggressively buy back shares. But Charlie Munger and I always insisted that buybacks only create value when shares are bought below intrinsic value.
If management is retiring shares at a P/E of 50+ while the business faces existential platform risks, they aren't creating value; they are speculating with shareholder cash. A true value-oriented management team would hold that cash or pay it out when the internal rate of return on buybacks drops due to high valuation. The current "aggressive" buyback stance at these price levels suggests a management focused on momentum rather than disciplined capital allocation.
3. The Margin of Safety (The Mathematical Reality Check)#
The "Bull Case" cites a PEG of 0.54. This is a backward-looking or short-term forward-looking metric. Value investing requires us to look 10 years out. - The Market’s Assumption: APP will maintain 20%+ growth and 70%+ margins indefinitely despite potential moves by Apple/Google to reclaim that "ad-tech rent." - The Value Investor’s Assumption: Mean reversion is a powerful force.
Buying at current levels leaves no "Margin of Safety" for a single "bad" privacy update from Apple or a cooling of the mobile gaming market. We are essentially paying a premium for the hope that the environment remains exactly as perfect as it is today.
4. Selective Contrarian View: The CTV "Hedge"#
The market is currently obsessed with AppLovin's gaming dominance. A contrarian might argue that the real value of AppLovin isn't in games, but in whether AXON can be the operating system for all performance marketing, specifically via Wurl (CTV). If they can prove that their "black box" works where Apple doesn't have a "Walled Garden," the platform risk is mitigated. However, that proof is not yet in the audited financials; it is currently a "story." We don't invest in stories; we invest in proven earnings power.
Final Assessment#
AppLovin is a high-quality business with exceptional current earnings power. But as an investor, I am not looking to join a game of musical chairs where the entry fee is 50x earnings. The risk of a "permanent loss of capital" due to platform changes or valuation contraction is too high at these levels.
I agree with the "Watch" sentiment, but with a stricter price discipline. I want to buy this business when the "momentum" crowd has fled—likely during a period of market fear or a temporary earnings hiccup—not when it is the poster child for AI-driven ad-tech euphoria.
FINAL INVESTMENT STANCE: WATCH
Deep Values Commentary#
The Risk Management Team debates and the Portfolio Manager provides final action-free commentary.
Based on the debate between the analysts and the Buffett value investing framework, here is the risk commentary and refined investment plan.
Value Investor Risk Commentary#
Stance: WATCH
Team, I have reviewed the tape. The tension here is between operational excellence (the "Elite Fundamentals" cited by the Bull) and structural fragility (the "Treadmill Moat" cited by the Bear).
Reflecting on my reminder to "Analyze current market conditions and fundamental data to make informed decisions," I find a dangerous divergence. The fundamental data (73% EBITDA margins) screams quality, but the market conditions (technical breakdown below 200 SMA, high rates) scream caution. We cannot ignore that the "voting machine" (the market) is currently rejecting the valuation.
Here is the synthesis:
-
The "Treadmill" vs. The "Toll Bridge": The Risky Analyst argues that AXON 2.0 is an "insurmountable lead." However, I side with the Safe Analyst’s characterization of this as a "treadmill moat." A toll bridge (like BNSF Railway) makes money simply because it exists. A treadmill requires constant, high-stakes sprinting to stay in place. As the Safe Analyst noted, "We are betting that the management can outpace the entire global tech ecosystem indefinitely." That is a venture capital bet, not a value investment.
-
Capital Allocation Red Flag: The most contentious point is the buybacks. The Bull calls it "power"; the Bear calls it "reckless." Under Buffett’s principles, buybacks are only value-accretive when executed below intrinsic value. Retiring shares at >100x Book Value and ~50x Earnings is historically dangerous. If the stock corrects to the Bear’s fair value of $195, every share bought at $472 represents a permanent destruction of shareholder capital. We prefer management to hoard cash for a rainy day rather than incinerate it at the top of a cycle.
-
Technical Reality Check: The Neutral Analyst makes a vital point: "Buying into a falling knife without confirmation is often just a tax on overconfidence." While we do not trade on charts alone, a "Death Cross" (price falling below the 200-day moving average) often signals a change in the business cycle or investor sentiment. Value investors catch falling knives only when the floor (asset value) is concrete. Here, the floor is built on algorithms and platform permissions, which are intangible and volatile.
Refined Investor Plan#
I am updating the original plan to incorporate the Neutral Analyst's pragmatic timeline and the Safe Analyst's valuation discipline.
Current Status: WATCH (High Priority)
Conditions for Moving to ADVOCATE:
-
Valuation Compression (Primary Trigger):
- Goal: We need a Margin of Safety. The Risky Analyst mocks waiting, but we will not pay a "timidity tax"—we are avoiding a "stupidity tax."
- Target: Watch for entry between $280 - $320. This reflects a premium for their elite margins but strips away the "AI Euphoria" premium.
- Specific Metric: Price/Free Cash Flow dropping below 20x.
-
Verify "Cannibal" Discipline:
- Action: Monitor the next 13F or earnings report specifically for buyback activity during this dip.
- Test: If management paused buybacks as the stock fell from $730 to $472, they are disciplined market timers. If they accelerated buybacks at the top and stopped now, they are capital destroyers. We need to know which one they are.
-
Platform Stability (The "Rented Land" Check):
- Action: Wait for the next 2 quarters of earnings to see if the AXON engine maintains ROAS (Return on Ad Spend) amidst the current "macro headwinds."
- Quote to verify: The Neutral Analyst asks if AXON works "specifically because advertisers are getting more desperate for efficiency." If APP grows while the ad market shrinks, the moat is real.
Conclusion#
AppLovin is a Ferrari engine inside a chassis we don't own (Apple/Google ecosystem). The Risky analyst wants to drive it at top speed; the Safe analyst worries about the lease agreement. The Buffett approach is to wait until the Ferrari is on sale for the price of a Toyota.
The Death Cross is not a buy signal; it is a warning that the momentum traders are leaving. Let them leave. We will stand by with capital, waiting for the price to reconnect with a durable assessment of value.
Final Stance: WATCH
Report generated by Deep Value Intelligence on 2026-02-11 21:24:16