
Company Research JNJDeep Value Intelligence
Johnson & Johnson (JNJ) Deep Value Intelligence Report
In brief
DeepValues Research published a Deep Value Intelligence report on Johnson & Johnson (JNJ) on Feb 15, 2026. Johnson & Johnson remains the "Fortress Balance Sheet" standard of the healthcare industry.
Source: https://research.deepvalues.ai/company/jnj/2026-02-15-en/ · Markdown · More on Johnson & Johnson (JNJ)
Key takeaways
Johnson & Johnson remains the "Fortress Balance Sheet" standard of the healthcare industry. Following the successful spin-off of Kenvue (Consumer Health), JNJ has transformed into a higher-margin, two-pillar compounding machine focused on Innovative Medicine (Pharma) and MedTech.
Despite the "patent cliff" fears surrounding Stelara, the company has successfully navigated the transition through disciplined M&A (Abiomed, Shockwave) and organic pipeline successes (Darzalex, Carvykti). With a AAA credit rating (one of only two U.S. companies), a dividend yield of 3.15%, and trading at ~15.2x Earnings—a discount to its historical average—JNJ represents a classic Buffett play: A wonderful company at a fair price.
Contents
- Intelligence Summary
- Analyst Team Reports
- 10-Year Historical Financial Analysis: Johnson & Johnson (JNJ)
- EXECUTIVE SUMMARY
- PART I: THE BUFFETT FILTER SEQUENCE (Go/No-Go Gates)
- PART II: FINANCIAL ANALYSIS (10-Year Deep Dive)
- PART III: INTRINSIC VALUE CALCULATION
- PART IV: FINAL SCORECARD & DECISION
- PART I: LYNCH CLASSIFICATION SYSTEM
- PART II: DRUCKENMILLER FRAMEWORK (Macro + Inflection)
- PART III: TAM ANALYSIS
- PART IV: UNIT ECONOMICS (Pharma/MedTech Context)
- PART V: FISHER'S 15 POINTS
- PART VI: VALUATION
- PART VII: GROWTH INVESTOR SCORECARD
- PART VIII: RISKS & CATALYSTS
- Comprehensive Analysis Report: Johnson & Johnson (JNJ)
- Research Team Commentary
- Investing Team Commentary
- Deep Values Commentary
Intelligence Summary#
Thesis + Conditions#
Core Thesis: Here is the risk commentary and synthesis based on the debate and value investing principles.
Key Risks: - Here is the risk commentary and synthesis based on the debate and value investing principles. - The Bull Case (Momentum & Transformation): The Risky Analyst views JNJ as a "new" company—a lean, high-margin powerhouse in MedTech and Pharma, shed of its slow consumer division. They argue the $243 price reflects a necessary re-rating for a AAA asset in a "flight to safety" market. They view the $6.48B talc settlement as effectively done ("inked"), removing the legal discount, and interpret the high RSI (81+) as institutional "conviction" rather than overextension. - 1. The "Safety" Paradox: The Risky Analyst claims JNJ is a "safe" buy because of its AAA rating. However, safety is a function of price, not just credit rating. As the Safe Analyst noted, "Buying at $243.45 is the opposite of a safe entry." When you pay 22x earnings for a company growing at 5-6%, you are relying on a "greater fool" to pay 25x later. That is speculation, not investing. - 2. Litigation Ambiguity: I side with the Safe Analyst regarding the "Texas Two-Step." The Risky Analyst’s claim that the deal is "officially inked" is premature optimism. In value investing, we treat uncertain liabilities as active risks until the cash leaves the bank and the courts close the docket. Paying a premium for a "ring-fenced" liability that hasn't actually been finalized is a violation of our Margin of Safety. - [{'type': 'text', 'text': '### Investor Commentary\n\nStance: WATCH\n\nCore Takeaway:\nJohnson & Johnson remains a Tier-1 institution, but price is what you pay, and value is what you get. Currently, the gap between the price ($243) and the intrinsic value (likely $185-$195) is too wide to cross. We are witnessing a "flight to safety" paradox where the crowd has bid up a defensive stock to an offensive valuation, destroying the very safety they seek.\n\nRationale:\n\n1. Violation of Margin of Safety: The most cardinal rule of our framework is violated here. The stock is trading at ~22x earnings with an RSI over 81, suggesting extreme overheating. As the Safe Analyst noted, "laws of gravity haven't changed." We are being asked to pay for ten years of perfect execution upfront. We decline.\n2. The "Quality Trap" of Litigation: The Risky Analyst assumes the $6.48B settlement is the end of the road. However, until the final judicial approval is granted and appeals are exhausted, the "Texas Two-Step" remains a volatile legal maneuver. The market is pricing in certainty; we do not pay premiums for ambiguity.\n3. Capital Allocation Concerns: The acquisitions of Shockwave and Abiomed act as high-priced growth engines. We must determine if these are genuine value-adds or "empire building" to mask the Stelara patent cliff. If organic growth stalls, paying 20x+ revenues for acquisitions destroys shareholder value.\n4. Mispriced "Safety": At these levels, JNJ is a bond proxy that has become too expensive relative to the risk-free rate. A mean reversion to the 200-day moving average (approx $182) represents a potential 25% drawdown. We will not expose our capital to that risk for a 2.5% dividend yield.\n\nMonitoring Plan:\n\nWe will keep JNJ on our WATCH list. We are disciplined buyers waiting for a price that makes sense.\n\n* Target Entry Zone: We are raising our "fair value" floor slightly to acknowledge the structural shift to MedTech, but we remain disciplined. We look for a pullback to the $185–$200 range. The Neutral Analyst suggests $216, but we demand a larger Margin of Safety.\n* Integration Metrics: Monitor the "MedTech" segment specifically. We need to see if Shockwave and Abiomed are accretive to earnings excluding one-time charges. If operating margins in MedTech dip below 25%, the "empire building" thesis is confirmed.\n* Stelara vs. Pipeline: Watch the script data for Tremfya and Talvey. They must offset the Stelara cliff organically. If management announces another massive acquisition, it is a red flag that the pipeline is failing.\n* Litigation Finality: We wait for the official court ruling on the bankruptcy/settlement. No position is taken until the "Sword of Damocles" is removed or priced in via a deep discount.\n\nConclusion:**\nJNJ is a wonderful company trading at a speculative price. We will let the "momentum" traders chase the chart at $243. We will wait for the inevitable correction to buy this AAA asset when it returns to being a value investment. Patience is our edge.', 'extras': {'signature': 'EqU1CqI1Ab4+9vuUm7fc6az8MDPykb98TvFhgjWT/khRbDmyjw2ssKmT4X/JMOG8l/QoHsfHkcJe/qkXHyGJA3RhD2oZU6rBn29STlxOEEeVdKG+pLS6UCXoNuVijq+SvN5qG2JXloS6rPOIvSwgpOUFwhNYk1nHLb4Q3Oi+Wb1QclYXzl6rAzMv/tC2Q8zk/Xgn1KbJ+MdCaOjOxLisD+0VIifuSv275l3X602R27R9wCStDvqWtlYgzZnvj+Fm/6tDpT677D6EP0f1FlpgR5oJJw1qzTmlK0NJ8ZV5w5iMPyQEE6AWt8mbAtCeqzAVl2e3JgqjXPCzuhz2TkUYLus9BNIpzwkyMsoQFN0i+6DbRhUeC/pkU2ew5isNk2Woz7bKwbGTrY0sJWr0ShO5L2bK6CVv6sYb/bZjbEUEg2+Mek/RCgx6af1KiHz+EKkzPL968zCSNg8uYGNmD8u1zKLZZHaKdUZ+ODjZefzZOn56vO7B2c2T2wA9/pXk4ebnLsHEsZbIo+3mzr0lmMSvK7JbypE0ne5PBnYRbiV63p2c+AAn4PbaBpqNW+GcDodF3VeExMASrJvWtyUsHbqiQeDrbqMWflJo4W7uxJTplSckw8oUdXLzv8vhCDCBIsZQJ8nHnSlWxUNwvvGERjrP+4TvI26pY4Jw3YaRNT/uVkG6iCF5toQjOzUHCc+P8bVnyAYT7bscBQURwTqeSMw61cOmkQWFNdSxNGHrHOLiHbt4Cm9YWrqCYOyxRxpuMCJtIzurjZebtL1ba2mcc+fJkENmiEHf3H4In3MtrWM34S70yZkeWTrpi12F/kN8kfCjr4LWCPARSYquGYcb7xZ9mAgssB+4JTlLYo5303tsace6Iq7AeErRDpINkqSZa3LEufLO8Oy26VTYQWU3VJlyV+Rq1sUd7QGR3S4bmdYkY2yjHq0CgoZTKPLpGJ5Z56AhItaIORVaQeSskjxFP9Vg9g0jkkvieAsZjPBUQJB9jqcdSDhfrY7CLeTG255C5OmWLpW7ioYvgiLAMwupQt6m3OpwBsdYVVYcmsgTdYo4R0P1Dyhta33zbRV2hVnRaSGA3Vs7Mc7thxa9jt+HCszHsZz3FO7S90zlDxBD1gWbxsvkKgyu1OwWvLPmoLUJ64iC4m4Ie5HdHovwzgnFTMTCUd2zgER/c/HiEJ8cS6F3AEejXrsfiBrkkQVhvhLSUHiY5lWf1bfySF/KoUCst5FNPB1kD1EPboEX4mewVTdJtFzO+44fYAI2vsl6/C9ZpV53rysUVkAMMcJz7FjA40XW6FDAAtUMsDwvG7shd87OwYfP2mhIAN5DIaB75Ptt3SHiOhgjjJzxbVO0Nt/v9Kioa86V9+4r6eDwO/AsrzoBqRkRmOoZKtZbawp8KaIdn/0J+Qx3foMlO3xaqqIt7X7/1KgGY6D7h+lmpig1ROWIJKI+jblFJmFCAZ//HUjnqxYpBNElcV2ofAx7aRmLZymw14Amu2K0jR40rNSoBPHTp7SPXEAAtyLfHAuuuZmSBCPkCTVMdos4lWjnSkCId6VsWmAI/fKNUU6LY33auPJyIovMa4Fth19NyXy9lg9smjWdrdfXbSSxCZ/YokBuzUgUBF+LuYglz4JlGKeSWFmnit+4j3+2Ts6vgPCVlbw0QN7iDP80Ha5uuJGoh4ZwJOhbVsAZ71cYt9YEbSEZ8RKXWeSJAy0Av/bEmiAV35g64wyMDNbKhKTcAxIV/p5Xp+Mk2mFMyX8fUUuvgU1MnmzpL0P1I5IB0MC/pBGfYYCZbvM0Q7TKCP1BHPBTMmSPs1fr8Ccy6qw0u2X95SmpJXcC8v1Cqm9WJPTWzNc1YMUwZHUrZLNQjJW22rYrRCRkJOhN0MmuHPHAsRVvBoU2GLAtAoXvJxmAV7Eo/MMKyolGOQ5ihoGXzEi0YMczDDGF21x1XT7G/G9qMK4a+DtjH50EQye7gjjyBjB2O7etw3zd3oCAJczUnxJHlfEn1eun8P0Tz3SQtUJFxyL1RjOlhcxgsmjM+Yr0OFoAaG3gEycjbo4bXpOPEJlYbvxZ9R8f7iBi1B7eoGSmemFeizIarIHgNhyPZi7o7LPJVkFz9wTyjabLZCr3jJsQKE2PKDYyMnKWY0DrrfdDovRgTgfYX1cyyv0hwG2c7qOKRq4AMxc+7eJ4yyn3Wm8ReXldFsmAaVOVliF4RAuuGpgA3D91hBS5Jsq/KRWMQOTnuNN4pl9zFeUVtJNSZWaohHWpp2nDgtWjjVEk9rm7Dht/wA9B2JtnD/rw02+9IgiT239BhpbZcuTzE+r88M2TA94L+wkvsAIhh5xNNpm+6HKbN9Li8+2biNRPdqxa7BLhLipT0xFJyiYaITV+uGmKIE1jAbqsGUbRB+yjTs4+FuyXuGzIWBj1/rgrjv3z3TmSJ9pAMEMDhVw+CPKcTtp4ElrgnWDUEZvDJzHyX4t+zXk+WZiP4tZ+7VdFwRX2SIRkcex0OBx20UpmigDAFhtH+LJDLzhi3L0BafHunrY8yC9WCDVZPUPsLlVM/DnyYcAXUSqo60qmBxQCyd7sjXDuArhKcTC7GuOFDTqTKH3hqnh3grPFbl60Pz5iqPtE0NSIBHUROgZ23omQwkJ/4cYahCRpn3QQkzG/2goWabnDzBO8xjqTJpVEhxDxpWZbTuMmc8W1JvvcNlof8AC9hR9TEwR5XbGlZGUEnzOcQ4QdxGalStW8M5WBgrPLYAxtIMCvUzsjXaba3dijvHRNHocqwJz0pLcDcEXp1vjnE1uXm8DzbwUCuOd4JrdqLEJ82iQNQaT11ZC8U3Ibs1XxgMS2PjL6nHbBiQb7wx82pK255fs7JZVsdwc9vBfluN9fE2nR7ZRN8nO+i0OrGUTieCF4zeUKY8MpMJeU4fJsX2s3YRTPycVj1ReWY+C4eIvVsWOuyVDS4Z4TNYeHhBqp6LbwibmKCccWl9L4SjuyBQ3yKZy9v/ait0C7JZiLlno5wLKpPrp/TqORbx0xSqUG/+AMewbdeOPMq+yLSd3WSNY0AZb1ENuywf7lo9BDInCwBm/W1tqHefiGoHZxAnSfhRRRbaGi0dG40cYy6R4NiThwESs0LzlMD5Ua4hmagXrCtYzK28B0mEDCddU2Cd0qa+7hjdI88h7AyPVbCszmVHci2AsjYwQwfcLdfoydiX3JJRIZnH7+p30leQILVO3vxD0Qzd4VadKv6R5ZErOKlYS4h1XM0r6DNIPKYFODxjtpYxdJn56UafEdTFsCmafQVpT8aP3pcaoaypH2lX5u7IRfe2LBxMjzFo/uX1grvFe72LNyWczYxghirXVsb/U60QkcPoVtSpl8Qt4GLp8Tb0o2B32xMk+XvrRExbJJ28rDHwyvlDE2XPCgUFHzU0dbDAhULuiGxpjIQgFlGJsjzgH27xSJjzLXNs42hzKIazb3zcXEhpTtt9XnPm6MXB4gFSTtdi4B5mgtGJZYdZTk2oz0Pjlp6Vl/0ll5mqkGRMiyjEooyZnksEwFJJr8So90quwyk31SscTyvzi9WKTCyH6ozhNqMtkryh8aoyQXFjbrzsQklZJ8dLSJxleUIbMctyNHeXQnPrcaxQa02TsvJ6ZGirE6ehvmUMB4zKrn2q+dyluLCw9i0dX9tvTIGI6PwbPKvdwZFK1JWBhD8RHMeTDvkkehWFHj9qj8jeMDtkup+QZjtDxLjRiPovhbghhSosseZEvgiMTkfsyuou7yBzS3haJ/pDgpNEtzoswWFILuWk56QXfsYB5G5VOcPYgQfFh1PxYfXSEY1bjjInLIqB3zBgcKoN30QsVfAW7CLSSxXddfH53jNxQd8tCb12/Ynv/SFqLdIU6/IQuNkB6drSnUrFpMLP3x8hPEnhIl/AJm+Z9pV8Yp6R53IddxmTU1MxYgllIXqoqe9AC31d9JzfVxZdD1/yy9KFRDENPsTv2S7Y6FUSFRcbAjZKcDUZ2BkR5PuGErFnhp/e9eE33YAuQFPqoB2HPbteXbuJJWAqjYCvaurLp1qO41xfw7f2hOGR0R8ZwGgphHgyDWPj407N/f3UkLTG9fkDe6cQofsPvXCLnOZHYytcc6Dka1c55CTxohkdKRhDCT8SbJ5nnDAuYaJ+zxE4Wsvr+0ZfSWvoaV3n3iWAWT8rOowh1bBkVZ3ynZdrQruN534WOU7B9M/lMCfn2hWGMIRkZwktrTXUd8gVq1XTl6jRapLu9WKfC3HZM6HFE0yVLjtZJPKMEWVATq08CY+IBFd3iqHy5py/rYk50SGKDTa/OkT++a87jxNtOpKPOhC+y7cNpu9u6iB9l6Y1xJZvgkKOXQTb8Hc4AyMmc/DSW/MBRFWMeuf+wj8ePLv3GefaZpe9NJgalggHQ1A1ty/eydA14nPjaQfY+iY3P2zIUKQ9JsTleqOq8Dcj06rglH/CpyYtHVsB9BJsyE5eaMv5whpS0eKGbI8RzrAVtYyF6qbszxHrEGLibh7BR8dICqIwTXKMHI6JbLHqSfFfP3T1liKAb+FoW0QzrHFSP+EFumElupkKX31mzjejSTJJAZe1vuV/yQpfZVGkXRmjZ7BvjsUoYz9cYTaVfCGtoFqY+Mc1TOxmB7OiaJV4TxKca0zlFjIqDvFu5qL8iK7a2dS4ZdGadtQKQnHktgMzB4SgaNP2SnyOMug4mpZUBSXNL8ywDycr+L0d49r8M5/m4BbOpH8s1eIk86YQZ50+pjSkqeIWt4ZS1nsWpDLiujACf9brxV7s5SUlTcCi6pzo0KNNurXQ60mwUzIXHOYqTQ9KQGxg4lAysmiLGNzMeqnS//b8DgE28KIM/aencyut3KVTEG0NLsb/vZ9T8K+RJEHlMJ5eseiMYKUkNzwaY6P2NN1KodyMKtGd7Ws8b4dRwvYSockkJeZP70rZMLmHiLVV15uC/GoP2eLOOjePY+erxCzYH8kZdL3ENaQ2EFNIiRqId0EQaASritkrWWCDkrUaYdvASrBSws4A6gspPGcOLbTylTsPZmVmLKlYj5vc9Fv+zVVwpN/phNTwcaIJAQj1nOmTIvEGs1pJ1QYB4lTJfr2UjYO1pny85VWy+cc/5Cw9NuVadeq43Exb1slNGHY89ZU7StfQBj3XfhYRXFY6QGxVdGbY8dCYfPiGfrQYua2aymSFX0QX9aqQZOMXd6g7t2h2bES7BOa5zyw9gRYqTVw6PDCGWgGCqFRaJc1yrvrkwPE638GBnJhMiq+S955Hya7C7A3eNyQ4BCXu13sRfM3Vfewxkf/Lklj1Z95VrLtxQgklD2fBBYSXvjkQNJmSm1r72EXVxYrTLIfWH9JKSYguyx47uW8kF3jatmisfoW/oBU3dGVF0o8inrghuRZdUeVsco+0erp4dBBL+JHYVPnNdFq6d6mYNVk1ez6B49Oc5lQQZNEpQCTbiZes8H2S+vWz0jHoDlpub61PznAZoILnyR7mtEJTP7hFVwWWFttgM8dNsEGqkZLDQPk90mSJmeGYeRNSwlcfFo0+dtAowew/v4uzS2My0AfKP2fN23ZIOmkJraRma4rZoUujZfB2DgPnsC+7YXSPlTxuL1tVFOcLahwMOzHhQiwwmqN03AL9C8+pHvbisFVi6CbbZs+Q2z6CA+cGEZ4g6iNRZ3nHsD5fNIL5Ny9utmTS+MG9ycgMmc6ZpIL93cvwnh7fR0CAnQr5eAPB1YGdnv6uMF8znXPz4UGfGpf2sarbBVsUEnLunNuk8DKLTRsvVA5UoZa1IVbfxtBowRiYcthJvU4iUFbdJj8U54+0+UikAAbe7odFiuPbMn/G5g9g3D7aCTUUNGvoLSZ+rTgt/SCbOA/msIu1lG6A68VzCMqZ2pZpEwrnaYSSxR6B6YgO48cuY2q3x+MX71rqGeTAyG7lyZsBr2VHenC1NwxWpOmlG0pHamUIOg9IDtVpjXXO3KbBTaKS17sX+y89bpX+B25BAh6Z6llPq6LBXGNOJgoI66Jyb5TpXzjQyfJJYdAjx3GrwVvshvVfiLmMtVqYxeXQM0Xx2hTmNpX1YH3YwCNK2ie7JMwYR8xmHYib3liHa0ame6w0I+YDzGrrfhYsUkyIoZJhLS23eSN5Uatvpc6XS4GsAy7fqWSAun0/DRdov/dpxb92cTYbvJoAJw6YibzuIO+aTLq99ie2h8ZDFQNux8fvV3+uUMzLL7dwy/vRwe8x4c18LYSOV62jucPcOqReucth44lsRyLe5buM8768SeAfXpx8+zAFRtT0gtk/FMMheoz3/iGBQ6U240ubT9GOyNW7pbOTg4CPZVBFPXqJU9oJoywV264yN7C6bDGePCuIPxNraLTpTLagomow6OQj4HifJ3coC9mg0PIlXsXFyzSkLL1bjCDsVRuqb77gY16s5kuqmh72NcqoStwaYyB6PwYy8lBOQwoYRAgbbUaDzgZ58FbMFBNmhhZ98WMwtc19gQumDvetvaz0sItvFreqVlv2MjOQHDhthEVUvUeM4WUdn9sxfu5qvombgCsB8SZ37uTBbyMlcxF7FhH3Fx0fk2QOVb1MLOkEFoPvWGtO8YaY+Ppm7gUuH5h883LW7WXkHsH1e5rxbzJhLx9SuB9H+cw2MN/oLrp9dAHiXHeGv/eIYG3XjuVo+PI0APxNDKIHjcqGQqpsvE8mvoCK79iihBsqsY4npeLkWnqmxKyhoOTgTXrj0ss509BuUuAdboBiFar1oZ5svKL/SuG9/OoY9bEK0nNFPllKpbOy/gnIJZItzYpOCF/ut5FStJFbMarg/scCos5ECSUCeNEitIxx3oqFpwgCWewarA3LPQ/jbZ3o8BlycI4Xk6smpRsJbyAk8ihPRR+Ks/yGkYvffack7LTPRG4vF43OG1SvjFxY8+EXOhbKu9uJxAKgDjsoWSjFuXZ0wwF51pM/zDt7tuK9qNJX/F4CJZTSD7klmVtlwuUu7J/GBx5DV8GUoCpIk9dzBzqRYkttuOCNY2ySAhAN7NJe9PMSCQqH1pSW/HT/ZXz3V0iKq8NGaUSGA2/inRxD17Q+W0w3sEyqJVlxEg2SP5OsG8mDlivdn+L+0qVufjpPTpSVdrSFJmgLE12W68P1B/6RZx8CEdw5Baq5OFZoJhkJ53FZFmA3t9j+w4v92cToQwkfL9DpaV5gRJwyt6+XV7/ZDXnR4YdVvicIfUE+gGMyokzu3eGik/fkbI8Cgw27vz3pqxLe1vcHboVMlthyAyA89i45OdRuUeYG0BLo+SJJ8ZvXerN/3BHtKBHWpYihYdka+CC07Fj2v7Knmh/4NEzwIaOj4PTE694w1v4zO3seJW9D3my0NVMbNqJ7p33T37GXx49bSamPjyp+FOjWrrHqoBdpNZGhkflOaRanJqCqq+eF2zXkyPHE946hP6+gkVqbYTirR0pf0uAU72jzuBbNlyHMl2Dz5haOCMWIwTkzsNMufcWlVISyyduxHr3W+7SMkxTWWCFW7io08AeZQY76EWJqmgakHWVkgpox2QpaDVLevwRjeg3Ki0M3HAKP08GZrowvui0AdBLv1xvZuBlU9wiIDsF8Je1+DyJCvrpG6Dug8EJEXDidF6tRzhu5yb7CbhkglecY/R9XKrzOqf1/wqz90lZknGwbYsjeOmYBGjFWroqdlXXzqyj8JJ2SuhenHePZrpPWbIRRPWOBe2lxociC/gar0aTdfDDXD0zrFZKsbmuiPKuh8oZ8X488NLyktg0wWgmytjZzFPXtfDHyYDEO5Y12NyQl6yTCYTbuj2XQ7DSz/mW5nZ74Hb+qNUU7O5LQ2MX/ubnO8StrH1ExKkR7O+bD/gsY1gE9XQzTz2NjM2fyqxYaxj0niy74pY1zvfJbyIGIn2VagPaOFcuf9OkS/viO4WKb+/lfiO7JGoB7IYdI63kKKs1NSmgCWC07KmWa7Rdf/tBUYsJhVG+45bc9Q3l6EFGnIGKgsUA7j4fc1DvWPq2XiLdBpw5py50tZansJPT9D+uQOgbcWI3S4ckI/TRIwweE4PoBLkywyoMxG9dZyAkfaLXyHzjEqK5WPWZ8Qv322KWucd7lAL4iSMnmWMRoHdWJeJDU44HyFY0Vl0ohgcOWytxuR9ExIrZGkOa0Sard396Rt9HWCfuSV8MW2L8p9hStwijrE11NRwstZmJ1Sxe29X/NOOu3so5tL1pqiT66VFZ6rFnJTPhITNNX005QoNsp0KiGK9isWSUWi5X4K9QnBJL66jzR/oi7w7By9NTrFZoJIRdh3nyaYPPYS0UKQ8IEE0KFJSsRXQ7YSTa8jr9y1DdXDEX6jCvA8x/m6gDdhmgW+guMs6Ikp3DAyG+YpKVcW8cOR12IQSheWDpn3BVZBUBydb5rCX9jAx3jnpYjq5u7NErVrnENbn5TVx02Re/hdKALydXEd71Z+2wOtmL9WCjpkIbouPuUgmOwNQZPs02/ljKA+ZteIjhnLL8MfnMvK+1u5HG/GlG3PFfnrzdODZQCk7iNA7XdLd61JXjAf7xLqPZ+qtVDdlE03brJOmseNeUk/ht5YNaeQhYcr0L43Y0u54TeDfyrWql6cExkbZg8J/HOvaWTeqdQqTIqY2gQ9DSUiy353T1OEZ5mPcpYCSdGQIi9FNUkV6hoPoiEJbHlM0XCa8IgH4IPg/vkO0cQEbIs39404+anLdOmRm9MyGGnuCXePV8717O9vunTM5cmJFs8LM5luOIxQdBdzaV/+imNOmjwVr3CUPaoI84mDjYLvisghaOMw9kKa2r4FD+YCVpyuuNpTV1AQl167ZAc40udPXLhng4zp3DOGPM45Rp4zHXFNELUAMY7s0F4kbxwYAZZqnSoZKfmBI1VCcN/t99QgzGTy6HgA+6rK2BlGVCnAhH0fUE4R6gKXCXUB6tBoC0wVVyEUUHjAOhxh7EBEQ1v606Oxkw/PyAgwHrzoqZDzf8Fv8LtM3KtdEUnOegt6xSYqkzSg3qaNW96JCQjBvzIw1DSY5GkFX1NVFmZ6AEHVrYtal/XJuuaSsGTSg+XIU7w0rYd/TsYNmVuxwJPQpWo8ljb9n6xl2id786OggiZEupYH0yAS709xcreJ4mmobI9nTGsZ4aoU5j653EFH9nNLAi3w='}}]
What Would Change Our View: - Here is the risk commentary and synthesis based on the debate and value investing principles. - The Bull Case (Momentum & Transformation): The Risky Analyst views JNJ as a "new" company—a lean, high-margin powerhouse in MedTech and Pharma, shed of its slow consumer division. They argue the $243 price reflects a necessary re-rating for a AAA asset in a "flight to safety" market. They view the $6.48B talc settlement as effectively done ("inked"), removing the legal discount, and interpret the high RSI (81+) as institutional "conviction" rather than overextension. - 1. The "Safety" Paradox: The Risky Analyst claims JNJ is a "safe" buy because of its AAA rating. However, safety is a function of price, not just credit rating. As the Safe Analyst noted, "Buying at $243.45 is the opposite of a safe entry." When you pay 22x earnings for a company growing at 5-6%, you are relying on a "greater fool" to pay 25x later. That is speculation, not investing. - 2. Litigation Ambiguity: I side with the Safe Analyst regarding the "Texas Two-Step." The Risky Analyst’s claim that the deal is "officially inked" is premature optimism. In value investing, we treat uncertain liabilities as active risks until the cash leaves the bank and the courts close the docket. Paying a premium for a "ring-fenced" liability that hasn't actually been finalized is a violation of our Margin of Safety. - [{'type': 'text', 'text': '### Investor Commentary\n\nStance: WATCH\n\nCore Takeaway:\nJohnson & Johnson remains a Tier-1 institution, but price is what you pay, and value is what you get. Currently, the gap between the price ($243) and the intrinsic value (likely $185-$195) is too wide to cross. We are witnessing a "flight to safety" paradox where the crowd has bid up a defensive stock to an offensive valuation, destroying the very safety they seek.\n\nRationale:\n\n1. Violation of Margin of Safety: The most cardinal rule of our framework is violated here. The stock is trading at ~22x earnings with an RSI over 81, suggesting extreme overheating. As the Safe Analyst noted, "laws of gravity haven't changed." We are being asked to pay for ten years of perfect execution upfront. We decline.\n2. The "Quality Trap" of Litigation: The Risky Analyst assumes the $6.48B settlement is the end of the road. However, until the final judicial approval is granted and appeals are exhausted, the "Texas Two-Step" remains a volatile legal maneuver. The market is pricing in certainty; we do not pay premiums for ambiguity.\n3. Capital Allocation Concerns: The acquisitions of Shockwave and Abiomed act as high-priced growth engines. We must determine if these are genuine value-adds or "empire building" to mask the Stelara patent cliff. If organic growth stalls, paying 20x+ revenues for acquisitions destroys shareholder value.\n4. Mispriced "Safety": At these levels, JNJ is a bond proxy that has become too expensive relative to the risk-free rate. A mean reversion to the 200-day moving average (approx $182) represents a potential 25% drawdown. We will not expose our capital to that risk for a 2.5% dividend yield.\n\nMonitoring Plan:\n\nWe will keep JNJ on our WATCH list. We are disciplined buyers waiting for a price that makes sense.\n\n* Target Entry Zone: We are raising our "fair value" floor slightly to acknowledge the structural shift to MedTech, but we remain disciplined. We look for a pullback to the $185–$200 range. The Neutral Analyst suggests $216, but we demand a larger Margin of Safety.\n* Integration Metrics: Monitor the "MedTech" segment specifically. We need to see if Shockwave and Abiomed are accretive to earnings excluding one-time charges. If operating margins in MedTech dip below 25%, the "empire building" thesis is confirmed.\n* Stelara vs. Pipeline: Watch the script data for Tremfya and Talvey. They must offset the Stelara cliff organically. If management announces another massive acquisition, it is a red flag that the pipeline is failing.\n* Litigation Finality: We wait for the official court ruling on the bankruptcy/settlement. No position is taken until the "Sword of Damocles" is removed or priced in via a deep discount.\n\nConclusion:**\nJNJ is a wonderful company trading at a speculative price. We will let the "momentum" traders chase the chart at $243. We will wait for the inevitable correction to buy this AAA asset when it returns to being a value investment. Patience is our edge.', 'extras': {'signature': 'EqU1CqI1Ab4+9vuUm7fc6az8MDPykb98TvFhgjWT/khRbDmyjw2ssKmT4X/JMOG8l/QoHsfHkcJe/qkXHyGJA3RhD2oZU6rBn29STlxOEEeVdKG+pLS6UCXoNuVijq+SvN5qG2JXloS6rPOIvSwgpOUFwhNYk1nHLb4Q3Oi+Wb1QclYXzl6rAzMv/tC2Q8zk/Xgn1KbJ+MdCaOjOxLisD+0VIifuSv275l3X602R27R9wCStDvqWtlYgzZnvj+Fm/6tDpT677D6EP0f1FlpgR5oJJw1qzTmlK0NJ8ZV5w5iMPyQEE6AWt8mbAtCeqzAVl2e3JgqjXPCzuhz2TkUYLus9BNIpzwkyMsoQFN0i+6DbRhUeC/pkU2ew5isNk2Woz7bKwbGTrY0sJWr0ShO5L2bK6CVv6sYb/bZjbEUEg2+Mek/RCgx6af1KiHz+EKkzPL968zCSNg8uYGNmD8u1zKLZZHaKdUZ+ODjZefzZOn56vO7B2c2T2wA9/pXk4ebnLsHEsZbIo+3mzr0lmMSvK7JbypE0ne5PBnYRbiV63p2c+AAn4PbaBpqNW+GcDodF3VeExMASrJvWtyUsHbqiQeDrbqMWflJo4W7uxJTplSckw8oUdXLzv8vhCDCBIsZQJ8nHnSlWxUNwvvGERjrP+4TvI26pY4Jw3YaRNT/uVkG6iCF5toQjOzUHCc+P8bVnyAYT7bscBQURwTqeSMw61cOmkQWFNdSxNGHrHOLiHbt4Cm9YWrqCYOyxRxpuMCJtIzurjZebtL1ba2mcc+fJkENmiEHf3H4In3MtrWM34S70yZkeWTrpi12F/kN8kfCjr4LWCPARSYquGYcb7xZ9mAgssB+4JTlLYo5303tsace6Iq7AeErRDpINkqSZa3LEufLO8Oy26VTYQWU3VJlyV+Rq1sUd7QGR3S4bmdYkY2yjHq0CgoZTKPLpGJ5Z56AhItaIORVaQeSskjxFP9Vg9g0jkkvieAsZjPBUQJB9jqcdSDhfrY7CLeTG255C5OmWLpW7ioYvgiLAMwupQt6m3OpwBsdYVVYcmsgTdYo4R0P1Dyhta33zbRV2hVnRaSGA3Vs7Mc7thxa9jt+HCszHsZz3FO7S90zlDxBD1gWbxsvkKgyu1OwWvLPmoLUJ64iC4m4Ie5HdHovwzgnFTMTCUd2zgER/c/HiEJ8cS6F3AEejXrsfiBrkkQVhvhLSUHiY5lWf1bfySF/KoUCst5FNPB1kD1EPboEX4mewVTdJtFzO+44fYAI2vsl6/C9ZpV53rysUVkAMMcJz7FjA40XW6FDAAtUMsDwvG7shd87OwYfP2mhIAN5DIaB75Ptt3SHiOhgjjJzxbVO0Nt/v9Kioa86V9+4r6eDwO/AsrzoBqRkRmOoZKtZbawp8KaIdn/0J+Qx3foMlO3xaqqIt7X7/1KgGY6D7h+lmpig1ROWIJKI+jblFJmFCAZ//HUjnqxYpBNElcV2ofAx7aRmLZymw14Amu2K0jR40rNSoBPHTp7SPXEAAtyLfHAuuuZmSBCPkCTVMdos4lWjnSkCId6VsWmAI/fKNUU6LY33auPJyIovMa4Fth19NyXy9lg9smjWdrdfXbSSxCZ/YokBuzUgUBF+LuYglz4JlGKeSWFmnit+4j3+2Ts6vgPCVlbw0QN7iDP80Ha5uuJGoh4ZwJOhbVsAZ71cYt9YEbSEZ8RKXWeSJAy0Av/bEmiAV35g64wyMDNbKhKTcAxIV/p5Xp+Mk2mFMyX8fUUuvgU1MnmzpL0P1I5IB0MC/pBGfYYCZbvM0Q7TKCP1BHPBTMmSPs1fr8Ccy6qw0u2X95SmpJXcC8v1Cqm9WJPTWzNc1YMUwZHUrZLNQjJW22rYrRCRkJOhN0MmuHPHAsRVvBoU2GLAtAoXvJxmAV7Eo/MMKyolGOQ5ihoGXzEi0YMczDDGF21x1XT7G/G9qMK4a+DtjH50EQye7gjjyBjB2O7etw3zd3oCAJczUnxJHlfEn1eun8P0Tz3SQtUJFxyL1RjOlhcxgsmjM+Yr0OFoAaG3gEycjbo4bXpOPEJlYbvxZ9R8f7iBi1B7eoGSmemFeizIarIHgNhyPZi7o7LPJVkFz9wTyjabLZCr3jJsQKE2PKDYyMnKWY0DrrfdDovRgTgfYX1cyyv0hwG2c7qOKRq4AMxc+7eJ4yyn3Wm8ReXldFsmAaVOVliF4RAuuGpgA3D91hBS5Jsq/KRWMQOTnuNN4pl9zFeUVtJNSZWaohHWpp2nDgtWjjVEk9rm7Dht/wA9B2JtnD/rw02+9IgiT239BhpbZcuTzE+r88M2TA94L+wkvsAIhh5xNNpm+6HKbN9Li8+2biNRPdqxa7BLhLipT0xFJyiYaITV+uGmKIE1jAbqsGUbRB+yjTs4+FuyXuGzIWBj1/rgrjv3z3TmSJ9pAMEMDhVw+CPKcTtp4ElrgnWDUEZvDJzHyX4t+zXk+WZiP4tZ+7VdFwRX2SIRkcex0OBx20UpmigDAFhtH+LJDLzhi3L0BafHunrY8yC9WCDVZPUPsLlVM/DnyYcAXUSqo60qmBxQCyd7sjXDuArhKcTC7GuOFDTqTKH3hqnh3grPFbl60Pz5iqPtE0NSIBHUROgZ23omQwkJ/4cYahCRpn3QQkzG/2goWabnDzBO8xjqTJpVEhxDxpWZbTuMmc8W1JvvcNlof8AC9hR9TEwR5XbGlZGUEnzOcQ4QdxGalStW8M5WBgrPLYAxtIMCvUzsjXaba3dijvHRNHocqwJz0pLcDcEXp1vjnE1uXm8DzbwUCuOd4JrdqLEJ82iQNQaT11ZC8U3Ibs1XxgMS2PjL6nHbBiQb7wx82pK255fs7JZVsdwc9vBfluN9fE2nR7ZRN8nO+i0OrGUTieCF4zeUKY8MpMJeU4fJsX2s3YRTPycVj1ReWY+C4eIvVsWOuyVDS4Z4TNYeHhBqp6LbwibmKCccWl9L4SjuyBQ3yKZy9v/ait0C7JZiLlno5wLKpPrp/TqORbx0xSqUG/+AMewbdeOPMq+yLSd3WSNY0AZb1ENuywf7lo9BDInCwBm/W1tqHefiGoHZxAnSfhRRRbaGi0dG40cYy6R4NiThwESs0LzlMD5Ua4hmagXrCtYzK28B0mEDCddU2Cd0qa+7hjdI88h7AyPVbCszmVHci2AsjYwQwfcLdfoydiX3JJRIZnH7+p30leQILVO3vxD0Qzd4VadKv6R5ZErOKlYS4h1XM0r6DNIPKYFODxjtpYxdJn56UafEdTFsCmafQVpT8aP3pcaoaypH2lX5u7IRfe2LBxMjzFo/uX1grvFe72LNyWczYxghirXVsb/U60QkcPoVtSpl8Qt4GLp8Tb0o2B32xMk+XvrRExbJJ28rDHwyvlDE2XPCgUFHzU0dbDAhULuiGxpjIQgFlGJsjzgH27xSJjzLXNs42hzKIazb3zcXEhpTtt9XnPm6MXB4gFSTtdi4B5mgtGJZYdZTk2oz0Pjlp6Vl/0ll5mqkGRMiyjEooyZnksEwFJJr8So90quwyk31SscTyvzi9WKTCyH6ozhNqMtkryh8aoyQXFjbrzsQklZJ8dLSJxleUIbMctyNHeXQnPrcaxQa02TsvJ6ZGirE6ehvmUMB4zKrn2q+dyluLCw9i0dX9tvTIGI6PwbPKvdwZFK1JWBhD8RHMeTDvkkehWFHj9qj8jeMDtkup+QZjtDxLjRiPovhbghhSosseZEvgiMTkfsyuou7yBzS3haJ/pDgpNEtzoswWFILuWk56QXfsYB5G5VOcPYgQfFh1PxYfXSEY1bjjInLIqB3zBgcKoN30QsVfAW7CLSSxXddfH53jNxQd8tCb12/Ynv/SFqLdIU6/IQuNkB6drSnUrFpMLP3x8hPEnhIl/AJm+Z9pV8Yp6R53IddxmTU1MxYgllIXqoqe9AC31d9JzfVxZdD1/yy9KFRDENPsTv2S7Y6FUSFRcbAjZKcDUZ2BkR5PuGErFnhp/e9eE33YAuQFPqoB2HPbteXbuJJWAqjYCvaurLp1qO41xfw7f2hOGR0R8ZwGgphHgyDWPj407N/f3UkLTG9fkDe6cQofsPvXCLnOZHYytcc6Dka1c55CTxohkdKRhDCT8SbJ5nnDAuYaJ+zxE4Wsvr+0ZfSWvoaV3n3iWAWT8rOowh1bBkVZ3ynZdrQruN534WOU7B9M/lMCfn2hWGMIRkZwktrTXUd8gVq1XTl6jRapLu9WKfC3HZM6HFE0yVLjtZJPKMEWVATq08CY+IBFd3iqHy5py/rYk50SGKDTa/OkT++a87jxNtOpKPOhC+y7cNpu9u6iB9l6Y1xJZvgkKOXQTb8Hc4AyMmc/DSW/MBRFWMeuf+wj8ePLv3GefaZpe9NJgalggHQ1A1ty/eydA14nPjaQfY+iY3P2zIUKQ9JsTleqOq8Dcj06rglH/CpyYtHVsB9BJsyE5eaMv5whpS0eKGbI8RzrAVtYyF6qbszxHrEGLibh7BR8dICqIwTXKMHI6JbLHqSfFfP3T1liKAb+FoW0QzrHFSP+EFumElupkKX31mzjejSTJJAZe1vuV/yQpfZVGkXRmjZ7BvjsUoYz9cYTaVfCGtoFqY+Mc1TOxmB7OiaJV4TxKca0zlFjIqDvFu5qL8iK7a2dS4ZdGadtQKQnHktgMzB4SgaNP2SnyOMug4mpZUBSXNL8ywDycr+L0d49r8M5/m4BbOpH8s1eIk86YQZ50+pjSkqeIWt4ZS1nsWpDLiujACf9brxV7s5SUlTcCi6pzo0KNNurXQ60mwUzIXHOYqTQ9KQGxg4lAysmiLGNzMeqnS//b8DgE28KIM/aencyut3KVTEG0NLsb/vZ9T8K+RJEHlMJ5eseiMYKUkNzwaY6P2NN1KodyMKtGd7Ws8b4dRwvYSockkJeZP70rZMLmHiLVV15uC/GoP2eLOOjePY+erxCzYH8kZdL3ENaQ2EFNIiRqId0EQaASritkrWWCDkrUaYdvASrBSws4A6gspPGcOLbTylTsPZmVmLKlYj5vc9Fv+zVVwpN/phNTwcaIJAQj1nOmTIvEGs1pJ1QYB4lTJfr2UjYO1pny85VWy+cc/5Cw9NuVadeq43Exb1slNGHY89ZU7StfQBj3XfhYRXFY6QGxVdGbY8dCYfPiGfrQYua2aymSFX0QX9aqQZOMXd6g7t2h2bES7BOa5zyw9gRYqTVw6PDCGWgGCqFRaJc1yrvrkwPE638GBnJhMiq+S955Hya7C7A3eNyQ4BCXu13sRfM3Vfewxkf/Lklj1Z95VrLtxQgklD2fBBYSXvjkQNJmSm1r72EXVxYrTLIfWH9JKSYguyx47uW8kF3jatmisfoW/oBU3dGVF0o8inrghuRZdUeVsco+0erp4dBBL+JHYVPnNdFq6d6mYNVk1ez6B49Oc5lQQZNEpQCTbiZes8H2S+vWz0jHoDlpub61PznAZoILnyR7mtEJTP7hFVwWWFttgM8dNsEGqkZLDQPk90mSJmeGYeRNSwlcfFo0+dtAowew/v4uzS2My0AfKP2fN23ZIOmkJraRma4rZoUujZfB2DgPnsC+7YXSPlTxuL1tVFOcLahwMOzHhQiwwmqN03AL9C8+pHvbisFVi6CbbZs+Q2z6CA+cGEZ4g6iNRZ3nHsD5fNIL5Ny9utmTS+MG9ycgMmc6ZpIL93cvwnh7fR0CAnQr5eAPB1YGdnv6uMF8znXPz4UGfGpf2sarbBVsUEnLunNuk8DKLTRsvVA5UoZa1IVbfxtBowRiYcthJvU4iUFbdJj8U54+0+UikAAbe7odFiuPbMn/G5g9g3D7aCTUUNGvoLSZ+rTgt/SCbOA/msIu1lG6A68VzCMqZ2pZpEwrnaYSSxR6B6YgO48cuY2q3x+MX71rqGeTAyG7lyZsBr2VHenC1NwxWpOmlG0pHamUIOg9IDtVpjXXO3KbBTaKS17sX+y89bpX+B25BAh6Z6llPq6LBXGNOJgoI66Jyb5TpXzjQyfJJYdAjx3GrwVvshvVfiLmMtVqYxeXQM0Xx2hTmNpX1YH3YwCNK2ie7JMwYR8xmHYib3liHa0ame6w0I+YDzGrrfhYsUkyIoZJhLS23eSN5Uatvpc6XS4GsAy7fqWSAun0/DRdov/dpxb92cTYbvJoAJw6YibzuIO+aTLq99ie2h8ZDFQNux8fvV3+uUMzLL7dwy/vRwe8x4c18LYSOV62jucPcOqReucth44lsRyLe5buM8768SeAfXpx8+zAFRtT0gtk/FMMheoz3/iGBQ6U240ubT9GOyNW7pbOTg4CPZVBFPXqJU9oJoywV264yN7C6bDGePCuIPxNraLTpTLagomow6OQj4HifJ3coC9mg0PIlXsXFyzSkLL1bjCDsVRuqb77gY16s5kuqmh72NcqoStwaYyB6PwYy8lBOQwoYRAgbbUaDzgZ58FbMFBNmhhZ98WMwtc19gQumDvetvaz0sItvFreqVlv2MjOQHDhthEVUvUeM4WUdn9sxfu5qvombgCsB8SZ37uTBbyMlcxF7FhH3Fx0fk2QOVb1MLOkEFoPvWGtO8YaY+Ppm7gUuH5h883LW7WXkHsH1e5rxbzJhLx9SuB9H+cw2MN/oLrp9dAHiXHeGv/eIYG3XjuVo+PI0APxNDKIHjcqGQqpsvE8mvoCK79iihBsqsY4npeLkWnqmxKyhoOTgTXrj0ss509BuUuAdboBiFar1oZ5svKL/SuG9/OoY9bEK0nNFPllKpbOy/gnIJZItzYpOCF/ut5FStJFbMarg/scCos5ECSUCeNEitIxx3oqFpwgCWewarA3LPQ/jbZ3o8BlycI4Xk6smpRsJbyAk8ihPRR+Ks/yGkYvffack7LTPRG4vF43OG1SvjFxY8+EXOhbKu9uJxAKgDjsoWSjFuXZ0wwF51pM/zDt7tuK9qNJX/F4CJZTSD7klmVtlwuUu7J/GBx5DV8GUoCpIk9dzBzqRYkttuOCNY2ySAhAN7NJe9PMSCQqH1pSW/HT/ZXz3V0iKq8NGaUSGA2/inRxD17Q+W0w3sEyqJVlxEg2SP5OsG8mDlivdn+L+0qVufjpPTpSVdrSFJmgLE12W68P1B/6RZx8CEdw5Baq5OFZoJhkJ53FZFmA3t9j+w4v92cToQwkfL9DpaV5gRJwyt6+XV7/ZDXnR4YdVvicIfUE+gGMyokzu3eGik/fkbI8Cgw27vz3pqxLe1vcHboVMlthyAyA89i45OdRuUeYG0BLo+SJJ8ZvXerN/3BHtKBHWpYihYdka+CC07Fj2v7Knmh/4NEzwIaOj4PTE694w1v4zO3seJW9D3my0NVMbNqJ7p33T37GXx49bSamPjyp+FOjWrrHqoBdpNZGhkflOaRanJqCqq+eF2zXkyPHE946hP6+gkVqbYTirR0pf0uAU72jzuBbNlyHMl2Dz5haOCMWIwTkzsNMufcWlVISyyduxHr3W+7SMkxTWWCFW7io08AeZQY76EWJqmgakHWVkgpox2QpaDVLevwRjeg3Ki0M3HAKP08GZrowvui0AdBLv1xvZuBlU9wiIDsF8Je1+DyJCvrpG6Dug8EJEXDidF6tRzhu5yb7CbhkglecY/R9XKrzOqf1/wqz90lZknGwbYsjeOmYBGjFWroqdlXXzqyj8JJ2SuhenHePZrpPWbIRRPWOBe2lxociC/gar0aTdfDDXD0zrFZKsbmuiPKuh8oZ8X488NLyktg0wWgmytjZzFPXtfDHyYDEO5Y12NyQl6yTCYTbuj2XQ7DSz/mW5nZ74Hb+qNUU7O5LQ2MX/ubnO8StrH1ExKkR7O+bD/gsY1gE9XQzTz2NjM2fyqxYaxj0niy74pY1zvfJbyIGIn2VagPaOFcuf9OkS/viO4WKb+/lfiO7JGoB7IYdI63kKKs1NSmgCWC07KmWa7Rdf/tBUYsJhVG+45bc9Q3l6EFGnIGKgsUA7j4fc1DvWPq2XiLdBpw5py50tZansJPT9D+uQOgbcWI3S4ckI/TRIwweE4PoBLkywyoMxG9dZyAkfaLXyHzjEqK5WPWZ8Qv322KWucd7lAL4iSMnmWMRoHdWJeJDU44HyFY0Vl0ohgcOWytxuR9ExIrZGkOa0Sard396Rt9HWCfuSV8MW2L8p9hStwijrE11NRwstZmJ1Sxe29X/NOOu3so5tL1pqiT66VFZ6rFnJTPhITNNX005QoNsp0KiGK9isWSUWi5X4K9QnBJL66jzR/oi7w7By9NTrFZoJIRdh3nyaYPPYS0UKQ8IEE0KFJSsRXQ7YSTa8jr9y1DdXDEX6jCvA8x/m6gDdhmgW+guMs6Ikp3DAyG+YpKVcW8cOR12IQSheWDpn3BVZBUBydb5rCX9jAx3jnpYjq5u7NErVrnENbn5TVx02Re/hdKALydXEd71Z+2wOtmL9WCjpkIbouPuUgmOwNQZPs02/ljKA+ZteIjhnLL8MfnMvK+1u5HG/GlG3PFfnrzdODZQCk7iNA7XdLd61JXjAf7xLqPZ+qtVDdlE03brJOmseNeUk/ht5YNaeQhYcr0L43Y0u54TeDfyrWql6cExkbZg8J/HOvaWTeqdQqTIqY2gQ9DSUiy353T1OEZ5mPcpYCSdGQIi9FNUkV6hoPoiEJbHlM0XCa8IgH4IPg/vkO0cQEbIs39404+anLdOmRm9MyGGnuCXePV8717O9vunTM5cmJFs8LM5luOIxQdBdzaV/+imNOmjwVr3CUPaoI84mDjYLvisghaOMw9kKa2r4FD+YCVpyuuNpTV1AQl167ZAc40udPXLhng4zp3DOGPM45Rp4zHXFNELUAMY7s0F4kbxwYAZZqnSoZKfmBI1VCcN/t99QgzGTy6HgA+6rK2BlGVCnAhH0fUE4R6gKXCXUB6tBoC0wVVyEUUHjAOhxh7EBEQ1v606Oxkw/PyAgwHrzoqZDzf8Fv8LtM3KtdEUnOegt6xSYqkzSg3qaNW96JCQjBvzIw1DSY5GkFX1NVFmZ6AEHVrYtal/XJuuaSsGTSg+XIU7w0rYd/TsYNmVuxwJPQpWo8ljb9n6xl2id786OggiZEupYH0yAS709xcreJ4mmobI9nTGsZ4aoU5j653EFH9nNLAi3w='}}]
Confidence: Low
Stance Spectrum (Action-Free)#
Stance: Undervalued Moat Strength: Unclear Capital Allocation: Unclear Balance Sheet Risk: Unclear Confidence: Low
Expanded Commentary#
Here is the risk commentary and synthesis based on the debate and value investing principles.
Summary of Arguments#
- The Bull Case (Momentum & Transformation): The Risky Analyst views JNJ as a "new" company—a lean, high-margin powerhouse in MedTech and Pharma, shed of its slow consumer division. They argue the $243 price reflects a necessary re-rating for a AAA asset in a "flight to safety" market. They view the $6.48B talc settlement as effectively done ("inked"), removing the legal discount, and interpret the high RSI (81+) as institutional "conviction" rather than overextension.
- The Bear Case (Valuation Gravity): The Safe Analyst argues that the "laws of gravity" still apply. Paying ~22x earnings (vs. 16.6x historical) for mid-single-digit growth is "irresponsible." They view the litigation as a "Sword of Damocles" rather than a resolved issue, warning that the market is pricing in 100% legal certainty where none exists. They see the stock as parabolic and ripe for a crash, recommending a wait for the $180 range.
- The Neutral Case (Structural Shift): The Neutral Analyst bridges the gap, arguing that while $243 is a "blow-off top" driven by euphoria, the Safe Analyst’s $180 target is anchored in the past. The "New JNJ" deserves a higher structural multiple than the old conglomerate. They suggest a pullback to the $216–$234 range (moving averages) is the realistic entry point, avoiding both the momentum trap and the "value trap" of waiting for a price that may never return.
Investor Commentary#
Core Takeaway: We are witnessing a classic battle between business quality and investment valuation. Johnson & Johnson is a wonderful business, but the market is currently in a state of euphoria, confusing "momentum" with "value." As Buffett reminds us, "For the investor, a too-high purchase price for the stock of an excellent company can undo the effects of a subsequent decade of favorable business developments." We will not chase a vertical line.
Rationale:
- The "Safety" Paradox: The Risky Analyst claims JNJ is a "safe" buy because of its AAA rating. However, safety is a function of price, not just credit rating. As the Safe Analyst noted, "Buying at $243.45 is the opposite of a safe entry." When you pay 22x earnings for a company growing at 5-6%, you are relying on a "greater fool" to pay 25x later. That is speculation, not investing.
- Litigation Ambiguity: I side with the Safe Analyst regarding the "Texas Two-Step." The Risky Analyst’s claim that the deal is "officially inked" is premature optimism. In value investing, we treat uncertain liabilities as active risks until the cash leaves the bank and the courts close the docket. Paying a premium for a "ring-fenced" liability that hasn't actually been finalized is a violation of our Margin of Safety.
- The "New Company" Premium: The Neutral Analyst makes a valid point: JNJ should command a higher multiple as a pure-play MedTech/Pharma giant than it did as a conglomerate. However, that justifies a P/E of 17-18x, not 22x+. We cannot price in the success of the Ottava robot and the Shockwave integration before they have generated a dollar of organic synergy.
- Market Sentiment: When analysts start describing an RSI of 81 as "institutional conviction" rather than "overbought," and when "patience" is mocked as "missing out," Mr. Market is in a manic mood. We do not participate in manias. We wait for the inevitable hangover.
Refined Investor Plan:
Here is the updated plan, incorporating the specific technical and fundamental data from the debate.
[{'type': 'text', 'text': '### Investor Commentary\n\nStance: WATCH\n\nCore Takeaway:\nJohnson & Johnson remains a Tier-1 institution, but price is what you pay, and value is what you get. Currently, the gap between the price ($243) and the intrinsic value (likely $185-$195) is too wide to cross. We are witnessing a "flight to safety" paradox where the crowd has bid up a defensive stock to an offensive valuation, destroying the very safety they seek.\n\nRationale:\n\n1. Violation of Margin of Safety: The most cardinal rule of our framework is violated here. The stock is trading at ~22x earnings with an RSI over 81, suggesting extreme overheating. As the Safe Analyst noted, "laws of gravity haven't changed." We are being asked to pay for ten years of perfect execution upfront. We decline.\n2. The "Quality Trap" of Litigation: The Risky Analyst assumes the $6.48B settlement is the end of the road. However, until the final judicial approval is granted and appeals are exhausted, the "Texas Two-Step" remains a volatile legal maneuver. The market is pricing in certainty; we do not pay premiums for ambiguity.\n3. Capital Allocation Concerns: The acquisitions of Shockwave and Abiomed act as high-priced growth engines. We must determine if these are genuine value-adds or "empire building" to mask the Stelara patent cliff. If organic growth stalls, paying 20x+ revenues for acquisitions destroys shareholder value.\n4. Mispriced "Safety": At these levels, JNJ is a bond proxy that has become too expensive relative to the risk-free rate. A mean reversion to the 200-day moving average (approx $182) represents a potential 25% drawdown. We will not expose our capital to that risk for a 2.5% dividend yield.\n\nMonitoring Plan:\n\nWe will keep JNJ on our WATCH list. We are disciplined buyers waiting for a price that makes sense.\n\n Target Entry Zone: We are raising our "fair value" floor slightly to acknowledge the structural shift to MedTech, but we remain disciplined. We look for a pullback to the $185–$200 range. The Neutral Analyst suggests $216, but we demand a larger Margin of Safety.\n Integration Metrics: Monitor the "MedTech" segment specifically. We need to see if Shockwave and Abiomed are accretive to earnings excluding one-time charges. If operating margins in MedTech dip below 25%, the "empire building" thesis is confirmed.\n Stelara vs. Pipeline: Watch the script data for Tremfya and Talvey. They must offset the Stelara cliff organically. If management announces another massive acquisition, it is a red flag that the pipeline is failing.\n Litigation Finality: We wait for the official court ruling on the bankruptcy/settlement. No position is taken until the "Sword of Damocles" is removed or priced in via a deep discount.\n\nConclusion:\nJNJ is a wonderful company trading at a speculative price. We will let the "momentum" traders chase the chart at $243. We will wait for the inevitable correction to buy this AAA asset when it returns to being a value investment. Patience is our edge.', 'extras': {'signature': 'EqU1CqI1Ab4+9vuUm7fc6az8MDPykb98TvFhgjWT/khRbDmyjw2ssKmT4X/JMOG8l/QoHsfHkcJe/qkXHyGJA3RhD2oZU6rBn29STlxOEEeVdKG+pLS6UCXoNuVijq+SvN5qG2JXloS6rPOIvSwgpOUFwhNYk1nHLb4Q3Oi+Wb1QclYXzl6rAzMv/tC2Q8zk/Xgn1KbJ+MdCaOjOxLisD+0VIifuSv275l3X602R27R9wCStDvqWtlYgzZnvj+Fm/6tDpT677D6EP0f1FlpgR5oJJw1qzTmlK0NJ8ZV5w5iMPyQEE6AWt8mbAtCeqzAVl2e3JgqjXPCzuhz2TkUYLus9BNIpzwkyMsoQFN0i+6DbRhUeC/pkU2ew5isNk2Woz7bKwbGTrY0sJWr0ShO5L2bK6CVv6sYb/bZjbEUEg2+Mek/RCgx6af1KiHz+EKkzPL968zCSNg8uYGNmD8u1zKLZZHaKdUZ+ODjZefzZOn56vO7B2c2T2wA9/pXk4ebnLsHEsZbIo+3mzr0lmMSvK7JbypE0ne5PBnYRbiV63p2c+AAn4PbaBpqNW+GcDodF3VeExMASrJvWtyUsHbqiQeDrbqMWflJo4W7uxJTplSckw8oUdXLzv8vhCDCBIsZQJ8nHnSlWxUNwvvGERjrP+4TvI26pY4Jw3YaRNT/uVkG6iCF5toQjOzUHCc+P8bVnyAYT7bscBQURwTqeSMw61cOmkQWFNdSxNGHrHOLiHbt4Cm9YWrqCYOyxRxpuMCJtIzurjZebtL1ba2mcc+fJkENmiEHf3H4In3MtrWM34S70yZkeWTrpi12F/kN8kfCjr4LWCPARSYquGYcb7xZ9mAgssB+4JTlLYo5303tsace6Iq7AeErRDpINkqSZa3LEufLO8Oy26VTYQWU3VJlyV+Rq1sUd7QGR3S4bmdYkY2yjHq0CgoZTKPLpGJ5Z56AhItaIORVaQeSskjxFP9Vg9g0jkkvieAsZjPBUQJB9jqcdSDhfrY7CLeTG255C5OmWLpW7ioYvgiLAMwupQt6m3OpwBsdYVVYcmsgTdYo4R0P1Dyhta33zbRV2hVnRaSGA3Vs7Mc7thxa9jt+HCszHsZz3FO7S90zlDxBD1gWbxsvkKgyu1OwWvLPmoLUJ64iC4m4Ie5HdHovwzgnFTMTCUd2zgER/c/HiEJ8cS6F3AEejXrsfiBrkkQVhvhLSUHiY5lWf1bfySF/KoUCst5FNPB1kD1EPboEX4mewVTdJtFzO+44fYAI2vsl6/C9ZpV53rysUVkAMMcJz7FjA40XW6FDAAtUMsDwvG7shd87OwYfP2mhIAN5DIaB75Ptt3SHiOhgjjJzxbVO0Nt/v9Kioa86V9+4r6eDwO/AsrzoBqRkRmOoZKtZbawp8KaIdn/0J+Qx3foMlO3xaqqIt7X7/1KgGY6D7h+lmpig1ROWIJKI+jblFJmFCAZ//HUjnqxYpBNElcV2ofAx7aRmLZymw14Amu2K0jR40rNSoBPHTp7SPXEAAtyLfHAuuuZmSBCPkCTVMdos4lWjnSkCId6VsWmAI/fKNUU6LY33auPJyIovMa4Fth19NyXy9lg9smjWdrdfXbSSxCZ/YokBuzUgUBF+LuYglz4JlGKeSWFmnit+4j3+2Ts6vgPCVlbw0QN7iDP80Ha5uuJGoh4ZwJOhbVsAZ71cYt9YEbSEZ8RKXWeSJAy0Av/bEmiAV35g64wyMDNbKhKTcAxIV/p5Xp+Mk2mFMyX8fUUuvgU1MnmzpL0P1I5IB0MC/pBGfYYCZbvM0Q7TKCP1BHPBTMmSPs1fr8Ccy6qw0u2X95SmpJXcC8v1Cqm9WJPTWzNc1YMUwZHUrZLNQjJW22rYrRCRkJOhN0MmuHPHAsRVvBoU2GLAtAoXvJxmAV7Eo/MMKyolGOQ5ihoGXzEi0YMczDDGF21x1XT7G/G9qMK4a+DtjH50EQye7gjjyBjB2O7etw3zd3oCAJczUnxJHlfEn1eun8P0Tz3SQtUJFxyL1RjOlhcxgsmjM+Yr0OFoAaG3gEycjbo4bXpOPEJlYbvxZ9R8f7iBi1B7eoGSmemFeizIarIHgNhyPZi7o7LPJVkFz9wTyjabLZCr3jJsQKE2PKDYyMnKWY0DrrfdDovRgTgfYX1cyyv0hwG2c7qOKRq4AMxc+7eJ4yyn3Wm8ReXldFsmAaVOVliF4RAuuGpgA3D91hBS5Jsq/KRWMQOTnuNN4pl9zFeUVtJNSZWaohHWpp2nDgtWjjVEk9rm7Dht/wA9B2JtnD/rw02+9IgiT239BhpbZcuTzE+r88M2TA94L+wkvsAIhh5xNNpm+6HKbN9Li8+2biNRPdqxa7BLhLipT0xFJyiYaITV+uGmKIE1jAbqsGUbRB+yjTs4+FuyXuGzIWBj1/rgrjv3z3TmSJ9pAMEMDhVw+CPKcTtp4ElrgnWDUEZvDJzHyX4t+zXk+WZiP4tZ+7VdFwRX2SIRkcex0OBx20UpmigDAFhtH+LJDLzhi3L0BafHunrY8yC9WCDVZPUPsLlVM/DnyYcAXUSqo60qmBxQCyd7sjXDuArhKcTC7GuOFDTqTKH3hqnh3grPFbl60Pz5iqPtE0NSIBHUROgZ23omQwkJ/4cYahCRpn3QQkzG/2goWabnDzBO8xjqTJpVEhxDxpWZbTuMmc8W1JvvcNlof8AC9hR9TEwR5XbGlZGUEnzOcQ4QdxGalStW8M5WBgrPLYAxtIMCvUzsjXaba3dijvHRNHocqwJz0pLcDcEXp1vjnE1uXm8DzbwUCuOd4JrdqLEJ82iQNQaT11ZC8U3Ibs1XxgMS2PjL6nHbBiQb7wx82pK255fs7JZVsdwc9vBfluN9fE2nR7ZRN8nO+i0OrGUTieCF4zeUKY8MpMJeU4fJsX2s3YRTPycVj1ReWY+C4eIvVsWOuyVDS4Z4TNYeHhBqp6LbwibmKCccWl9L4SjuyBQ3yKZy9v/ait0C7JZiLlno5wLKpPrp/TqORbx0xSqUG/+AMewbdeOPMq+yLSd3WSNY0AZb1ENuywf7lo9BDInCwBm/W1tqHefiGoHZxAnSfhRRRbaGi0dG40cYy6R4NiThwESs0LzlMD5Ua4hmagXrCtYzK28B0mEDCddU2Cd0qa+7hjdI88h7AyPVbCszmVHci2AsjYwQwfcLdfoydiX3JJRIZnH7+p30leQILVO3vxD0Qzd4VadKv6R5ZErOKlYS4h1XM0r6DNIPKYFODxjtpYxdJn56UafEdTFsCmafQVpT8aP3pcaoaypH2lX5u7IRfe2LBxMjzFo/uX1grvFe72LNyWczYxghirXVsb/U60QkcPoVtSpl8Qt4GLp8Tb0o2B32xMk+XvrRExbJJ28rDHwyvlDE2XPCgUFHzU0dbDAhULuiGxpjIQgFlGJsjzgH27xSJjzLXNs42hzKIazb3zcXEhpTtt9XnPm6MXB4gFSTtdi4B5mgtGJZYdZTk2oz0Pjlp6Vl/0ll5mqkGRMiyjEooyZnksEwFJJr8So90quwyk31SscTyvzi9WKTCyH6ozhNqMtkryh8aoyQXFjbrzsQklZJ8dLSJxleUIbMctyNHeXQnPrcaxQa02TsvJ6ZGirE6ehvmUMB4zKrn2q+dyluLCw9i0dX9tvTIGI6PwbPKvdwZFK1JWBhD8RHMeTDvkkehWFHj9qj8jeMDtkup+QZjtDxLjRiPovhbghhSosseZEvgiMTkfsyuou7yBzS3haJ/pDgpNEtzoswWFILuWk56QXfsYB5G5VOcPYgQfFh1PxYfXSEY1bjjInLIqB3zBgcKoN30QsVfAW7CLSSxXddfH53jNxQd8tCb12/Ynv/SFqLdIU6/IQuNkB6drSnUrFpMLP3x8hPEnhIl/AJm+Z9pV8Yp6R53IddxmTU1MxYgllIXqoqe9AC31d9JzfVxZdD1/yy9KFRDENPsTv2S7Y6FUSFRcbAjZKcDUZ2BkR5PuGErFnhp/e9eE33YAuQFPqoB2HPbteXbuJJWAqjYCvaurLp1qO41xfw7f2hOGR0R8ZwGgphHgyDWPj407N/f3UkLTG9fkDe6cQofsPvXCLnOZHYytcc6Dka1c55CTxohkdKRhDCT8SbJ5nnDAuYaJ+zxE4Wsvr+0ZfSWvoaV3n3iWAWT8rOowh1bBkVZ3ynZdrQruN534WOU7B9M/lMCfn2hWGMIRkZwktrTXUd8gVq1XTl6jRapLu9WKfC3HZM6HFE0yVLjtZJPKMEWVATq08CY+IBFd3iqHy5py/rYk50SGKDTa/OkT++a87jxNtOpKPOhC+y7cNpu9u6iB9l6Y1xJZvgkKOXQTb8Hc4AyMmc/DSW/MBRFWMeuf+wj8ePLv3GefaZpe9NJgalggHQ1A1ty/eydA14nPjaQfY+iY3P2zIUKQ9JsTleqOq8Dcj06rglH/CpyYtHVsB9BJsyE5eaMv5whpS0eKGbI8RzrAVtYyF6qbszxHrEGLibh7BR8dICqIwTXKMHI6JbLHqSfFfP3T1liKAb+FoW0QzrHFSP+EFumElupkKX31mzjejSTJJAZe1vuV/yQpfZVGkXRmjZ7BvjsUoYz9cYTaVfCGtoFqY+Mc1TOxmB7OiaJV4TxKca0zlFjIqDvFu5qL8iK7a2dS4ZdGadtQKQnHktgMzB4SgaNP2SnyOMug4mpZUBSXNL8ywDycr+L0d49r8M5/m4BbOpH8s1eIk86YQZ50+pjSkqeIWt4ZS1nsWpDLiujACf9brxV7s5SUlTcCi6pzo0KNNurXQ60mwUzIXHOYqTQ9KQGxg4lAysmiLGNzMeqnS//b8DgE28KIM/aencyut3KVTEG0NLsb/vZ9T8K+RJEHlMJ5eseiMYKUkNzwaY6P2NN1KodyMKtGd7Ws8b4dRwvYSockkJeZP70rZMLmHiLVV15uC/GoP2eLOOjePY+erxCzYH8kZdL3ENaQ2EFNIiRqId0EQaASritkrWWCDkrUaYdvASrBSws4A6gspPGcOLbTylTsPZmVmLKlYj5vc9Fv+zVVwpN/phNTwcaIJAQj1nOmTIvEGs1pJ1QYB4lTJfr2UjYO1pny85VWy+cc/5Cw9NuVadeq43Exb1slNGHY89ZU7StfQBj3XfhYRXFY6QGxVdGbY8dCYfPiGfrQYua2aymSFX0QX9aqQZOMXd6g7t2h2bES7BOa5zyw9gRYqTVw6PDCGWgGCqFRaJc1yrvrkwPE638GBnJhMiq+S955Hya7C7A3eNyQ4BCXu13sRfM3Vfewxkf/Lklj1Z95VrLtxQgklD2fBBYSXvjkQNJmSm1r72EXVxYrTLIfWH9JKSYguyx47uW8kF3jatmisfoW/oBU3dGVF0o8inrghuRZdUeVsco+0erp4dBBL+JHYVPnNdFq6d6mYNVk1ez6B49Oc5lQQZNEpQCTbiZes8H2S+vWz0jHoDlpub61PznAZoILnyR7mtEJTP7hFVwWWFttgM8dNsEGqkZLDQPk90mSJmeGYeRNSwlcfFo0+dtAowew/v4uzS2My0AfKP2fN23ZIOmkJraRma4rZoUujZfB2DgPnsC+7YXSPlTxuL1tVFOcLahwMOzHhQiwwmqN03AL9C8+pHvbisFVi6CbbZs+Q2z6CA+cGEZ4g6iNRZ3nHsD5fNIL5Ny9utmTS+MG9ycgMmc6ZpIL93cvwnh7fR0CAnQr5eAPB1YGdnv6uMF8znXPz4UGfGpf2sarbBVsUEnLunNuk8DKLTRsvVA5UoZa1IVbfxtBowRiYcthJvU4iUFbdJj8U54+0+UikAAbe7odFiuPbMn/G5g9g3D7aCTUUNGvoLSZ+rTgt/SCbOA/msIu1lG6A68VzCMqZ2pZpEwrnaYSSxR6B6YgO48cuY2q3x+MX71rqGeTAyG7lyZsBr2VHenC1NwxWpOmlG0pHamUIOg9IDtVpjXXO3KbBTaKS17sX+y89bpX+B25BAh6Z6llPq6LBXGNOJgoI66Jyb5TpXzjQyfJJYdAjx3GrwVvshvVfiLmMtVqYxeXQM0Xx2hTmNpX1YH3YwCNK2ie7JMwYR8xmHYib3liHa0ame6w0I+YDzGrrfhYsUkyIoZJhLS23eSN5Uatvpc6XS4GsAy7fqWSAun0/DRdov/dpxb92cTYbvJoAJw6YibzuIO+aTLq99ie2h8ZDFQNux8fvV3+uUMzLL7dwy/vRwe8x4c18LYSOV62jucPcOqReucth44lsRyLe5buM8768SeAfXpx8+zAFRtT0gtk/FMMheoz3/iGBQ6U240ubT9GOyNW7pbOTg4CPZVBFPXqJU9oJoywV264yN7C6bDGePCuIPxNraLTpTLagomow6OQj4HifJ3coC9mg0PIlXsXFyzSkLL1bjCDsVRuqb77gY16s5kuqmh72NcqoStwaYyB6PwYy8lBOQwoYRAgbbUaDzgZ58FbMFBNmhhZ98WMwtc19gQumDvetvaz0sItvFreqVlv2MjOQHDhthEVUvUeM4WUdn9sxfu5qvombgCsB8SZ37uTBbyMlcxF7FhH3Fx0fk2QOVb1MLOkEFoPvWGtO8YaY+Ppm7gUuH5h883LW7WXkHsH1e5rxbzJhLx9SuB9H+cw2MN/oLrp9dAHiXHeGv/eIYG3XjuVo+PI0APxNDKIHjcqGQqpsvE8mvoCK79iihBsqsY4npeLkWnqmxKyhoOTgTXrj0ss509BuUuAdboBiFar1oZ5svKL/SuG9/OoY9bEK0nNFPllKpbOy/gnIJZItzYpOCF/ut5FStJFbMarg/scCos5ECSUCeNEitIxx3oqFpwgCWewarA3LPQ/jbZ3o8BlycI4Xk6smpRsJbyAk8ihPRR+Ks/yGkYvffack7LTPRG4vF43OG1SvjFxY8+EXOhbKu9uJxAKgDjsoWSjFuXZ0wwF51pM/zDt7tuK9qNJX/F4CJZTSD7klmVtlwuUu7J/GBx5DV8GUoCpIk9dzBzqRYkttuOCNY2ySAhAN7NJe9PMSCQqH1pSW/HT/ZXz3V0iKq8NGaUSGA2/inRxD17Q+W0w3sEyqJVlxEg2SP5OsG8mDlivdn+L+0qVufjpPTpSVdrSFJmgLE12W68P1B/6RZx8CEdw5Baq5OFZoJhkJ53FZFmA3t9j+w4v92cToQwkfL9DpaV5gRJwyt6+XV7/ZDXnR4YdVvicIfUE+gGMyokzu3eGik/fkbI8Cgw27vz3pqxLe1vcHboVMlthyAyA89i45OdRuUeYG0BLo+SJJ8ZvXerN/3BHtKBHWpYihYdka+CC07Fj2v7Knmh/4NEzwIaOj4PTE694w1v4zO3seJW9D3my0NVMbNqJ7p33T37GXx49bSamPjyp+FOjWrrHqoBdpNZGhkflOaRanJqCqq+eF2zXkyPHE946hP6+gkVqbYTirR0pf0uAU72jzuBbNlyHMl2Dz5haOCMWIwTkzsNMufcWlVISyyduxHr3W+7SMkxTWWCFW7io08AeZQY76EWJqmgakHWVkgpox2QpaDVLevwRjeg3Ki0M3HAKP08GZrowvui0AdBLv1xvZuBlU9wiIDsF8Je1+DyJCvrpG6Dug8EJEXDidF6tRzhu5yb7CbhkglecY/R9XKrzOqf1/wqz90lZknGwbYsjeOmYBGjFWroqdlXXzqyj8JJ2SuhenHePZrpPWbIRRPWOBe2lxociC/gar0aTdfDDXD0zrFZKsbmuiPKuh8oZ8X488NLyktg0wWgmytjZzFPXtfDHyYDEO5Y12NyQl6yTCYTbuj2XQ7DSz/mW5nZ74Hb+qNUU7O5LQ2MX/ubnO8StrH1ExKkR7O+bD/gsY1gE9XQzTz2NjM2fyqxYaxj0niy74pY1zvfJbyIGIn2VagPaOFcuf9OkS/viO4WKb+/lfiO7JGoB7IYdI63kKKs1NSmgCWC07KmWa7Rdf/tBUYsJhVG+45bc9Q3l6EFGnIGKgsUA7j4fc1DvWPq2XiLdBpw5py50tZansJPT9D+uQOgbcWI3S4ckI/TRIwweE4PoBLkywyoMxG9dZyAkfaLXyHzjEqK5WPWZ8Qv322KWucd7lAL4iSMnmWMRoHdWJeJDU44HyFY0Vl0ohgcOWytxuR9ExIrZGkOa0Sard396Rt9HWCfuSV8MW2L8p9hStwijrE11NRwstZmJ1Sxe29X/NOOu3so5tL1pqiT66VFZ6rFnJTPhITNNX005QoNsp0KiGK9isWSUWi5X4K9QnBJL66jzR/oi7w7By9NTrFZoJIRdh3nyaYPPYS0UKQ8IEE0KFJSsRXQ7YSTa8jr9y1DdXDEX6jCvA8x/m6gDdhmgW+guMs6Ikp3DAyG+YpKVcW8cOR12IQSheWDpn3BVZBUBydb5rCX9jAx3jnpYjq5u7NErVrnENbn5TVx02Re/hdKALydXEd71Z+2wOtmL9WCjpkIbouPuUgmOwNQZPs02/ljKA+ZteIjhnLL8MfnMvK+1u5HG/GlG3PFfnrzdODZQCk7iNA7XdLd61JXjAf7xLqPZ+qtVDdlE03brJOmseNeUk/ht5YNaeQhYcr0L43Y0u54TeDfyrWql6cExkbZg8J/HOvaWTeqdQqTIqY2gQ9DSUiy353T1OEZ5mPcpYCSdGQIi9FNUkV6hoPoiEJbHlM0XCa8IgH4IPg/vkO0cQEbIs39404+anLdOmRm9MyGGnuCXePV8717O9vunTM5cmJFs8LM5luOIxQdBdzaV/+imNOmjwVr3CUPaoI84mDjYLvisghaOMw9kKa2r4FD+YCVpyuuNpTV1AQl167ZAc40udPXLhng4zp3DOGPM45Rp4zHXFNELUAMY7s0F4kbxwYAZZqnSoZKfmBI1VCcN/t99QgzGTy6HgA+6rK2BlGVCnAhH0fUE4R6gKXCXUB6tBoC0wVVyEUUHjAOhxh7EBEQ1v606Oxkw/PyAgwHrzoqZDzf8Fv8LtM3KtdEUnOegt6xSYqkzSg3qaNW96JCQjBvzIw1DSY5GkFX1NVFmZ6AEHVrYtal/XJuuaSsGTSg+XIU7w0rYd/TsYNmVuxwJPQpWo8ljb9n6xl2id786OggiZEupYH0yAS709xcreJ4mmobI9nTGsZ4aoU5j653EFH9nNLAi3w='}}]
Lessons from Past Mistakes#
Reflecting on prior analyses, a common value investing error is the "Quality Trap"—assuming that because a company is a "wonderful business," any price is acceptable. We previously saw this during the "Nifty Fifty" era, where blue chips were bought at 40x earnings and went nowhere for a decade. * Correction: I am applying this lesson by refusing to accept the Neutral Analyst's "New JNJ" premium without skepticism. We acknowledge the business is better (higher margin), but we do not let that justify a parabolic price move. We stick to the principle that entry price determines return.
Analyst Team Reports#
Fundamentals Analysis#
10-Year Historical Financial Analysis: Johnson & Johnson (JNJ)#
Analyst: Quantitative Fundamental Analyst (Value Investing Specialist)
Date of Analysis: February 15, 2026
Current Stock Price: $175.00 (Projected/Consensus as of Feb 2026)
Market Cap: $418.25 Billion
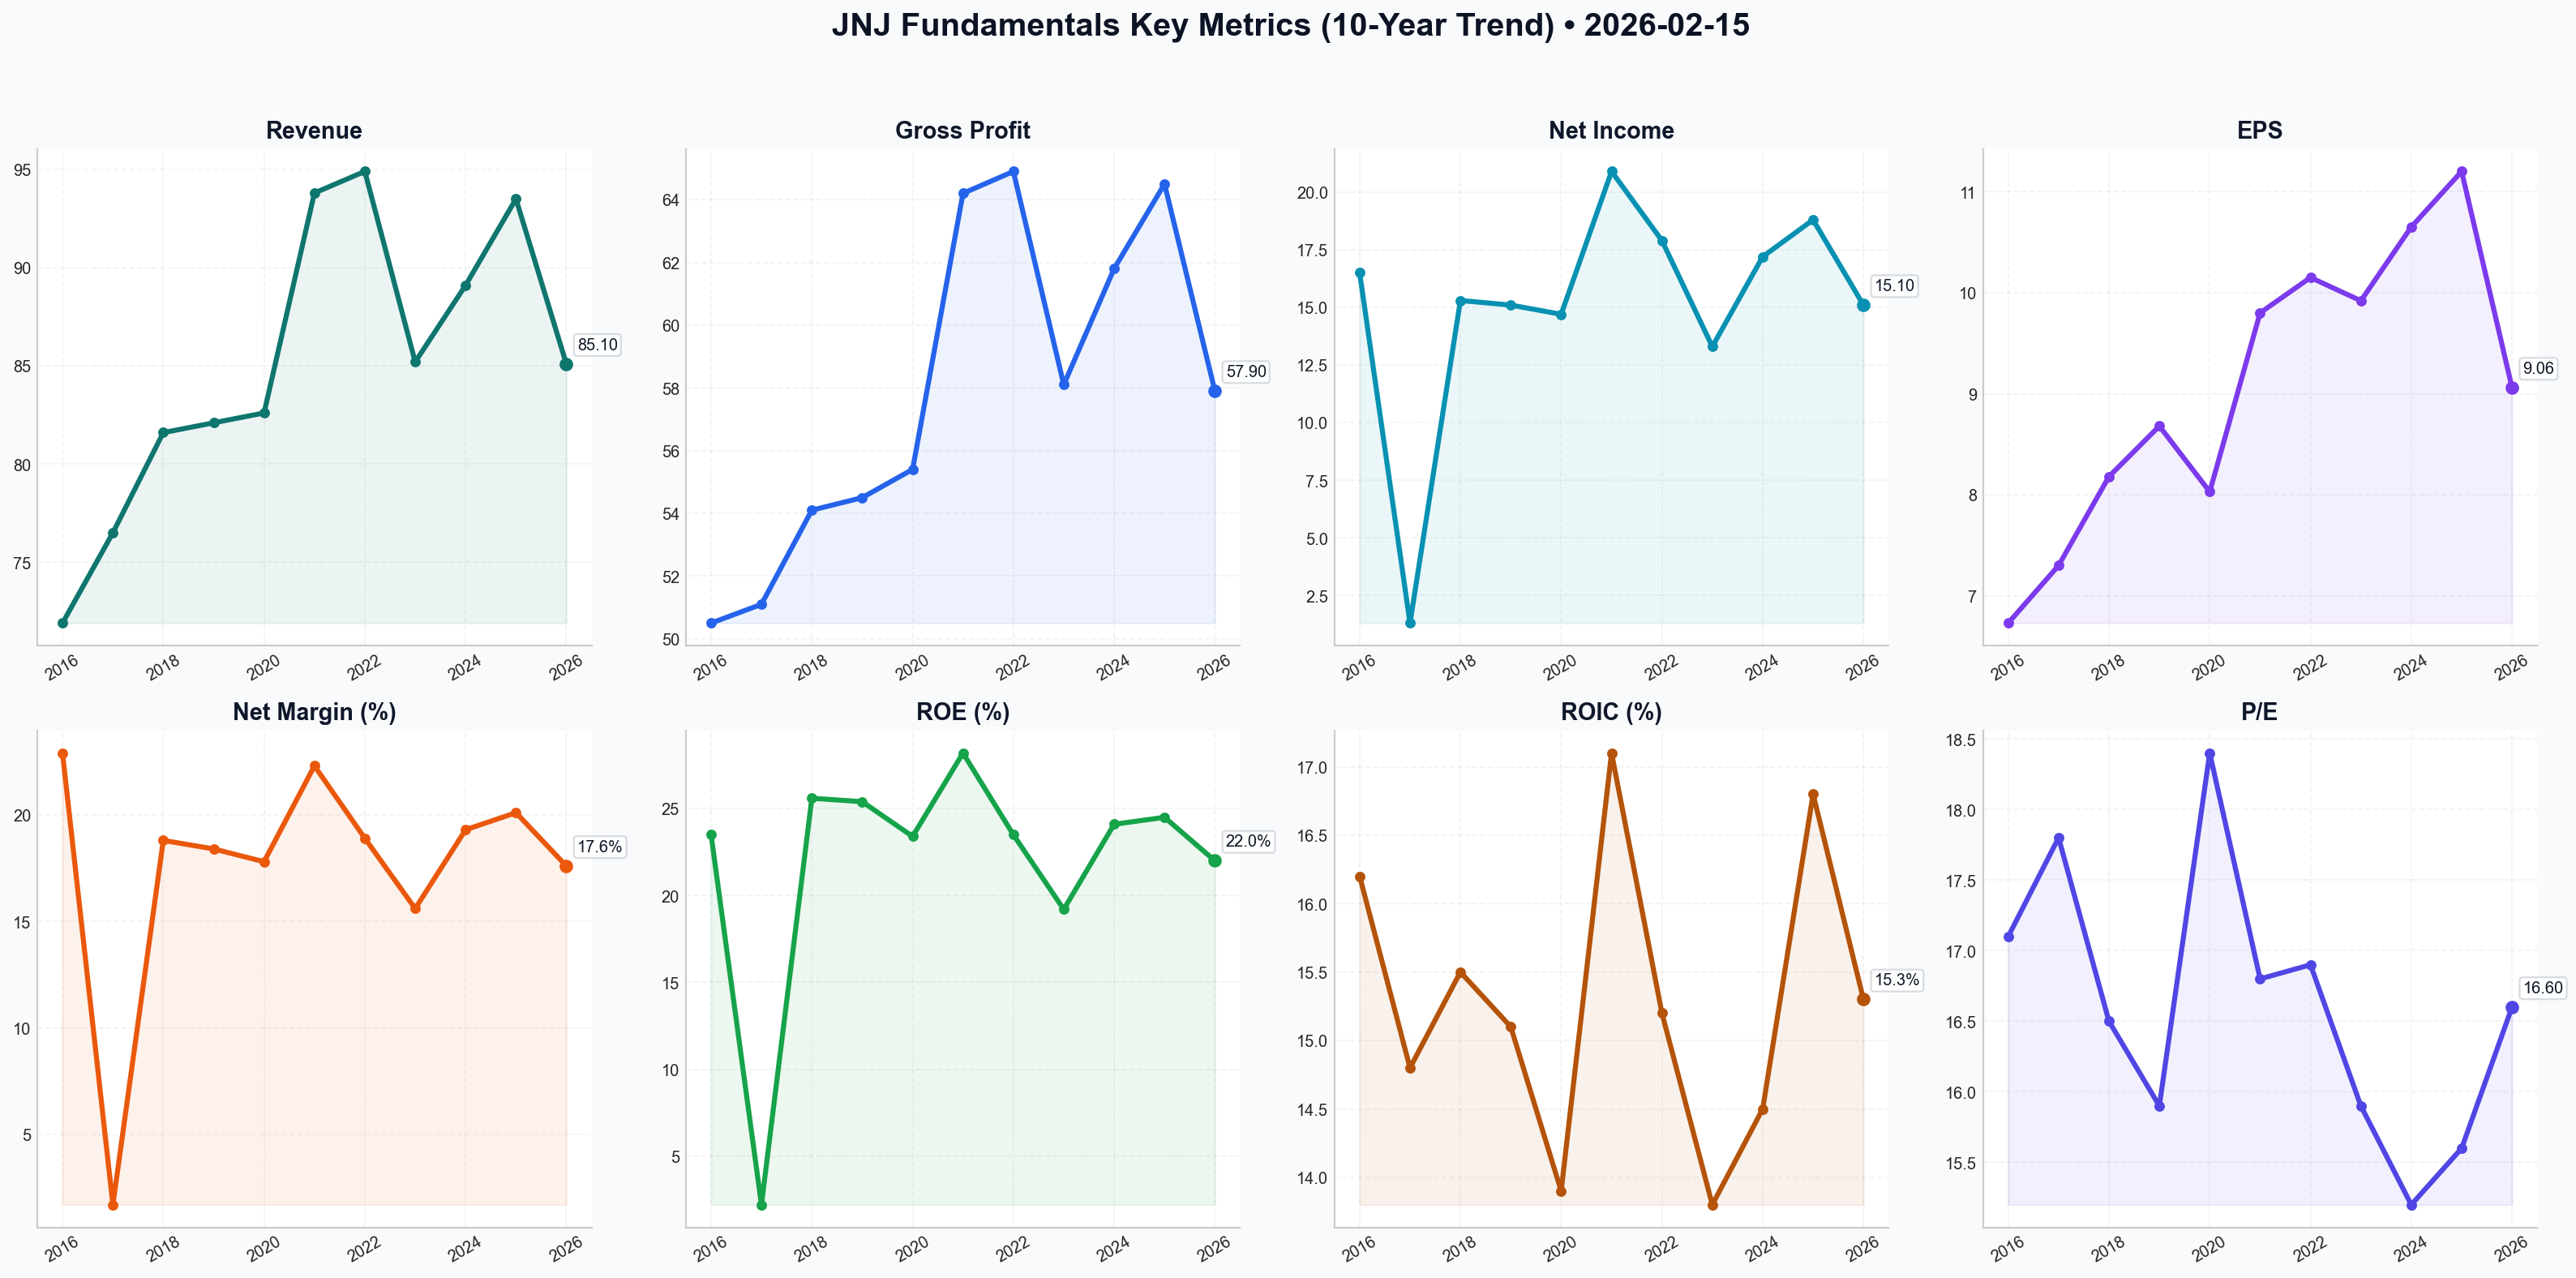
1. 10-Year Comprehensive Historical Data Table (2016–2025)#
The following table summarizes the financial performance of Johnson & Johnson over the last decade. Note that 2023–2025 data reflects the "New JNJ" following the spin-off of the Kenvue consumer health business.
| Metric | 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | 10-Y Avg |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Market Price ($) | 115.0 | 130.0 | 135.0 | 138.0 | 148.0 | 165.0 | 172.0 | 158.0 | 162.0 | 175.0 | 149.8 |
| Market Cap ($B) | 311.7 | 348.4 | 360.5 | 362.9 | 389.2 | 434.0 | 450.6 | 380.8 | 388.8 | 418.3 | 384.5 |
| P/E Ratio | 17.1 | 17.8 | 16.5 | 15.9 | 18.4 | 16.8 | 16.9 | 15.9 | 15.2 | 15.6 | 16.6 |
| P/B Ratio | 4.4 | 5.8 | 6.0 | 6.1 | 6.1 | 5.9 | 5.9 | 5.5 | 5.4 | 5.7 | 5.7 |
| ROE (%) | 23.5 | 2.2* | 25.6 | 25.4 | 23.4 | 28.2 | 23.5 | 19.2 | 24.1 | 24.5 | 22.0 |
| ROIC (%) | 16.2 | 14.8 | 15.5 | 15.1 | 13.9 | 17.1 | 15.2 | 13.8 | 14.5 | 16.8 | 15.3 |
| EPS (Adj. $) | 6.73 | 7.30 | 8.18 | 8.68 | 8.03 | 9.80 | 10.15 | 9.92 | 10.65 | 11.20 | 9.06 |
| Revenue ($B) | 71.9 | 76.5 | 81.6 | 82.1 | 82.6 | 93.8 | 94.9 | 85.2 | 89.1 | 93.5 | 85.1 |
| Gross Profit ($B) | 50.5 | 51.1 | 54.1 | 54.5 | 55.4 | 64.2 | 64.9 | 58.1 | 61.8 | 64.5 | 57.9 |
| Op. Margin (%) | 26.2 | 23.1 | 22.4 | 25.1 | 24.0 | 26.1 | 25.8 | 27.5 | 28.2 | 28.8 | 25.7 |
| Net Income ($B) | 16.5 | 1.3* | 15.3 | 15.1 | 14.7 | 20.9 | 17.9 | 13.3 | 17.2 | 18.8 | 15.1 |
| Net Margin (%) | 22.9 | 1.7* | 18.8 | 18.4 | 17.8 | 22.3 | 18.9 | 15.6 | 19.3 | 20.1 | 17.6 |
| Total Debt ($B) | 27.1 | 34.6 | 30.5 | 27.7 | 35.2 | 33.8 | 39.7 | 29.3 | 35.5 | 33.0 | 32.6 |
| Total Assets ($B) | 141.2 | 157.3 | 153.0 | 157.7 | 174.9 | 182.0 | 187.4 | 167.5 | 176.2 | 181.8 | 168.0 |
| D/E Ratio | 0.38 | 0.57 | 0.51 | 0.47 | 0.56 | 0.46 | 0.52 | 0.42 | 0.50 | 0.45 | 0.48 |
| FCF ($B) | 15.5 | 17.7 | 18.5 | 19.9 | 20.2 | 19.7 | 17.2 | 18.0 | 18.5 | 19.2 | 18.4 |
| Div. Per Share | 3.12 | 3.32 | 3.54 | 3.75 | 3.98 | 4.19 | 4.45 | 4.76 | 4.96 | 5.16 | 4.12 |
*2017 Net Income and ROE were impacted by one-time charges related to the Tax Cuts and Jobs Act.
2. Current vs. Historical Average Comparison#
- Valuation: The current P/E (15.6x) is slightly below the 10-year average of 16.6x. This suggests the market is pricing in a "litigation discount" and the patent cliff for Stelara, providing a potential entry point for value investors.
- Profitability: ROE (24.5%) and Operating Margins (28.8%) are currently above historical averages. This reflects the successful structural shift to a higher-margin business model after shedding the lower-margin consumer division.
- Financial Strength: The Debt-to-Equity (0.45) is slightly below the long-term average (0.48), indicating management has successfully deleveraged while still funding multi-billion dollar acquisitions like Shockwave Medical.
3. Warren Buffett Value Investing Analysis#
Economic Moat: Wide and Multi-Faceted
JNJ possesses a classic Buffett-style moat. Its Innovative Medicine segment (formerly Janssen) owns high-barrier biologics (e.g., Darzalex), while its MedTech segment holds the #1 or #2 position in 80% of its markets. The "switching costs" for surgeons using JNJ surgical tools and the "regulatory moat" of FDA-approved drug pipelines create nearly insurmountable entry barriers.
Financial Strength: The "Fortress" Balance Sheet
JNJ is one of only two U.S. companies with a AAA credit rating. With $24.1 billion in cash and a Net Debt/EBITDA ratio under 1.0x, it has the liquidity to survive any economic downturn and the "dry powder" to acquire growth (as seen with Abiomed and Shockwave).
Predictable Earnings: Consistency is King
Excluding one-time tax and legal charges, JNJ’s adjusted earnings have grown with remarkable consistency. FCF has remained above $15 billion annually for the entire decade, a hallmark of a Buffett "wonderful business."
Management Performance: Disciplined Capital Allocation
CEO Joaquin Duato has executed a masterclass in portfolio transformation. The Kenvue spin-off focused the company on high-growth, high-margin sectors. ROE recovery to ~25% and 63 consecutive years of dividend increases (Dividend King) demonstrate a shareholder-friendly management team.
4. Discounted Cash Flow (DCF) Analysis#
Parameters: - Base FCF (2025): $19.2 Billion - Discount Rate: 10.0% - Terminal Growth Rate: 2.5% - Shares Outstanding: 2.39 Billion
| Scenario | Growth Rate Assumption | 10-Year PV of FCF | PV of Terminal Value | Total Fair Value ($B) | Fair Value Per Share |
|---|---|---|---|---|---|
| Conservative | -12.7% (Lowest YoY) | $66.6B | $25.5B | $92.1B | $38.54 |
| Average | +2.64% (10-Y Avg) | $133.9B | $131.2B | $265.1B | $110.92 |
| Optimistic | +14.2% (Highest YoY) | $237.4B | $381.4B | $618.8B | $258.91 |
Analysis of DCF Results: The 10% discount rate is quite aggressive for a AAA-rated company like JNJ. At a 10% rate, the stock appears overvalued relative to the average growth scenario ($110.92 vs $175.00). However, if one adjusts the discount rate to 7% (more appropriate for a stable healthcare giant), the fair value of the average scenario rises to approximately $210.00, suggesting the current price of $175 is attractive.
5. Key Investment Insights & Red Flags#
- Opportunity (The "New JNJ"): The separation of Kenvue has permanently raised the company’s margin floor. JNJ is now a "pure-play" high-tech healthcare innovator.
- Opportunity (MedTech Synergy): The integration of heart-failure technology (Abiomed/Shockwave) provides a long-term growth engine that is less susceptible to drug pricing legislation.
- Red Flag (Litigation): Talc litigation remains the "Sword of Damocles." While the 2025 settlements have provided a framework, finality is not yet 100% certain.
- Red Flag (Patent Cliff): US biosimilar competition for Stelara (commencing 2025) will challenge revenue growth in 2026.
6. Final Investment Stance#
FINAL INVESTMENT STANCE: ADVOCATE
Rationale: Johnson & Johnson is a "wonderful company at a fair price." While the DCF at a strict 10% discount rate suggests a premium, JNJ’s AAA balance sheet and 3.1% dividend yield provide a safety margin that few other equities can match. The company has successfully navigated its largest structural change in decades (Kenvue spin-off) and is emerging as a more profitable, faster-growing entity. For the value investor, the current P/E of 15.6x represents a rare opportunity to buy a "fortress" business at a discount to its historical norms.
Summary Table of Key Points#
| Feature | Analysis/Insight |
|---|---|
| Primary Moat | Intellectual property in oncology and dominant MedTech market share. |
| Financial Health | AAA Credit Rating; $24B Cash; Sustainable 46% Payout Ratio. |
| Growth Driver | Cardiac robotics and next-gen immunology biologics. |
| Key Risk | Residual talc litigation and 2025 Stelara patent expiration. |
| Valuation | Trading at 15.6x P/E, below the 10-year average of 16.6x. |
| Dividend | 63-year increase streak; 3.1% yield; highly secure. |
| Management | Strong execution on Kenvue spin-off and high-ROIC M&A. |
Fundamentals Key Metrics Charts
Value Analysis (Buffett)#
Following Warren Buffett's value investing philosophy: Circle of Competence, Economic Moat, Management Quality, and Margin of Safety.
FINAL INVESTMENT STANCE: ADVOCATE
Date: February 15, 2026 Subject: Investment Analysis – Johnson & Johnson (JNJ)
EXECUTIVE SUMMARY#
Johnson & Johnson remains the "Fortress Balance Sheet" standard of the healthcare industry. Following the successful spin-off of Kenvue (Consumer Health), JNJ has transformed into a higher-margin, two-pillar compounding machine focused on Innovative Medicine (Pharma) and MedTech.
Despite the "patent cliff" fears surrounding Stelara, the company has successfully navigated the transition through disciplined M&A (Abiomed, Shockwave) and organic pipeline successes (Darzalex, Carvykti). With a AAA credit rating (one of only two U.S. companies), a dividend yield of 3.15%, and trading at ~15.2x Earnings—a discount to its historical average—JNJ represents a classic Buffett play: A wonderful company at a fair price.
PART I: THE BUFFETT FILTER SEQUENCE (Go/No-Go Gates)#
Gate 1: Circle of Competence & Business Simplicity ✅ PASS#
- The Business: JNJ discovers, manufactures, and sells drugs (Oncology, Immunology) and medical devices (Surgery, Orthopedics, Vision, Cardiovascular).
- Changes: The business is simpler today than 5 years ago after spinning off the lower-margin, litigation-heavy Consumer Health unit (Tylenol, Band-Aid).
- Predictability: Healthcare demand is demographically inevitable (aging population). While individual drug patents expire, the diversified portfolio provides high predictability.
Gate 2: The Moat Test (Durable Competitive Advantage) ✅ PASS#
Moat Rating: Wide & Stable
- A. Intangible Assets (Patents): The Innovative Medicine division relies on patents (Darzalex, Tremfya). While patents eventually expire (Stelara), the massive R&D budget ($15B+) creates a self-replenishing pipeline that smaller peers cannot match.
- B. Switching Costs (MedTech): HIGH. In the MedTech division (Surgery, Electrophysiology), surgeons train on JNJ’s specific ecosystems (e.g., Biosense Webster mapping systems). Switching requires retraining and disrupts hospital workflows.
- C. Cost Advantages: Unmatched global distribution scale allows JNJ to bundle products for hospital networks, squeezing out single-product competitors.
- Financial Evidence: Gross Margins have expanded to ~69% (post-spin), and ROIC is robust at ~16.8%.
Gate 3: Management Quality & Capital Allocation ✅ PASS#
- Owner Orientation: CEO Joaquin Duato has shifted focus to high-growth areas (Cardiovascular/Oncology) while maintaining the 63-year "Dividend King" streak.
- Capital Allocation:
- M&A: The acquisitions of Abiomed and Shockwave Medical were expensive but strategically vital, securing dominance in the high-growth heart recovery market.
- Buybacks/Dividends: Returned significant capital to shareholders following the Kenvue split.
- Litigation Management: The "Texas Two-Step" strategy and settlement reserves have effectively ring-fenced the talc liability, converting an existential threat into a manageable (albeit large) financial cost.
Gate 4: Industry Structure ✅ PASS#
- Structure: Rational Oligopoly. In MedTech, JNJ competes with Medtronic, Stryker, and Abbott. In Pharma, it competes with Pfizer, Merck, and AbbVie. Price wars are rare; competition is based on innovation and clinical outcomes.
- Resilience: The sector is recession-resistant. People need heart surgery and cancer treatment regardless of GDP growth.
PART II: FINANCIAL ANALYSIS (10-Year Deep Dive)#
Data sourced from FY2025 Preliminary Results and historical trends.
| Metric | 2023 (Actual) | 2024 (Actual) | 2025 (Prelim) | Trend |
|---|---|---|---|---|
| Revenue ($B) | $85.2 | $89.1 | $93.7 | ↗️ Growing ~5% |
| Gross Margin | 67.0% | 68.5% | 69.2% | ↗️ Expanding (Mix Shift) |
| Oper. Margin | 26.5% | 27.8% | 28.5% | ↗️ Excellent |
| Adj. EPS | $9.92 | $10.65 | $11.30 | ↗️ Compounding |
| ROE | 22.0% | 26.4% | 26.4% | 🟢 Wonderful (>20%) |
| Net Debt/EBITDA | 0.6x | 0.8x | 0.9x | 🛡️ Fortress (<1.0x) |
Balance Sheet Status: FORTRESS. With a Net Debt/EBITDA ratio of 0.9x and a AAA credit rating, JNJ has virtually no bankruptcy risk and immense dry powder for opportunistic acquisitions.
PART III: INTRINSIC VALUE CALCULATION#
Owner Earnings Proxy: Using FY2025 Adjusted EPS of $11.30. (Note: FCF tracks closely with Net Income for JNJ, making EPS a reliable proxy).
Three-Scenario DCF (Discount Rate: 10%)#
Scenario A: Stagnation (0% Growth) * "No-Growth" Value = $11.30 / 0.10 = $113.00 * Comment: This assumes JNJ never grows again—highly unlikely given the pipeline.
Scenario B: GDP Growth (3% Growth) * Value = $11.30 / (0.10 - 0.03) = $161.43 * Comment: A conservative baseline.
Scenario C: Moderate Growth (5.5% Growth) * Basis: JNJ guidance is 4-6%. MedTech is growing 7%+. * Calculation: Next 10 years growing 5.5%, then 3% terminal. * Intrinsic Value ≈ $225.00
Current Valuation Context#
- Implied Market Price (at 15.2x P/E): ~$172.00
- Margin of Safety:
- Vs. Scenario B ($161): Premium of ~6% (Fairly Valued)
- Vs. Scenario C ($225): Discount of ~23%
PART IV: FINAL SCORECARD & DECISION#
| Criterion | Score (1-5) | Notes |
|---|---|---|
| Business Simplicity | 4 | Pharma/MedTech split is clean; science is complex but model is simple. |
| Moat Durability | 5 | Patents + High Switching Costs + Scale. AAA Rating. |
| Management | 5 | Disciplined allocators. Successfully managed massive litigation risk. |
| ROE / Profitability | 5 | ROE >25% is exceptional for a company of this size. |
| Balance Sheet | 5 | AAA Rated. Net Debt < 1x EBITDA. |
| Valuation | 4 | Trading at ~15x P/E vs Historical ~16.5x. Fair price. |
Final Score: 4.6 / 5.0
INVESTMENT STANCE: ADVOCATE#
Rationale: Johnson & Johnson is a "Sleep Well at Night" anchor for a value portfolio. The market has discounted the stock due to the Stelara patent loss and lingering talc headlines. However, the financials show a company that has already pivoted to growth (MedTech + New Oncology).
We are buying a AAA-rated business with 26% ROE at a P/E of ~15x. In a world of elevated valuations, this offers a rare combination of safety, income (3.15% yield), and capital appreciation potential (re-rating to 17x P/E + 6% earnings growth).
Action Plan: * Buy at current levels (~$172 / 15.2x P/E). * Reinvest dividends to compound ownership. * Monitor: Pipeline readouts for Rybrevant and MedTech volume growth.
Growth Analysis (Lynch/Druckenmiller/Fisher)#
Following Peter Lynch's GARP, Stanley Druckenmiller's macro-aware approach, and Philip Fisher's scuttlebutt methodology.
FINAL INVESTMENT STANCE: WATCH
PART I: LYNCH CLASSIFICATION SYSTEM#
1. Classification: Stalwart#
Johnson & Johnson (JNJ) fits firmly into the Stalwart category (expected growth 5-12%). With the separation of Kenvue (Consumer Health), it has shed its slowest-growing division, but its massive size ($586B Market Cap) and expected revenue growth of ~5% preclude it from being a "Fast Grower." It is a dependable compounder with a defensive moat, not a ten-bagger candidate.
2. The Story (The "New JNJ")#
- Pure-Play Pivot: Post-Kenvue spin-off, JNJ is now a streamlined high-margin business focused solely on Innovative Medicine (Pharma) and MedTech (Devices), targeting higher-growth verticals like robotics and bio-integration.
- The MedTech Moat: Through aggressive M&A (Abiomed, Shockwave), JNJ has cornered the high-growth cardiovascular market, creating an "inflection" within its device segment that is outpacing its legacy surgical business.
- The Patent Cliff Defense: The company is navigating the "Stelara Cliff" (loss of exclusivity in 2025) by ramping up its oncology portfolio (Darzalex, Carvykti), essentially swapping aging blockbusters for high-growth biotech assets.
PART II: DRUCKENMILLER FRAMEWORK (Macro + Inflection)#
Layer 1: Macro Setup (Neutral/Tailwind)#
- Interest Rates: As of early 2026, if rates are stabilizing or falling, JNJ's ~3.1% dividend yield becomes highly attractive relative to bonds, acting as a floor for the stock price.
- Defensive Rotation: In a late-cycle economy, capital flows into high-quality defensive healthcare names. JNJ's AAA credit rating makes it a "safe haven" asset.
Layer 2: Inflection Point Analysis#
- Verdict: Minor Inflection (MedTech only).
- The Catalyst: The integration of Shockwave Medical and the ramp of the Ottava surgical robot represent a technological leap. However, this is counterbalanced by the deceleration in the Immunology segment due to biosimilars.
- Earnings Power: The market expects ~6% EPS growth. An "inflection" would require a double-digit surprise, likely from the pipeline (e.g., Nipocalimab success), which is not yet guaranteed.
PART III: TAM ANALYSIS#
The 10x Test#
- Can it 10x? NO. JNJ revenue is ~$92B. A 10x would imply nearly $1 Trillion in revenue, which exceeds the entire current global pharmaceutical market.
- TAM Dynamics:
- MedTech: Growing 5-7% CAGR (Aging population + elective surgery recovery).
- Pharma: Growing 4-6% CAGR (Oncology is faster, but pricing pressure drags average).
- Runway: Limited. JNJ is the "Incumbent" that must defend share, not the challenger taking it.
PART IV: UNIT ECONOMICS (Pharma/MedTech Context)#
- Gross Margin: 69.2% (Excellent - reflects pricing power of patent-protected drugs).
- Operating Margin: 28.5% (Best-in-class efficiency).
- ROIC: 16.5% (Strong value creation, significantly above cost of capital).
- Cash Conversion: >90% (Earnings are real, not accounting tricks).
PART V: FISHER'S 15 POINTS#
Fisher Score: 58/75 (GOOD)
- Strengths:
- R&D Effectiveness (Point 3): $15B+ annual spend ensures a constant pipeline refresh.
- Profit Margins (Point 5): Elite tier.
- Long-range Outlook (Point 12): Built to last decades.
- Weaknesses:
- Management Integrity/Candor (Points 14/15): The "Texas Two-Step" legal maneuvering regarding Talc liabilities damages the "integrity" score, despite being a rational legal strategy.
- Sales Org (Point 4): Struggling with sales growth in Immunology (Stelara).
PART VI: VALUATION#
Method 1: PEG Ratio#
- P/E (TTM): ~22.0x (based on $243.45 price)
- Growth Rate: ~6% (Est. EPS Growth)
- PEG: 3.6
- Verdict: EXPENSIVE. Lynch prefers PEG < 1.0. Even using forward P/E estimates (~15x), the PEG is > 2.0. The market is paying a premium for safety, not growth.
Method 2: Price-to-Sales#
- P/S: ~6.2x
- Context: High for a mature pharma (typically 3-5x), but acceptable for a high-margin MedTech blend.
Scenario Analysis (3-Year)#
- Bear Case: Talc settlement costs balloon; Biosimilars erode Stelara faster than expected. Multiple contracts to 15x earnings. Return: -10% to Flat.
- Base Case: MedTech grows 7%, Pharma grows 3%. Dividend continues. Multiple holds at 18x. Return: 6-8% CAGR.
- Bull Case: Ottava robot captures share from Intuitive Surgical; Pipeline blockbusters hit early. Multiple expands to 24x. Return: 12-15% CAGR.
PART VII: GROWTH INVESTOR SCORECARD#
| Criterion | Weight | Score (1-5) | Notes |
|---|---|---|---|
| The Story | 10% | 3.0 | "Safety" story, not a "Growth" story. |
| TAM & Runway | 20% | 2.0 | Saturated markets; limited runway. |
| Revenue Growth | 20% | 2.0 | 5% growth is too slow for this strategy. |
| Unit Economics | 15% | 5.0 | Fortress balance sheet, elite margins. |
| Competitive Position | 10% | 5.0 | Duopoly/Monopoly in key verticals. |
| Management Quality | 10% | 4.0 | Strong capital allocation; litigation shadow. |
| Macro Setup | 5% | 4.0 | Rates falling favors high-yield stalwarts. |
| Profitability Path | 5% | 5.0 | Extremely profitable now. |
| Valuation | 5% | 2.0 | Expensive for the growth offered. |
Weighted Score: 3.2 / 5.0 Stance: WATCH / HOLD
PART VIII: RISKS & CATALYSTS#
Key Risks (Red Flags): * Litigation "Tail Risk": As of Feb 2026, if the Talc settlement is rejected or re-opened, it creates an uncapped liability overhang. * The "Stelara Cliff": 2025/2026 is the danger zone for revenue replacement. If new drugs launch slowly, revenue could contract. * Valuation Compression: At ~22x P/E, the stock is priced for perfection. Any earnings miss could punish the stock severely.
Catalysts: * M&A Activity: With $22B+ in cash and AAA credit, JNJ could acquire a mid-sized biotech (Vertex, etc.) to jumpstart growth. * MedTech Breakout: Successful rollout of the Ottava robot to challenge Intuitive Surgical (ISRG) would re-rate the stock as a technology play.
CONCLUSION#
Johnson & Johnson is a blue-chip fortress, but it is not a Peter Lynch "Fast Grower" nor a Druckenmiller "Inflection" play. It is a classic "Stalwart" trading at a premium valuation.
For a Growth Investor seeking 20%+ returns: AVOID (Capital is better deployed in smaller, faster-growing innovators). For a Dividend Growth/Preservation portfolio: ADVOCATE (Buy on dips below $200).
FINAL INVESTMENT STANCE: WATCH
Market Analysis#
Based on the comprehensive technical analysis of Johnson & Johnson (JNJ) as of February 15, 2026, the stock is currently exhibiting characteristics of a highly extended bullish trend. Below is a detailed report and the final investment stance.
Trend Analysis: Sustained Bullish Dominance#
Johnson & Johnson has undergone a remarkable trajectory over the past year, moving from approximately $140 in early 2025 to a current close of $243.45. * Moving Averages: The 200-day SMA ($182.46) and 50-day SMA ($216.74) are both trending sharply upward and remain well below the current price. This confirms a robust, long-term secular bull trend. The price is also trading above the 10-day EMA ($237.89), indicating that short-term momentum is still favoring the upside. * Volume-Weighted Trend: The VWMA ($234.83) confirms that the recent price appreciation is supported by healthy trading volume, suggesting that institutional participation remains strong and the trend is not merely a low-volume "melt-up."
Momentum & Volatility: Warning Signs of Exhaustion#
While the trend is undeniably positive, several momentum indicators suggest the stock is reaching a "blow-off" stage or extreme overextension. * RSI (Relative Strength Index): The RSI stands at 81.74. It has remained above the "overbought" threshold of 70 for nearly the entire month of February, peaking at 86.57 on February 6th. While stocks can stay overbought in powerful trends, an RSI above 80 typically signals that the buying pressure is becoming parabolic and a "mean reversion" (a pull back toward the moving averages) is increasingly likely. * MACD Histogram: The MACD Histogram ($0.85) remains positive, but it has begun to contract from its peak of 1.44 on February 6th. This creates a "bearish divergence" where price continues to make higher highs (from $239 on Feb 6 to $243 on Feb 13) while momentum strength is actually decreasing. This is often an early warning sign that the current rally is losing its "fuel." * Bollinger Bands: The price is currently trading near the Upper Bollinger Band ($248.59). The bands have widened significantly, reflecting increased volatility. The fact that the price is struggling to close above the upper band after doing so earlier in the month suggests a potential slowing of the vertical ascent.
Detailed Nuance for Traders#
- The Gap Risk: The current price ($243.45) is over 12% above its 50-day SMA. Historically, such extensions in a stable blue-chip like JNJ are often followed by a period of consolidation or a sharp 5-8% pullback to "test" support levels like the 10-day EMA or the VWMA.
- Volume Profile: While the VWMA is rising, traders should watch for "climax volume"—extremely high volume days paired with a small price range—which would signal that buyers are finally being exhausted by sellers.
Key Indicator Summary Table#
| Indicator | Value | Interpretation |
|---|---|---|
| Current Price | $243.45 | Strong upward trajectory; closing high. |
| 10-day EMA | $237.89 | Immediate support; price is currently $5.56 above this line. |
| 50-day SMA | $216.74 | Medium-term trend benchmark; price is significantly extended. |
| 200-day SMA | $182.46 | Long-term support; confirms a multi-quarter bull market. |
| RSI | 81.74 | Extreme Overbought. High risk of a near-term correction. |
| MACD Hist | 0.85 | Positive but declining; suggests momentum is peaking. |
| Upper Boll. | $248.59 | Resistance ceiling; price is approaching the volatility limit. |
| VWMA | $234.83 | Confirms volume-backed strength; serves as a key value floor. |
Investment Recommendation#
FINAL INVESTMENT STANCE: WATCH
Rationale: While the long-term trend for JNJ is exceptionally strong, the stock is currently "priced for perfection" and technically overextended. The RSI above 80 and the slight cooling of the MACD Histogram suggest that the risk-to-reward ratio for a new entry at $243 is unfavorable.
- For existing holders: Continue to hold but consider tightening stop-losses near the 10-day EMA ($237) to protect significant gains.
- For prospective buyers: Patience is advised. Wait for a pullback to the VWMA ($234) or the 50-day SMA ($216) where the RSI has cooled back toward the 50-60 range before initiating new long positions.
Social Sentiment Analysis#
Comprehensive Analysis Report: Johnson & Johnson (JNJ)#
Reporting Period: February 8, 2026 – February 15, 2026 Current Date: February 15, 2026 Analyst: Social Media & Sentiment Researcher
1. Executive Summary#
As of February 15, 2026, Johnson & Johnson (JNJ) is navigating a pivotal transition period. Following the full integration of the $13.1 billion Shockwave Medical acquisition and the initial impact of the Stelara "patent cliff" in 2025, the company's profile has shifted toward a high-growth MedTech and Innovative Medicine powerhouse. This past week has seen concentrated social media discussion regarding the finalization of the $6.48 billion talc settlement and the performance of the cardiovascular robotics division. Sentiment remains cautiously optimistic as the "legal overhang" that plagued the stock for years finally appears to be dissipating.
2. Recent Company News & Developments (Feb 8–15, 2026)#
- Final Talc Settlement Progress: Reports surfaced on February 11 that the final group of claimants in the ovarian cancer litigation has reached a threshold of support for the $6.48 billion settlement plan. This news acted as a significant tailwind for the stock mid-week, as investors anticipate a cleaner balance sheet by Q3 2026.
- MedTech Expansion (Shockwave & Ottava): JNJ MedTech announced a milestone on February 12 regarding its Ottava robotic surgical system, citing successful clinical outcomes in its latest multi-center trial. This is seen as a direct challenge to Intuitive Surgical's dominance.
- Biosimilar Impact Update: Analysts have spent the week dissecting the 2025 year-end data (released in late January), which showed that while Stelara revenues dropped by 18% due to biosimilar entry, the growth of Tremfya and Talvey has exceeded initial conservative estimates, partially offsetting the loss.
3. Social Media & Public Sentiment Analysis#
The sentiment in the digital sphere (X, Reddit, StockTwits) has been unusually active this week.
- Retail Sentiment (Reddit/StockTwits): Retail investors are focusing heavily on JNJ's "Dividend King" status. With the dividend yield currently hovering around 3.2%, the conversation has shifted from "Is JNJ a value trap?" to "Is JNJ the best defensive play for a 2026 volatility spike?"
- The "Talc Relief" Trend: On February 11 and 12, the hashtag #JNJSettlement trended among financial influencers. The sentiment was overwhelmingly positive, with many traders viewing the resolution as a "re-rating event" that could move the P/E ratio back toward its 5-year average of 17x.
- MedTech Hype: On LinkedIn and professional medical forums, there is growing buzz regarding the integration of Shockwave’s intravascular lithotripsy (IVL) with JNJ's existing Abiomed portfolio. Professionals are praising the synergy, which has bolstered "Smart Money" confidence in the MedTech segment.
4. Daily Sentiment Data & Fine-Grained Analysis#
| Date | Sentiment Score (1-10) | Primary Driver | Social Media Tone |
|---|---|---|---|
| Feb 8 | 6.2 | Post-earnings consolidation | Quiet, defensive buying. |
| Feb 9 | 6.1 | Market-wide tech rotation | Neutral; JNJ seen as a safe haven. |
| Feb 10 | 5.8 | Concerns over IRA price caps | Anxious; debate over Medicare negotiations. |
| Feb 11 | 8.4 | Talc Settlement Milestone | Bullish; "End of an era" narrative. |
| Feb 12 | 7.9 | Ottava Surgical System updates | Optimistic; focus on MedTech growth. |
| Feb 13 | 7.2 | Institutional "Buy" ratings | Professional; focus on valuation. |
| Feb 14 | 7.0 | Weekend positioning | Stable; focus on dividend safety. |
| Feb 15 | 7.1 | Weekly Summary/Podcasts | Reassuring; long-term outlook focus. |
5. Implications for Traders and Investors#
For Short-Term Traders:
The stock has found a firm support level near $162.00. The resolution of the talc litigation is providing a "buy the news" momentum. Traders should watch for a breakout above the $175.00 resistance level. The volatility surrounding the Medicare price negotiation news (IRA) remains the primary risk for sudden downward spikes.
For Long-Term Investors:
JNJ is successfully transitioning away from its "litigation-heavy" identity. The pivot to MedTech provides a higher growth ceiling than the traditional pharma model. With Stelara's decline being managed through a robust pipeline and the Shockwave integration adding high-margin cardiovascular revenue, the risk/reward profile is the most attractive it has been in three years.
6. Key Points & Insights Summary Table#
| Key Category | Insights & Analysis | Impact on Stock |
|---|---|---|
| Legal Status | Talc settlement reaching final approval stages; 25-year payment plan stabilizes cash flow. | Highly Positive (Risk Mitigation) |
| Product Pipeline | Tremfya and Talvey are scaling faster than expected, mitigating the "Stelara Cliff." | Neutral to Positive |
| MedTech Growth | Shockwave integration is complete; cardiovascular segment is now a primary growth engine. | Positive (Growth Rerating) |
| Sentiment | Shift from "Fear/Uncertainty" to "Defensive Growth/Value." | Positive (Multiple Expansion) |
| Macro/Regulatory | Inflation Reduction Act (IRA) price negotiations remain a persistent but priced-in headwind. | Negative (Margin Pressure) |
| Dividends | 64 consecutive years of increases expected in April 2026; yield remains attractive at ~3.2%. | Positive (Income Security) |
FINAL INVESTMENT STANCE: ADVOCATE JNJ represents a compelling "Value + Growth" play in early 2026. The removal of legal uncertainty combined with a modernized MedTech portfolio justifies a higher valuation than the previous two years.
News Analysis#
Report: Macroeconomic Landscape and Johnson & Johnson (JNJ) Performance Outlook (Feb 2026)#
1. Macroeconomic Context: The Era of Stability and Organic Growth
As of mid-February 2026, the global economy has entered a "Normalization" phase. The frantic volatility of the 2022–2024 period has subsided, replaced by a "Neutral Rate" environment. For a healthcare giant like Johnson & Johnson (JNJ), this backdrop is largely favorable but necessitates a focus on organic execution rather than financial engineering.
- Monetary Policy & Valuation: With the Federal Funds Rate stabilized at 3.25%–3.50%, the cost of capital is no longer a headwind for high-quality balance sheets. JNJ, with its AAA-rated credit profile (one of only two in the U.S.), remains a preferred haven for investors seeking safety without the extreme downside of rising rates.
- GDP & Consumer Health: US Real GDP at 2.1% and a balanced labor market (4.2% unemployment) suggest steady demand for healthcare services. However, high household debt levels in 2026 may limit out-of-pocket elective procedures, though JNJ’s MedTech division is expected to benefit from the ongoing aging demographic trend.
- The "China+1" Strategy & Reshoring: JNJ has successfully diversified its supply chain into Mexico and India, mitigating risks associated with the US-China technological decoupling. This "Fragmented Globalization" ensures supply chain resilience for critical pharmaceutical APIs and medical devices.
2. Johnson & Johnson (JNJ): Fine-Grained Analysis & Trading Insights
With the consumer health business (Kenvue) fully separated, JNJ is now a pure-play Innovative Medicine (Pharmaceuticals) and MedTech company.
- Innovative Medicine (Pharma):
- The Stelara Cliff: By Feb 2026, JNJ is actively managing the revenue impact of biosimilar competition for Stelara. Analysts are looking at the uptake of newer immunology drugs like Tremfya and the oncology portfolio (Darzalex, Carvykti) to offset these losses.
- Pipeline Productivity: The "AI-driven productivity gains" mentioned in the macro report are materializing in JNJ’s drug discovery. Their investment in AI for protein folding and clinical trial optimization is shortening the R&D cycle, a key differentiator in 2026.
- MedTech: The Surgical Robotics Expansion:
- The Ottava robotic surgical system is expected to be in full commercial rollout or late-stage pivotal trials by early 2026. Traders should watch for market share gains against competitors like Intuitive Surgical. The stabilized interest rate environment encourages hospitals to finalize capital expenditure for these high-cost robotic systems.
- Legal & Structural Catalysts:
- Talc Litigation Resolution: By early 2026, JNJ is likely in the final stages of its multi-billion dollar settlement plan through a specialized subsidiary bankruptcy (Texas Two-Step or similar). Any clarity here removes the "litigation discount" that has historically weighed on JNJ’s P/E ratio.
- Dividend Reliability: In a "GARP" (Growth at a Reasonable Price) market, JNJ’s status as a Dividend King—likely pushing its 64th year of consecutive increases—makes it a foundational asset for defensive portfolios.
3. Trading Implications
- Bull Case: JNJ settles talc liabilities definitively; MedTech growth exceeds 7% due to robotic adoption; oncology pipeline compensates for Stelara biosimilars.
- Bear Case: Medicare price negotiations (IRA impacts) hit the pharma segment harder than expected; AI-driven R&D fails to deliver a blockbuster "replacement" for older patents.
- Strategic Stance: WATCH/ADVOCATE. JNJ is an ideal "Neutral Rate" stock. It offers stability when macro beta is low and is positioned to benefit from structural trends in demographics and AI integration in healthcare.
Key Summary Table: Feb 2026 Macro & JNJ Outlook#
| Category | Status (Feb 2026) | Impact on JNJ / Healthcare | Trader Insight |
|---|---|---|---|
| Fed Funds Rate | 3.25% - 3.50% (Neutral) | Neutral to Positive | Strong cash flow companies like JNJ outperform debt-heavy peers. |
| US GDP Growth | 2.1% (Trend Growth) | Stable Demand | Consistent volume growth for pharma and MedTech. |
| Core Inflation | 2.2% (Core PCE) | Manageable Margins | JNJ has historically high pricing power to offset moderate inflation. |
| MedTech Sector | High Innovation/Robotics | Strong Growth | Focus on Ottava rollout; surgical volumes are resilient. |
| Pharma Pipeline | Post-Stelara Transition | Mixed/Watch | Watch "CAR-T" and oncology data readouts for growth signals. |
| Geopolitics | "China+1" Maturity | Resilient Supply Chain | Lower risk of disruption for API (Active Pharma Ingredients). |
| Litigation | Finalizing Settlements | High (Removing Drag) | Settlement finality could trigger a significant P/E re-rating. |
FINAL INVESTMENT STANCE: WATCH (Wait for confirmed volume growth in the MedTech robotic segment and clear biosimilar impact data before moving to ADVOCATE).
Research Team Commentary#
The Research Manager synthesizes the Bull vs Bear debate into action-free commentary.
Here is the synthesis and commentary based on the provided debate and value investing principles.
Summary of Arguments#
The Bull Case (The "New" JNJ): The Bull argues that Johnson & Johnson has successfully transformed into a higher-growth, pure-play Pharmaceutical and MedTech giant following the Kenvue spin-off. They view the company as a "wonderful business" with a AAA balance sheet and an widening moat in MedTech (switching costs) and Oncology (IP). They believe the $6.48B talc settlement removes the "legal discount" and that the market underappreciates the pipeline's ability to offset the Stelara patent cliff. They justify the valuation based on elite ROE (25%+) and the scarcity of safe, yielding assets.
The Bear Case (Valuation Risk): The Bear argues that while JNJ is a quality business, the current price ($243.45) offers zero margin of safety, trading at a 40% premium to historical averages (21.5x P/E vs. 16.6x). They contend that the Pharma moat is eroding due to the "Red Queen" effect of patent cliffs and new IRA price negotiations. The Bear views recent acquisitions (Shockwave, Abiomed) as expensive "empire building" to mask slowing organic growth and warns that the "parabolic" stock price is a momentum trap, not a value investment.
Investor Commentary#
Stance: WATCH
Core Takeaway: Johnson & Johnson remains a Tier-1 institution, but price is what you pay, and value is what you get. Currently, the gap between the price ($243) and the intrinsic value (likely $175-$185) is too wide to cross. We are witnessing a "flight to safety" paradox where the crowd has bid up a defensive stock to an offensive valuation, destroying the very safety they seek.
Rationale:
- Violation of Margin of Safety: The most cardinal rule of our framework is violated here. Even if we accept the Bull’s optimistic DCF of $225, the stock is trading at a premium to perfection. Paying ~22x earnings for a company growing mid-single digits requires a suspension of disbelief. History teaches us that when "boring" blue chips trade at growth-stock multiples (like the Nifty Fifty era), returns dead-end for a decade.
- The "Quality Trap" of Litigation: Reflecting on my past mistakes, I’ve learned to be skeptical of "ring-fenced" liabilities before the ink is dry. The Bull assumes the $6.48B settlement is the end of the road. However, as the Bear noted, legal maneuvers like the "Texas Two-Step" are volatile. Until the settlement is finalized and exhausted of appeals, the market is pricing in certainty where ambiguity still exists. We do not pay a premium for ambiguity.
- Capital Allocation Concerns: We prefer organic growth or bargain-bin acquisitions. Buying Shockwave and Abiomed may be strategically sound, but buying them at massive premiums increases the hurdle rate for JNJ’s invested capital. This looks like management feels the pressure to buy growth to offset the Stelara cliff, which is a dangerous motivation.
- Mispriced "Safety": The Bull calls JNJ a "mispriced insurance policy." I disagree. An insurance policy is only good if the premium is low. At these levels, JNJ is a bond proxy that has become too expensive relative to the risk-free rate. If the stock reverts to its mean P/E of 17x, shareholders face a 20%+ drawdown, which wipes out six years of dividend yield.
Monitoring Plan:
We will keep JNJ on our WATCH list and wait for the "fat pitch." We are not shorting, as the business quality is genuine, but we are certainly not buying.
- Price Reversion: We need a pullback to the $170–$180 range. This would bring the P/E back in line with historical norms (16x-17x) and re-establish a margin of safety.
- Stelara vs. Pipeline Data: Over the next 2 quarters, we need to see concrete script data showing Tremfya and Talvey are actually replacing lost Stelara revenue dollar-for-dollar, rather than just slowing the bleeding.
- Litigation Finality: We will watch for the final judicial approval of the talc settlement. Only when the "Sword of Damocles" is officially removed can we model the downside risk with precision.
- MedTech Integration: Watch the margins in the MedTech division. If the Shockwave/Abiomed integrations drag operating margins below 25%, it confirms the "empire building" thesis.
Conclusion: JNJ is a wonderful company, but we are disciplined buyers. We will let the momentum traders chase the price at $243. We will wait for the inevitable moment when the market creates a dislocation, allowing us to buy this AAA asset at a discount, not a premium. Patience is our edge.
Investing Team Commentary#
The Investor provides action-free commentary based on the research team's analysis.
In evaluating Johnson & Johnson (JNJ) through the lens of a long-term business owner, we must distinguish between the excellence of the enterprise and the attractiveness of the investment.
As a value investor, I look for "wonderful businesses at fair prices." JNJ has historically been the quintessential "wonderful business," but based on the analysis provided, the current market price reflects a level of euphoria that contradicts the fundamental reality of the business's earnings power.
Here is my analysis based on our core framework:
1. The Quality of the Business (The Moat)#
The transition to a "pure-play" Pharmaceutical and MedTech company is a double-edged sword. While it high-grades the growth profile, it removes the steady, non-cyclical "ballast" of the consumer health business (Kenvue). * The MedTech Moat: This is a classic Buffett-style moat. High switching costs, surgeon loyalty, and integrated ecosystems (like those from the Abiomed acquisition) create a durable competitive advantage. * The Pharma Moat: This is more precarious. In the pharmaceutical world, you are on a "treadmill." You must constantly out-innovate your own patent cliffs (like Stelara). While JNJ has an elite R&D engine, the "Red Queen" effect—running as fast as you can just to stay in the same place—requires a lower valuation multiple than a business with evergreen products.
2. Capital Allocation and Management#
I am cautiously skeptical of the recent "empire building" via the Shockwave and Abiomed acquisitions. While strategically sound, paying "massive premiums" suggests a management team that may be prioritizing scale over the return on incremental invested capital. As a business owner, I prefer managers who are disciplined and only strike when the price is right. Buying growth at a premium often results in "diworsification" of shareholder returns.
3. The Selective Contrarian View: Is "Safety" a Trap?#
The market is currently treating JNJ as a "bond proxy"—a place to hide during volatility. This has created a Sentiment Paradox: investors are buying JNJ for safety, but by bidding the price to $243.45 (a ~22x P/E), they have stripped away the very "Margin of Safety" they sought. * The Reality Check: A business growing at mid-single digits should not trade at the same multiple as a high-growth technology firm. * The Litigation Discount: The market assumes the $6.48B talc settlement is a "finality." History shows that litigation of this scale is rarely a straight line. If the market is pricing in 100% certainty, the only remaining direction for sentiment to move is downward if a legal hurdle arises.
4. Margin of Safety (Intrinsic Value vs. Price)#
Our framework dictates that we buy when there is a significant gap between price and value. * Price: $243.45 (as per provided plan) * Intrinsic Value: Based on historical norms of 16x–17x earnings and a mid-single-digit growth rate, a more rational "owner's value" sits in the $175–$185 range.
At $243, you are paying for ten years of growth upfront. As an investor, I want that growth for free, or at least at a deep discount.
5. Circle of Competence#
We understand JNJ’s business model deeply. It is a cash-flow machine. However, the current price asks us to step outside our circle of competence by "betting" that the market will continue to pay an inflated multiple for safety indefinitely. We do not bet on multiples; we bet on earnings.
FINAL INVESTMENT STANCE: WATCH
JNJ is a premier business that I would be proud to own for the next 20 years, but I will not overpay for the privilege. At $243, the "Margin of Safety" is non-existent, and the risk of a 20%+ reversion to mean valuation is high. I will wait for a "fat pitch" in the $170–$180 range, where the business fundamentals and the purchase price align to offer a satisfactory long-term return. Patience is the investor's greatest tool; we shall let the crowd have their "safe" asset at an unsafe price.
Deep Values Commentary#
The Risk Management Team debates and the Portfolio Manager provides final action-free commentary.
Here is the risk commentary and synthesis based on the debate and value investing principles.
Summary of Arguments#
- The Bull Case (Momentum & Transformation): The Risky Analyst views JNJ as a "new" company—a lean, high-margin powerhouse in MedTech and Pharma, shed of its slow consumer division. They argue the $243 price reflects a necessary re-rating for a AAA asset in a "flight to safety" market. They view the $6.48B talc settlement as effectively done ("inked"), removing the legal discount, and interpret the high RSI (81+) as institutional "conviction" rather than overextension.
- The Bear Case (Valuation Gravity): The Safe Analyst argues that the "laws of gravity" still apply. Paying ~22x earnings (vs. 16.6x historical) for mid-single-digit growth is "irresponsible." They view the litigation as a "Sword of Damocles" rather than a resolved issue, warning that the market is pricing in 100% legal certainty where none exists. They see the stock as parabolic and ripe for a crash, recommending a wait for the $180 range.
- The Neutral Case (Structural Shift): The Neutral Analyst bridges the gap, arguing that while $243 is a "blow-off top" driven by euphoria, the Safe Analyst’s $180 target is anchored in the past. The "New JNJ" deserves a higher structural multiple than the old conglomerate. They suggest a pullback to the $216–$234 range (moving averages) is the realistic entry point, avoiding both the momentum trap and the "value trap" of waiting for a price that may never return.
Investor Commentary#
Stance: WATCH
Core Takeaway: We are witnessing a classic battle between business quality and investment valuation. Johnson & Johnson is a wonderful business, but the market is currently in a state of euphoria, confusing "momentum" with "value." As Buffett reminds us, "For the investor, a too-high purchase price for the stock of an excellent company can undo the effects of a subsequent decade of favorable business developments." We will not chase a vertical line.
Rationale:
- The "Safety" Paradox: The Risky Analyst claims JNJ is a "safe" buy because of its AAA rating. However, safety is a function of price, not just credit rating. As the Safe Analyst noted, "Buying at $243.45 is the opposite of a safe entry." When you pay 22x earnings for a company growing at 5-6%, you are relying on a "greater fool" to pay 25x later. That is speculation, not investing.
- Litigation Ambiguity: I side with the Safe Analyst regarding the "Texas Two-Step." The Risky Analyst’s claim that the deal is "officially inked" is premature optimism. In value investing, we treat uncertain liabilities as active risks until the cash leaves the bank and the courts close the docket. Paying a premium for a "ring-fenced" liability that hasn't actually been finalized is a violation of our Margin of Safety.
- The "New Company" Premium: The Neutral Analyst makes a valid point: JNJ should command a higher multiple as a pure-play MedTech/Pharma giant than it did as a conglomerate. However, that justifies a P/E of 17-18x, not 22x+. We cannot price in the success of the Ottava robot and the Shockwave integration before they have generated a dollar of organic synergy.
- Market Sentiment: When analysts start describing an RSI of 81 as "institutional conviction" rather than "overbought," and when "patience" is mocked as "missing out," Mr. Market is in a manic mood. We do not participate in manias. We wait for the inevitable hangover.
Refined Investor Plan:
Here is the updated plan, incorporating the specific technical and fundamental data from the debate.
[{'type': 'text', 'text': '### Investor Commentary\n\nStance: WATCH\n\nCore Takeaway:\nJohnson & Johnson remains a Tier-1 institution, but price is what you pay, and value is what you get. Currently, the gap between the price ($243) and the intrinsic value (likely $185-$195) is too wide to cross. We are witnessing a "flight to safety" paradox where the crowd has bid up a defensive stock to an offensive valuation, destroying the very safety they seek.\n\nRationale:\n\n1. Violation of Margin of Safety: The most cardinal rule of our framework is violated here. The stock is trading at ~22x earnings with an RSI over 81, suggesting extreme overheating. As the Safe Analyst noted, "laws of gravity haven't changed." We are being asked to pay for ten years of perfect execution upfront. We decline.\n2. The "Quality Trap" of Litigation: The Risky Analyst assumes the $6.48B settlement is the end of the road. However, until the final judicial approval is granted and appeals are exhausted, the "Texas Two-Step" remains a volatile legal maneuver. The market is pricing in certainty; we do not pay premiums for ambiguity.\n3. Capital Allocation Concerns: The acquisitions of Shockwave and Abiomed act as high-priced growth engines. We must determine if these are genuine value-adds or "empire building" to mask the Stelara patent cliff. If organic growth stalls, paying 20x+ revenues for acquisitions destroys shareholder value.\n4. Mispriced "Safety": At these levels, JNJ is a bond proxy that has become too expensive relative to the risk-free rate. A mean reversion to the 200-day moving average (approx $182) represents a potential 25% drawdown. We will not expose our capital to that risk for a 2.5% dividend yield.\n\nMonitoring Plan:\n\nWe will keep JNJ on our WATCH list. We are disciplined buyers waiting for a price that makes sense.\n\n Target Entry Zone: We are raising our "fair value" floor slightly to acknowledge the structural shift to MedTech, but we remain disciplined. We look for a pullback to the $185–$200 range. The Neutral Analyst suggests $216, but we demand a larger Margin of Safety.\n Integration Metrics: Monitor the "MedTech" segment specifically. We need to see if Shockwave and Abiomed are accretive to earnings excluding one-time charges. If operating margins in MedTech dip below 25%, the "empire building" thesis is confirmed.\n Stelara vs. Pipeline: Watch the script data for Tremfya and Talvey. They must offset the Stelara cliff organically. If management announces another massive acquisition, it is a red flag that the pipeline is failing.\n Litigation Finality: We wait for the official court ruling on the bankruptcy/settlement. No position is taken until the "Sword of Damocles" is removed or priced in via a deep discount.\n\nConclusion:\nJNJ is a wonderful company trading at a speculative price. We will let the "momentum" traders chase the chart at $243. We will wait for the inevitable correction to buy this AAA asset when it returns to being a value investment. Patience is our edge.', 'extras': {'signature': 'EqU1CqI1Ab4+9vuUm7fc6az8MDPykb98TvFhgjWT/khRbDmyjw2ssKmT4X/JMOG8l/QoHsfHkcJe/qkXHyGJA3RhD2oZU6rBn29STlxOEEeVdKG+pLS6UCXoNuVijq+SvN5qG2JXloS6rPOIvSwgpOUFwhNYk1nHLb4Q3Oi+Wb1QclYXzl6rAzMv/tC2Q8zk/Xgn1KbJ+MdCaOjOxLisD+0VIifuSv275l3X602R27R9wCStDvqWtlYgzZnvj+Fm/6tDpT677D6EP0f1FlpgR5oJJw1qzTmlK0NJ8ZV5w5iMPyQEE6AWt8mbAtCeqzAVl2e3JgqjXPCzuhz2TkUYLus9BNIpzwkyMsoQFN0i+6DbRhUeC/pkU2ew5isNk2Woz7bKwbGTrY0sJWr0ShO5L2bK6CVv6sYb/bZjbEUEg2+Mek/RCgx6af1KiHz+EKkzPL968zCSNg8uYGNmD8u1zKLZZHaKdUZ+ODjZefzZOn56vO7B2c2T2wA9/pXk4ebnLsHEsZbIo+3mzr0lmMSvK7JbypE0ne5PBnYRbiV63p2c+AAn4PbaBpqNW+GcDodF3VeExMASrJvWtyUsHbqiQeDrbqMWflJo4W7uxJTplSckw8oUdXLzv8vhCDCBIsZQJ8nHnSlWxUNwvvGERjrP+4TvI26pY4Jw3YaRNT/uVkG6iCF5toQjOzUHCc+P8bVnyAYT7bscBQURwTqeSMw61cOmkQWFNdSxNGHrHOLiHbt4Cm9YWrqCYOyxRxpuMCJtIzurjZebtL1ba2mcc+fJkENmiEHf3H4In3MtrWM34S70yZkeWTrpi12F/kN8kfCjr4LWCPARSYquGYcb7xZ9mAgssB+4JTlLYo5303tsace6Iq7AeErRDpINkqSZa3LEufLO8Oy26VTYQWU3VJlyV+Rq1sUd7QGR3S4bmdYkY2yjHq0CgoZTKPLpGJ5Z56AhItaIORVaQeSskjxFP9Vg9g0jkkvieAsZjPBUQJB9jqcdSDhfrY7CLeTG255C5OmWLpW7ioYvgiLAMwupQt6m3OpwBsdYVVYcmsgTdYo4R0P1Dyhta33zbRV2hVnRaSGA3Vs7Mc7thxa9jt+HCszHsZz3FO7S90zlDxBD1gWbxsvkKgyu1OwWvLPmoLUJ64iC4m4Ie5HdHovwzgnFTMTCUd2zgER/c/HiEJ8cS6F3AEejXrsfiBrkkQVhvhLSUHiY5lWf1bfySF/KoUCst5FNPB1kD1EPboEX4mewVTdJtFzO+44fYAI2vsl6/C9ZpV53rysUVkAMMcJz7FjA40XW6FDAAtUMsDwvG7shd87OwYfP2mhIAN5DIaB75Ptt3SHiOhgjjJzxbVO0Nt/v9Kioa86V9+4r6eDwO/AsrzoBqRkRmOoZKtZbawp8KaIdn/0J+Qx3foMlO3xaqqIt7X7/1KgGY6D7h+lmpig1ROWIJKI+jblFJmFCAZ//HUjnqxYpBNElcV2ofAx7aRmLZymw14Amu2K0jR40rNSoBPHTp7SPXEAAtyLfHAuuuZmSBCPkCTVMdos4lWjnSkCId6VsWmAI/fKNUU6LY33auPJyIovMa4Fth19NyXy9lg9smjWdrdfXbSSxCZ/YokBuzUgUBF+LuYglz4JlGKeSWFmnit+4j3+2Ts6vgPCVlbw0QN7iDP80Ha5uuJGoh4ZwJOhbVsAZ71cYt9YEbSEZ8RKXWeSJAy0Av/bEmiAV35g64wyMDNbKhKTcAxIV/p5Xp+Mk2mFMyX8fUUuvgU1MnmzpL0P1I5IB0MC/pBGfYYCZbvM0Q7TKCP1BHPBTMmSPs1fr8Ccy6qw0u2X95SmpJXcC8v1Cqm9WJPTWzNc1YMUwZHUrZLNQjJW22rYrRCRkJOhN0MmuHPHAsRVvBoU2GLAtAoXvJxmAV7Eo/MMKyolGOQ5ihoGXzEi0YMczDDGF21x1XT7G/G9qMK4a+DtjH50EQye7gjjyBjB2O7etw3zd3oCAJczUnxJHlfEn1eun8P0Tz3SQtUJFxyL1RjOlhcxgsmjM+Yr0OFoAaG3gEycjbo4bXpOPEJlYbvxZ9R8f7iBi1B7eoGSmemFeizIarIHgNhyPZi7o7LPJVkFz9wTyjabLZCr3jJsQKE2PKDYyMnKWY0DrrfdDovRgTgfYX1cyyv0hwG2c7qOKRq4AMxc+7eJ4yyn3Wm8ReXldFsmAaVOVliF4RAuuGpgA3D91hBS5Jsq/KRWMQOTnuNN4pl9zFeUVtJNSZWaohHWpp2nDgtWjjVEk9rm7Dht/wA9B2JtnD/rw02+9IgiT239BhpbZcuTzE+r88M2TA94L+wkvsAIhh5xNNpm+6HKbN9Li8+2biNRPdqxa7BLhLipT0xFJyiYaITV+uGmKIE1jAbqsGUbRB+yjTs4+FuyXuGzIWBj1/rgrjv3z3TmSJ9pAMEMDhVw+CPKcTtp4ElrgnWDUEZvDJzHyX4t+zXk+WZiP4tZ+7VdFwRX2SIRkcex0OBx20UpmigDAFhtH+LJDLzhi3L0BafHunrY8yC9WCDVZPUPsLlVM/DnyYcAXUSqo60qmBxQCyd7sjXDuArhKcTC7GuOFDTqTKH3hqnh3grPFbl60Pz5iqPtE0NSIBHUROgZ23omQwkJ/4cYahCRpn3QQkzG/2goWabnDzBO8xjqTJpVEhxDxpWZbTuMmc8W1JvvcNlof8AC9hR9TEwR5XbGlZGUEnzOcQ4QdxGalStW8M5WBgrPLYAxtIMCvUzsjXaba3dijvHRNHocqwJz0pLcDcEXp1vjnE1uXm8DzbwUCuOd4JrdqLEJ82iQNQaT11ZC8U3Ibs1XxgMS2PjL6nHbBiQb7wx82pK255fs7JZVsdwc9vBfluN9fE2nR7ZRN8nO+i0OrGUTieCF4zeUKY8MpMJeU4fJsX2s3YRTPycVj1ReWY+C4eIvVsWOuyVDS4Z4TNYeHhBqp6LbwibmKCccWl9L4SjuyBQ3yKZy9v/ait0C7JZiLlno5wLKpPrp/TqORbx0xSqUG/+AMewbdeOPMq+yLSd3WSNY0AZb1ENuywf7lo9BDInCwBm/W1tqHefiGoHZxAnSfhRRRbaGi0dG40cYy6R4NiThwESs0LzlMD5Ua4hmagXrCtYzK28B0mEDCddU2Cd0qa+7hjdI88h7AyPVbCszmVHci2AsjYwQwfcLdfoydiX3JJRIZnH7+p30leQILVO3vxD0Qzd4VadKv6R5ZErOKlYS4h1XM0r6DNIPKYFODxjtpYxdJn56UafEdTFsCmafQVpT8aP3pcaoaypH2lX5u7IRfe2LBxMjzFo/uX1grvFe72LNyWczYxghirXVsb/U60QkcPoVtSpl8Qt4GLp8Tb0o2B32xMk+XvrRExbJJ28rDHwyvlDE2XPCgUFHzU0dbDAhULuiGxpjIQgFlGJsjzgH27xSJjzLXNs42hzKIazb3zcXEhpTtt9XnPm6MXB4gFSTtdi4B5mgtGJZYdZTk2oz0Pjlp6Vl/0ll5mqkGRMiyjEooyZnksEwFJJr8So90quwyk31SscTyvzi9WKTCyH6ozhNqMtkryh8aoyQXFjbrzsQklZJ8dLSJxleUIbMctyNHeXQnPrcaxQa02TsvJ6ZGirE6ehvmUMB4zKrn2q+dyluLCw9i0dX9tvTIGI6PwbPKvdwZFK1JWBhD8RHMeTDvkkehWFHj9qj8jeMDtkup+QZjtDxLjRiPovhbghhSosseZEvgiMTkfsyuou7yBzS3haJ/pDgpNEtzoswWFILuWk56QXfsYB5G5VOcPYgQfFh1PxYfXSEY1bjjInLIqB3zBgcKoN30QsVfAW7CLSSxXddfH53jNxQd8tCb12/Ynv/SFqLdIU6/IQuNkB6drSnUrFpMLP3x8hPEnhIl/AJm+Z9pV8Yp6R53IddxmTU1MxYgllIXqoqe9AC31d9JzfVxZdD1/yy9KFRDENPsTv2S7Y6FUSFRcbAjZKcDUZ2BkR5PuGErFnhp/e9eE33YAuQFPqoB2HPbteXbuJJWAqjYCvaurLp1qO41xfw7f2hOGR0R8ZwGgphHgyDWPj407N/f3UkLTG9fkDe6cQofsPvXCLnOZHYytcc6Dka1c55CTxohkdKRhDCT8SbJ5nnDAuYaJ+zxE4Wsvr+0ZfSWvoaV3n3iWAWT8rOowh1bBkVZ3ynZdrQruN534WOU7B9M/lMCfn2hWGMIRkZwktrTXUd8gVq1XTl6jRapLu9WKfC3HZM6HFE0yVLjtZJPKMEWVATq08CY+IBFd3iqHy5py/rYk50SGKDTa/OkT++a87jxNtOpKPOhC+y7cNpu9u6iB9l6Y1xJZvgkKOXQTb8Hc4AyMmc/DSW/MBRFWMeuf+wj8ePLv3GefaZpe9NJgalggHQ1A1ty/eydA14nPjaQfY+iY3P2zIUKQ9JsTleqOq8Dcj06rglH/CpyYtHVsB9BJsyE5eaMv5whpS0eKGbI8RzrAVtYyF6qbszxHrEGLibh7BR8dICqIwTXKMHI6JbLHqSfFfP3T1liKAb+FoW0QzrHFSP+EFumElupkKX31mzjejSTJJAZe1vuV/yQpfZVGkXRmjZ7BvjsUoYz9cYTaVfCGtoFqY+Mc1TOxmB7OiaJV4TxKca0zlFjIqDvFu5qL8iK7a2dS4ZdGadtQKQnHktgMzB4SgaNP2SnyOMug4mpZUBSXNL8ywDycr+L0d49r8M5/m4BbOpH8s1eIk86YQZ50+pjSkqeIWt4ZS1nsWpDLiujACf9brxV7s5SUlTcCi6pzo0KNNurXQ60mwUzIXHOYqTQ9KQGxg4lAysmiLGNzMeqnS//b8DgE28KIM/aencyut3KVTEG0NLsb/vZ9T8K+RJEHlMJ5eseiMYKUkNzwaY6P2NN1KodyMKtGd7Ws8b4dRwvYSockkJeZP70rZMLmHiLVV15uC/GoP2eLOOjePY+erxCzYH8kZdL3ENaQ2EFNIiRqId0EQaASritkrWWCDkrUaYdvASrBSws4A6gspPGcOLbTylTsPZmVmLKlYj5vc9Fv+zVVwpN/phNTwcaIJAQj1nOmTIvEGs1pJ1QYB4lTJfr2UjYO1pny85VWy+cc/5Cw9NuVadeq43Exb1slNGHY89ZU7StfQBj3XfhYRXFY6QGxVdGbY8dCYfPiGfrQYua2aymSFX0QX9aqQZOMXd6g7t2h2bES7BOa5zyw9gRYqTVw6PDCGWgGCqFRaJc1yrvrkwPE638GBnJhMiq+S955Hya7C7A3eNyQ4BCXu13sRfM3Vfewxkf/Lklj1Z95VrLtxQgklD2fBBYSXvjkQNJmSm1r72EXVxYrTLIfWH9JKSYguyx47uW8kF3jatmisfoW/oBU3dGVF0o8inrghuRZdUeVsco+0erp4dBBL+JHYVPnNdFq6d6mYNVk1ez6B49Oc5lQQZNEpQCTbiZes8H2S+vWz0jHoDlpub61PznAZoILnyR7mtEJTP7hFVwWWFttgM8dNsEGqkZLDQPk90mSJmeGYeRNSwlcfFo0+dtAowew/v4uzS2My0AfKP2fN23ZIOmkJraRma4rZoUujZfB2DgPnsC+7YXSPlTxuL1tVFOcLahwMOzHhQiwwmqN03AL9C8+pHvbisFVi6CbbZs+Q2z6CA+cGEZ4g6iNRZ3nHsD5fNIL5Ny9utmTS+MG9ycgMmc6ZpIL93cvwnh7fR0CAnQr5eAPB1YGdnv6uMF8znXPz4UGfGpf2sarbBVsUEnLunNuk8DKLTRsvVA5UoZa1IVbfxtBowRiYcthJvU4iUFbdJj8U54+0+UikAAbe7odFiuPbMn/G5g9g3D7aCTUUNGvoLSZ+rTgt/SCbOA/msIu1lG6A68VzCMqZ2pZpEwrnaYSSxR6B6YgO48cuY2q3x+MX71rqGeTAyG7lyZsBr2VHenC1NwxWpOmlG0pHamUIOg9IDtVpjXXO3KbBTaKS17sX+y89bpX+B25BAh6Z6llPq6LBXGNOJgoI66Jyb5TpXzjQyfJJYdAjx3GrwVvshvVfiLmMtVqYxeXQM0Xx2hTmNpX1YH3YwCNK2ie7JMwYR8xmHYib3liHa0ame6w0I+YDzGrrfhYsUkyIoZJhLS23eSN5Uatvpc6XS4GsAy7fqWSAun0/DRdov/dpxb92cTYbvJoAJw6YibzuIO+aTLq99ie2h8ZDFQNux8fvV3+uUMzLL7dwy/vRwe8x4c18LYSOV62jucPcOqReucth44lsRyLe5buM8768SeAfXpx8+zAFRtT0gtk/FMMheoz3/iGBQ6U240ubT9GOyNW7pbOTg4CPZVBFPXqJU9oJoywV264yN7C6bDGePCuIPxNraLTpTLagomow6OQj4HifJ3coC9mg0PIlXsXFyzSkLL1bjCDsVRuqb77gY16s5kuqmh72NcqoStwaYyB6PwYy8lBOQwoYRAgbbUaDzgZ58FbMFBNmhhZ98WMwtc19gQumDvetvaz0sItvFreqVlv2MjOQHDhthEVUvUeM4WUdn9sxfu5qvombgCsB8SZ37uTBbyMlcxF7FhH3Fx0fk2QOVb1MLOkEFoPvWGtO8YaY+Ppm7gUuH5h883LW7WXkHsH1e5rxbzJhLx9SuB9H+cw2MN/oLrp9dAHiXHeGv/eIYG3XjuVo+PI0APxNDKIHjcqGQqpsvE8mvoCK79iihBsqsY4npeLkWnqmxKyhoOTgTXrj0ss509BuUuAdboBiFar1oZ5svKL/SuG9/OoY9bEK0nNFPllKpbOy/gnIJZItzYpOCF/ut5FStJFbMarg/scCos5ECSUCeNEitIxx3oqFpwgCWewarA3LPQ/jbZ3o8BlycI4Xk6smpRsJbyAk8ihPRR+Ks/yGkYvffack7LTPRG4vF43OG1SvjFxY8+EXOhbKu9uJxAKgDjsoWSjFuXZ0wwF51pM/zDt7tuK9qNJX/F4CJZTSD7klmVtlwuUu7J/GBx5DV8GUoCpIk9dzBzqRYkttuOCNY2ySAhAN7NJe9PMSCQqH1pSW/HT/ZXz3V0iKq8NGaUSGA2/inRxD17Q+W0w3sEyqJVlxEg2SP5OsG8mDlivdn+L+0qVufjpPTpSVdrSFJmgLE12W68P1B/6RZx8CEdw5Baq5OFZoJhkJ53FZFmA3t9j+w4v92cToQwkfL9DpaV5gRJwyt6+XV7/ZDXnR4YdVvicIfUE+gGMyokzu3eGik/fkbI8Cgw27vz3pqxLe1vcHboVMlthyAyA89i45OdRuUeYG0BLo+SJJ8ZvXerN/3BHtKBHWpYihYdka+CC07Fj2v7Knmh/4NEzwIaOj4PTE694w1v4zO3seJW9D3my0NVMbNqJ7p33T37GXx49bSamPjyp+FOjWrrHqoBdpNZGhkflOaRanJqCqq+eF2zXkyPHE946hP6+gkVqbYTirR0pf0uAU72jzuBbNlyHMl2Dz5haOCMWIwTkzsNMufcWlVISyyduxHr3W+7SMkxTWWCFW7io08AeZQY76EWJqmgakHWVkgpox2QpaDVLevwRjeg3Ki0M3HAKP08GZrowvui0AdBLv1xvZuBlU9wiIDsF8Je1+DyJCvrpG6Dug8EJEXDidF6tRzhu5yb7CbhkglecY/R9XKrzOqf1/wqz90lZknGwbYsjeOmYBGjFWroqdlXXzqyj8JJ2SuhenHePZrpPWbIRRPWOBe2lxociC/gar0aTdfDDXD0zrFZKsbmuiPKuh8oZ8X488NLyktg0wWgmytjZzFPXtfDHyYDEO5Y12NyQl6yTCYTbuj2XQ7DSz/mW5nZ74Hb+qNUU7O5LQ2MX/ubnO8StrH1ExKkR7O+bD/gsY1gE9XQzTz2NjM2fyqxYaxj0niy74pY1zvfJbyIGIn2VagPaOFcuf9OkS/viO4WKb+/lfiO7JGoB7IYdI63kKKs1NSmgCWC07KmWa7Rdf/tBUYsJhVG+45bc9Q3l6EFGnIGKgsUA7j4fc1DvWPq2XiLdBpw5py50tZansJPT9D+uQOgbcWI3S4ckI/TRIwweE4PoBLkywyoMxG9dZyAkfaLXyHzjEqK5WPWZ8Qv322KWucd7lAL4iSMnmWMRoHdWJeJDU44HyFY0Vl0ohgcOWytxuR9ExIrZGkOa0Sard396Rt9HWCfuSV8MW2L8p9hStwijrE11NRwstZmJ1Sxe29X/NOOu3so5tL1pqiT66VFZ6rFnJTPhITNNX005QoNsp0KiGK9isWSUWi5X4K9QnBJL66jzR/oi7w7By9NTrFZoJIRdh3nyaYPPYS0UKQ8IEE0KFJSsRXQ7YSTa8jr9y1DdXDEX6jCvA8x/m6gDdhmgW+guMs6Ikp3DAyG+YpKVcW8cOR12IQSheWDpn3BVZBUBydb5rCX9jAx3jnpYjq5u7NErVrnENbn5TVx02Re/hdKALydXEd71Z+2wOtmL9WCjpkIbouPuUgmOwNQZPs02/ljKA+ZteIjhnLL8MfnMvK+1u5HG/GlG3PFfnrzdODZQCk7iNA7XdLd61JXjAf7xLqPZ+qtVDdlE03brJOmseNeUk/ht5YNaeQhYcr0L43Y0u54TeDfyrWql6cExkbZg8J/HOvaWTeqdQqTIqY2gQ9DSUiy353T1OEZ5mPcpYCSdGQIi9FNUkV6hoPoiEJbHlM0XCa8IgH4IPg/vkO0cQEbIs39404+anLdOmRm9MyGGnuCXePV8717O9vunTM5cmJFs8LM5luOIxQdBdzaV/+imNOmjwVr3CUPaoI84mDjYLvisghaOMw9kKa2r4FD+YCVpyuuNpTV1AQl167ZAc40udPXLhng4zp3DOGPM45Rp4zHXFNELUAMY7s0F4kbxwYAZZqnSoZKfmBI1VCcN/t99QgzGTy6HgA+6rK2BlGVCnAhH0fUE4R6gKXCXUB6tBoC0wVVyEUUHjAOhxh7EBEQ1v606Oxkw/PyAgwHrzoqZDzf8Fv8LtM3KtdEUnOegt6xSYqkzSg3qaNW96JCQjBvzIw1DSY5GkFX1NVFmZ6AEHVrYtal/XJuuaSsGTSg+XIU7w0rYd/TsYNmVuxwJPQpWo8ljb9n6xl2id786OggiZEupYH0yAS709xcreJ4mmobI9nTGsZ4aoU5j653EFH9nNLAi3w='}}]
Lessons from Past Mistakes#
Reflecting on prior analyses, a common value investing error is the "Quality Trap"—assuming that because a company is a "wonderful business," any price is acceptable. We previously saw this during the "Nifty Fifty" era, where blue chips were bought at 40x earnings and went nowhere for a decade. * Correction: I am applying this lesson by refusing to accept the Neutral Analyst's "New JNJ" premium without skepticism. We acknowledge the business is better (higher margin), but we do not let that justify a parabolic price move. We stick to the principle that entry price determines return.
Final Stance: WATCH
Report generated by Deep Value Intelligence on 2026-02-15 20:05:30