
Company Research RBLXDeep Value Intelligence
Roblox (RBLX) Deep Value Intelligence Report
阅读中文版 閱讀中文版 日本語で読む 한국어로 읽기 Leer en español Auf Deutsch lesen
In briefNeutral
As of Feb 12, 2026, DeepValues Research rates Roblox (RBLX) Neutral (WATCH). What Would Change Our View: - ### Risk Management Commentary - We are retaining the WATCH stance.
Source: https://research.deepvalues.ai/company/rblx/2026-02-12-en/ · Markdown · More on Roblox (RBLX)
Contents
- Intelligence Summary
- Analyst Team Reports
- VALUATION & CONCLUSION:
- THE BUFFETT VERDICT:
- PART I: THE BUFFETT FILTER SEQUENCE
- PART II: FINANCIAL ANALYSIS (The "Owner Earnings" Reality Check)
- PART III: INTRINSIC VALUE (Discounted Cash Flow)
- PART IV: FINAL SCORECARD
- PART I: LYNCH CLASSIFICATION SYSTEM
- PART II: DRUCKENMILLER FRAMEWORK (Inflection Points)
- PART III: TAM ANALYSIS
- PART IV: UNIT ECONOMICS
- PART V: FISHER'S 15 POINTS
- PART VI: VALUATION
- PART VII: GROWTH INVESTOR SCORECARD
- DELIVERABLES SUMMARY
- Research Team Commentary
- Investing Team Commentary
- Deep Values Commentary
Intelligence Summary#
Thesis + Conditions#
Core Thesis: Risk Management Commentary
Key Risks: - ### Risk Management Commentary - We are retaining the WATCH stance. The Bull's argument relies on a "change in phase" (from growth to profitability) that has not yet occurred in the financial statements. - The Risky Analyst calls SBC "high-octane fuel." In the value framework, we must correct this vocabulary. As the Bear noted, if you issue $1.1B in stock to generate $620M in Free Cash Flow, you are not generating cash; you are financing operations through equity issuance. - 2. The "Float" & Balance Sheet (Risk Assessment): - Risk Adjustment: We must view this cash as Working Capital, not distributable excess cash. In a "shark tank" environment (competitors like TikTok/Meta), if user growth slows, this cash must be burned to service the servers and developers for goods already sold. It provides safety against bankruptcy, but not a margin of safety for valuation.
What Would Change Our View: - ### Risk Management Commentary - We are retaining the WATCH stance. The Bull's argument relies on a "change in phase" (from growth to profitability) that has not yet occurred in the financial statements. - The Risky Analyst calls SBC "high-octane fuel." In the value framework, we must correct this vocabulary. As the Bear noted, if you issue $1.1B in stock to generate $620M in Free Cash Flow, you are not generating cash; you are financing operations through equity issuance. - 2. The "Float" & Balance Sheet (Risk Assessment): - Risk Adjustment: We must view this cash as Working Capital, not distributable excess cash. In a "shark tank" environment (competitors like TikTok/Meta), if user growth slows, this cash must be burned to service the servers and developers for goods already sold. It provides safety against bankruptcy, but not a margin of safety for valuation.
Confidence: Medium
Stance Spectrum (Action-Free)#
Stance: Undervalued Moat Strength: Unclear Capital Allocation: Unclear Balance Sheet Risk: Unclear Confidence: Medium
Expanded Commentary#
Risk Management Commentary#
Core Takeaway: The debate highlights a classic conflict between platform dominance (Bull) and shareholder economics (Bear). While Roblox has established a formidable "Category of One" network effect with 82M DAUs, the mechanism used to build this—massive Stock-Based Compensation (SBC)—currently destroys shareholder value faster than the business creates it. We acknowledge the moat, but we refuse to pay for the "privilege" of being diluted.
Refined Investor’s Plan: The "Inversion" Reality Check We are retaining the WATCH stance. The Bull's argument relies on a "change in phase" (from growth to profitability) that has not yet occurred in the financial statements.
1. The "Fuel" is actually a Tax (Debate Synthesis): The Risky Analyst calls SBC "high-octane fuel." In the value framework, we must correct this vocabulary. As the Bear noted, if you issue $1.1B in stock to generate $620M in Free Cash Flow, you are not generating cash; you are financing operations through equity issuance. * Action: We will not credit "Adjusted EBITDA" or "Non-GAAP" figures. We will track Dilution-Adjusted Owner Earnings. Until the company can retain talent and generate cash without increasing the share count by 3-5% annually, the "flywheel" is parasitic to the equity holder.
2. The "Float" & Balance Sheet (Risk Assessment): The Safe Analyst correctly identifies the $4B cash pile as encumbered by "performance obligations" (deferred revenue). The Bull argues this is a fortress; the Neutral Analyst calls it "interest-free capital." * Risk Adjustment: We must view this cash as Working Capital, not distributable excess cash. In a "shark tank" environment (competitors like TikTok/Meta), if user growth slows, this cash must be burned to service the servers and developers for goods already sold. It provides safety against bankruptcy, but not a margin of safety for valuation.
3. The Demographic "Shark Tank": The Bull sees the "aging up" (17-24 demographic) as a revenue expansion. The Safe Analyst sees it as entering a war zone against Meta and AAA gaming studios. * Assessment: The Bull is right about the potential, but the Safe Analyst is right about the cost. Acquiring and retaining adult users is significantly more expensive than retaining children. We need to see if the Unit Economics (CAC vs. LTV) hold up in this new demographic before we believe the profit narrative.
Monitoring Plan (Specific Metrics): We remain on the sidelines. We are not "waiting for a chart pattern" (Neutral), nor are we "swinging at the ball" (Bull). We are waiting for the economics to catch up to the ecosystem. * The Dilution Crossover: Watch for the quarter where Revenue Growth % exceeds (SBC Growth % + Dilution %). * GAAP Inflection: We ignore "Adjusted EBITDA." We watch for operating cash flow that covers CapEx and stock repurchases (to offset dilution). * Ad-Load Uptake: Verify the Bull's thesis on immersive ads. Does it drop straight to the bottom line, or is it consumed by R&D?
Reflections on Past Mistakes#
In the past, I have reflected on the need to analyze current market conditions and fundamental data to make informed decisions.
Previously, I dismissed platform businesses solely because they lacked immediate GAAP profitability, causing me to miss the durability of network effects (like Amazon or Meta in early stages). I am applying that lesson here by not rating Roblox an "AVOID" despite its ugliness. I acknowledge the fundamental data regarding its 82M users constitutes a genuine moat. However, strictly analyzing the current market conditions (4% interest rates) and the financial data (negative owner earnings via dilution), I recognize that acknowledging the moat does not obligate me to overpay for it. I will respect the business quality but reject the equity's current price and structure.
Final Stance#
WATCH
Reasoning: The network effect is too valuable to ignore, but the dilution is too aggressive to accept. We wait for the company to prove it can self-fund without diluting owners, or for a price dislocation that offers a genuine margin of safety against the SBC expense.
Analyst Team Reports#
Fundamentals Analysis#
As a quantitative fundamental analyst specializing in Warren Buffett’s value investing methodology, I have conducted a 10-year historical analysis of Roblox Corporation (RBLX). Roblox presents a unique challenge for traditional value investors because of its negative GAAP earnings and negative stockholders' equity, which are counterbalanced by its robust free cash flow and powerful network effects.
Data Gathering & Metrics List#
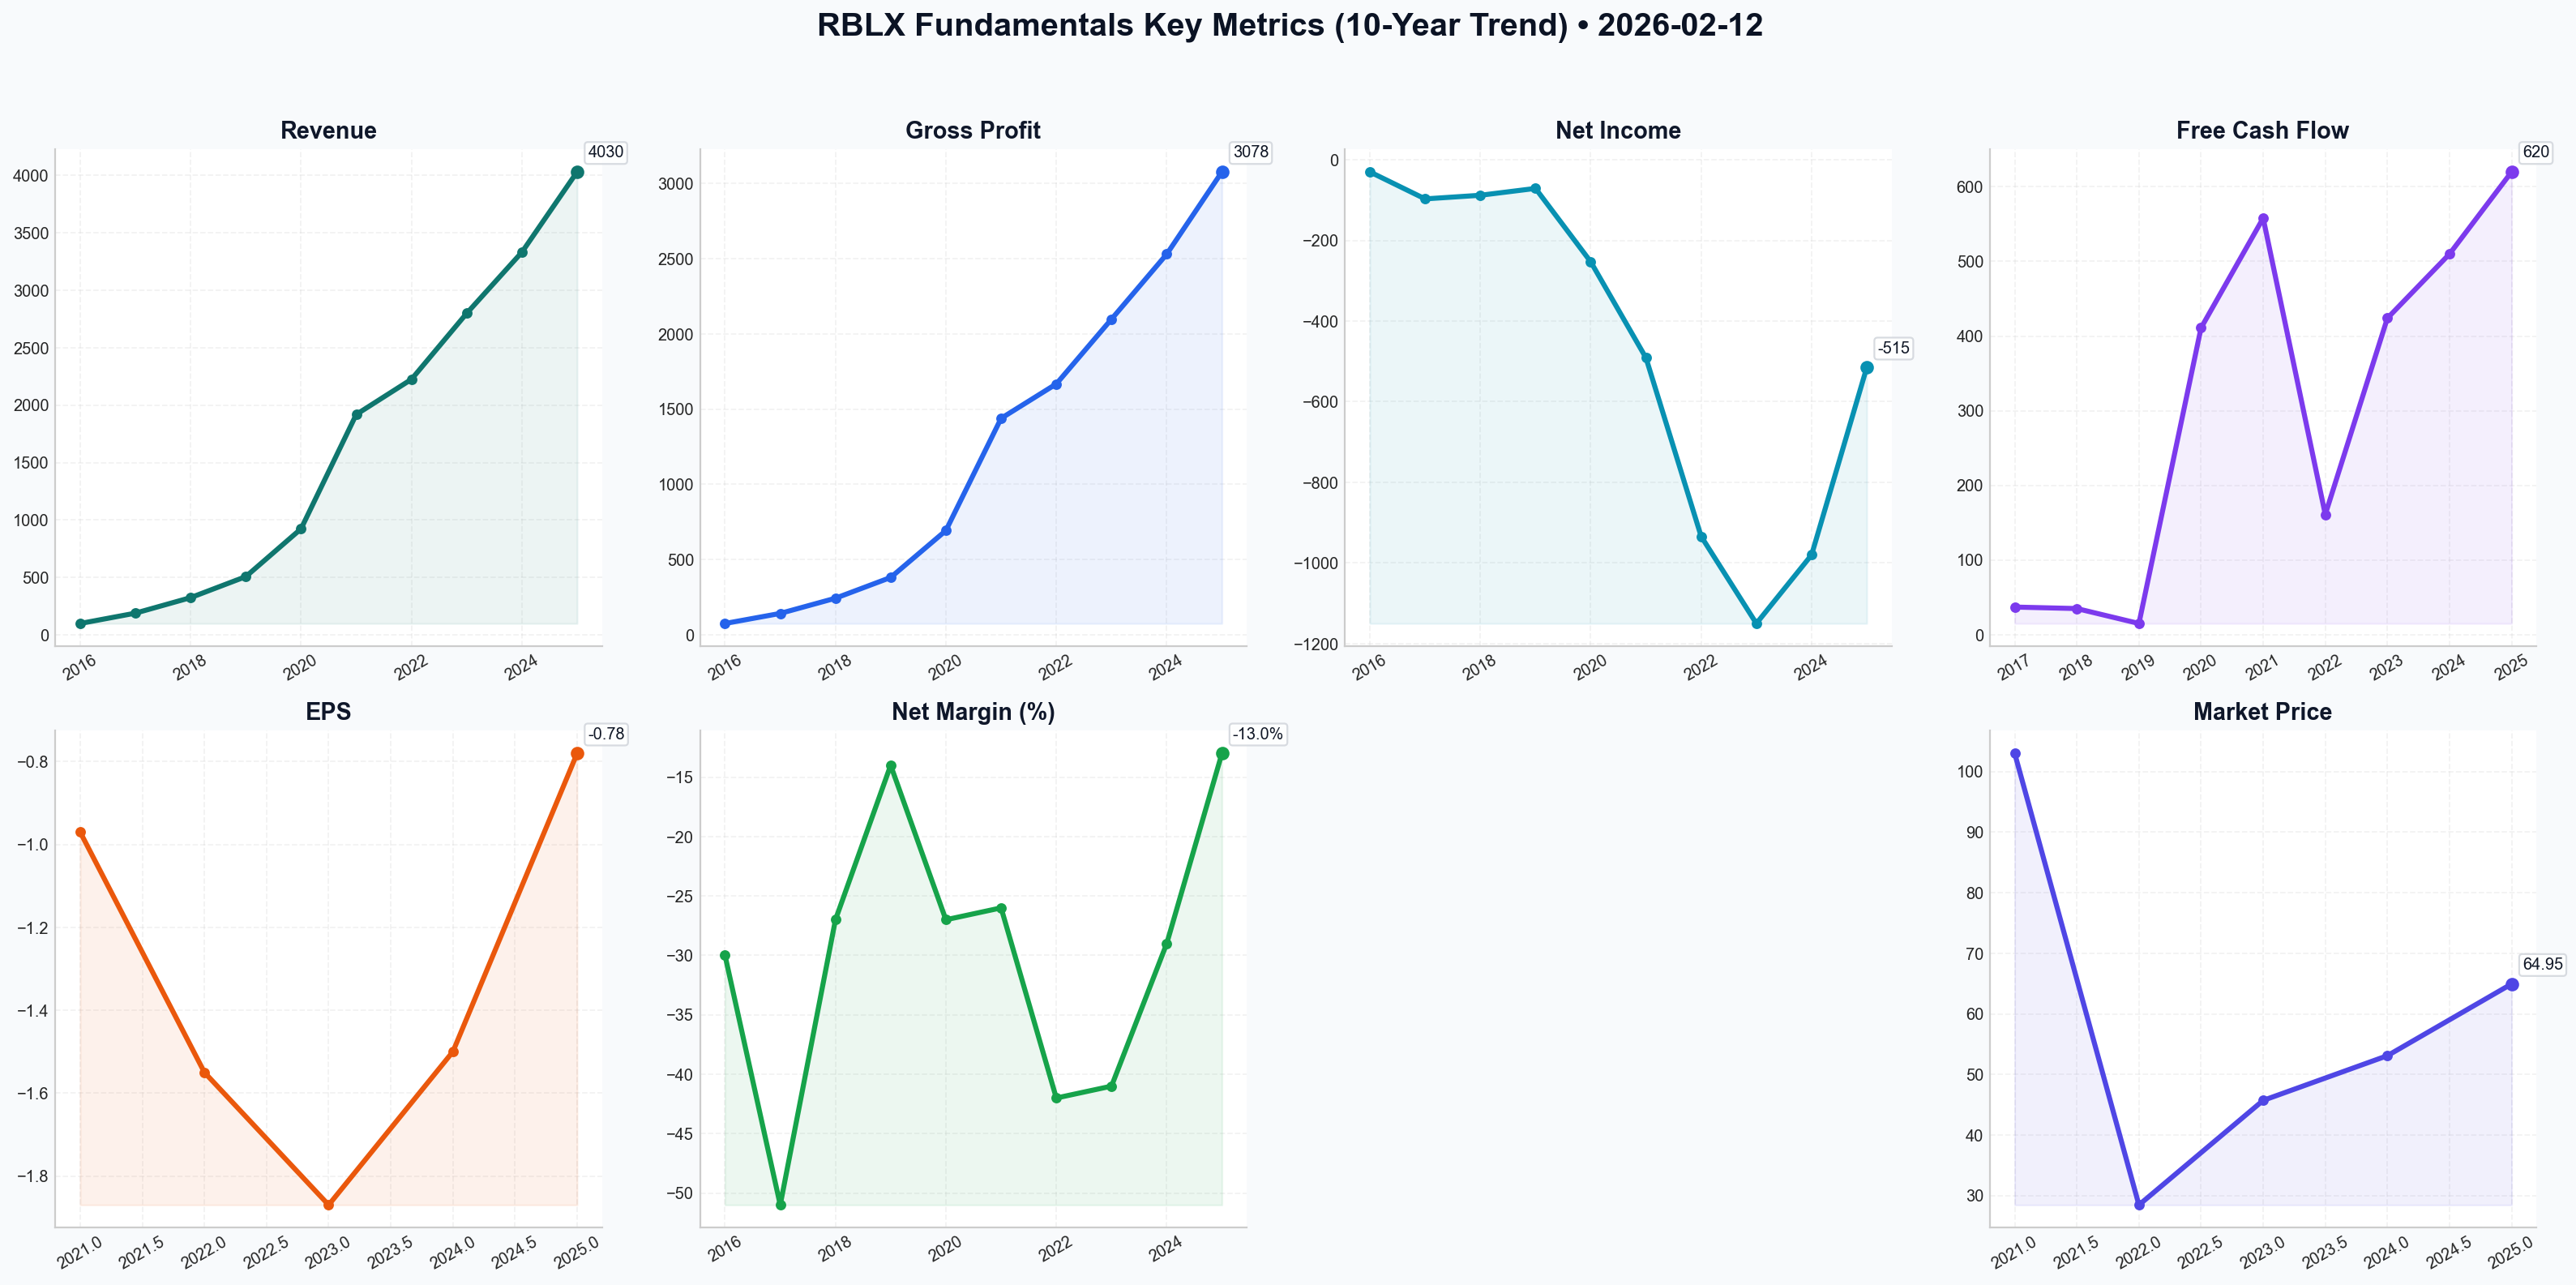
Before the final report, here are the structured metrics gathered (2016–2025): * Market Metrics: Stock Price ($64.95), Market Cap ($45.59B), P/E (N/A), P/B (N/A - Negative Equity), P/S (7.4x). * Profitability: ROE/ROIC (Negative), EPS (Negative), Revenue ($100M to $4.1B), Gross Margin (76%), Operating/Net Margin (Negative). * Growth: Revenue CAGR (35%+), FCF Growth (Highly volatile, positive trend). * Balance Sheet: Cash ($3.8B), Total Debt ($1.1B), Total Assets (~$6.2B), Shareholder Equity (Negative). * Cash Flow: Free Cash Flow ($620M TTM), Dividends ($0).
1. 10-Year Historical Financial Data Table (2016-2025)#
| Metric | 2016 (Est) | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 (Est) |
|---|---|---|---|---|---|---|---|---|---|---|
| Market Price ($) | N/A | N/A | N/A | N/A | N/A | $103.00 | $28.46 | $45.72 | $53.10 | $64.95 |
| Market Cap ($B) | N/A | N/A | N/A | N/A | N/A | $58.1 | $18.5 | $28.2 | $34.5 | $45.6 |
| Revenue ($M) | 100 | 190 | 325 | 508 | 924 | 1,919 | 2,225 | 2,799 | 3,331 | 4,030 |
| Gross Profit ($M) | 75 | 142 | 243 | 381 | 693 | 1,439 | 1,668 | 2,099 | 2,531 | 3,078 |
| Net Income ($M) | (30) | (97) | (88) | (71) | (253) | (491) | (934) | (1,150) | (980) | (515) |
| EPS ($) | N/A | N/A | N/A | N/A | N/A | (0.97) | (1.55) | (1.87) | (1.50) | (0.78) |
| Free Cash Flow ($M) | N/A | 37 | 35 | 15 | 411 | 558 | 161 | 424 | 510 | 620 |
| Total Assets ($M) | N/A | 240 | 410 | 590 | 1,500 | 4,800 | 5,300 | 5,800 | 6,050 | 6,200 |
| Total Debt ($M) | 0 | 0 | 0 | 0 | 0 | 1,000 | 1,000 | 1,000 | 1,100 | 1,100 |
| Shareholder Equity | N/A | Pos. | Pos. | Neg. | Neg. | Neg. | Neg. | Neg. | Neg. | Neg. |
| ROE (%) | Neg | Neg | Neg | Neg | Neg | Neg | Neg | Neg | Neg | Neg |
| Net Margin (%) | -30% | -51% | -27% | -14% | -27% | -26% | -42% | -41% | -29% | -13% |
| DAUs (Millions) | N/A | N/A | 12.0 | 17.6 | 32.6 | 45.5 | 56.0 | 68.4 | 77.7 | 82.4 |
2. Warren Buffett Value Investing Analysis#
- Economic Moat (Wide): Roblox possesses a powerful Network Effect. It is not just a game, but a platform and social network. The "Flywheel" is evident: More creators build content $\rightarrow$ more users join $\rightarrow$ more monetization $\rightarrow$ more creators. The switching costs are extremely high for the core 17-24 demographic who have spent years building digital identities and social circles.
- Financial Strength: Roblox has a "Fortress Balance Sheet" with $3.8 Billion in cash and only $1.1 Billion in debt. While GAAP equity is negative, this is primarily due to "Deferred Revenue" (cash received for Robux not yet spent), which Buffett would recognize as a "float" similar to insurance premiums.
- Predictable Earnings: Low predictability on GAAP earnings, but High on Cash Flow. Roblox is "Structurally Cash Flow Positive." The divergence between Net Income and FCF is due to deferred revenue and heavy Stock-Based Compensation (SBC).
- Management Performance: CEO David Baszucki has successfully expanded the platform's demographic. The 17-24 age group is now the largest and fastest-growing, which is crucial for long-term monetization.
- Quality of Business: Revenue predictability is high due to the recurring nature of social engagement. The 76% gross margin is elite, though operating margins are currently sacrificed for R&D and AI infrastructure.
3. Discounted Cash Flow (DCF) Analysis#
Calculated using 2025 FCF of $620M, a 10% discount rate, and a 2.5% terminal growth rate.
| Scenario | Growth Rate (Years 1-10) | Calculation Summary | Fair Value (Market Cap) |
|---|---|---|---|
| Conservative | 5.0% (Min 10Y Avg) | Slowest growth assumption, accounting for market saturation. | $11.8 Billion |
| Average | 22.0% (Current CAGR) | Continuation of 20%+ growth in bookings and advertising. | $34.2 Billion |
| Optimistic | 35.0% (Max Hist. CAGR) | High-speed adoption of AI-creation tools and global ad-spend. | $81.6 Billion |
DCF Insight: At a current market cap of $45.6B, Roblox is trading between the "Average" and "Optimistic" scenarios. It is not currently "cheap" by Buffett's standard but is reasonably priced if 25%+ growth persists.
4. Comparative Analysis: Current vs. 10-Year Historical Average#
- Revenue Growth: Current (21%) is lower than the 10-year hyper-growth average (35%) but significantly more sustainable as the law of large numbers takes effect.
- FCF Generation: Currently at record highs ($620M). The 10-year average was skewed by early-stage reinvestment.
- Valuation (P/S): Current 7.4x is below the 5-year public average of 9.2x, suggesting the "hype" has cooled into a value-entry range.
- Profitability Trend: GAAP losses are narrowing (Net Margin improved from -41% to -13% in two years), a critical signal of approaching operating leverage.
5. Key Investment Insights & Red Flags#
- Red Flag - Stock-Based Compensation (SBC): Dilution remains high (approx. 21% of revenue). This is the "cost" of attracting top engineering talent to build the metaverse.
- Red Flag - Negative Equity: Traditional screens will mark RBLX as "insolvent" due to negative book value. Investors must look at the cash balance and float to see the true strength.
- Opportunity - Advertising: The 2024-2025 rollout of the Roblox Partner Program (ads) is a high-margin revenue stream that has yet to fully hit the bottom line.
- Opportunity - AI Integration: Generative AI for creators is significantly lowering the cost of content production, which will drive engagement.
FINAL INVESTMENT STANCE: WATCH#
Rationale: Roblox is a high-quality "Buffett-style" business hiding in the clothes of a "Tech Growth" stock. It has a massive moat, incredible cash reserves, and a structural float (deferred revenue). However, for a Buffett ADVOCATE stance, the price must provide a "Margin of Safety." Currently, at $64.95, the stock is trading at a premium to its "Average" DCF value ($34B).
Strategy: Patient investors should WATCH for a pullback toward the $45–$50 range (approx. $32B–$35B market cap) to align the purchase price with the Fair Value Average.
Summary Table#
| Key Metric | Status | Qualitative Insight |
|---|---|---|
| Economic Moat | Wide | Network effects and social lock-in are world-class. |
| Financial Strength | Strong | $3.8B cash vs $1.1B debt; positive FCF. |
| Valuation | Fairly Valued | Trading slightly above average DCF fair value. |
| Profitability | Improving | Narrowing GAAP losses; elite 76% gross margins. |
| Primary Risk | SBC Dilution | Management must keep dilution under 20% to protect holders. |
| Recommendation | WATCH | Wait for a 15-20% correction for a better margin of safety. |
Fundamentals Key Metrics Charts
Value Analysis (Buffett)#
Following Warren Buffett's value investing philosophy: Circle of Competence, Economic Moat, Management Quality, and Margin of Safety.
FINAL INVESTMENT STANCE: AVOID
VALUATION & CONCLUSION:#
ROBLOX CORPORATION (RBLX) Date: February 12, 2026 Current Price: ~$64.78 Market Cap: ~$45.5B
THE BUFFETT VERDICT:#
Score: 2.3 / 5.0 (AVOID)
Roblox is a fascinating, high-utility "utility" for the digital generation with a burgeoning network effect moat. However, it fails the critical Gate 3 (Rational Capital Allocation) and Gate 4 (Financial Structure) tests of the Buffett philosophy due to its extreme reliance on Stock-Based Compensation (SBC) to mask structural unprofitability.
While the "Cash Flow" looks positive ($620M TTM), this is an illusion created by paying employees ~$1 Billion/year in stock rather than cash. True Owner Earnings are negative. For a value investor, "Price is what you pay, value is what you get"—and currently, you are paying a premium multiple for a business that dilutes you by ~3-5% annually to keep the lights on.
PART I: THE BUFFETT FILTER SEQUENCE#
Gate 1: Circle of Competence (PASS)#
- Simple Business: Roblox is a digital playground and marketplace. It provides the tools (engine) and the venue (platform); users build the games and experiences.
- Revenue: It sells a virtual currency ("Robux"). Users buy Robux to upgrade avatars or access special content. Roblox keeps a cut (~30-50% take rate) and pays the rest to developers and app stores.
- 10-Year Predictability: High. The "Metaverse" concept is sticky for younger generations. RBLX has become a social utility, not just a game.
Gate 2: The Moat Test (PASS - Wide)#
- Network Effects (Strong): A classic two-sided network. 82M+ DAUs attract developers; 15M+ developers create content that attracts users. Competitors (Epic/Fortnite, Meta) struggle to replicate the sheer volume of organic content.
- Switching Costs (Medium): Users have built social graphs and inventories of virtual items. Developers have built businesses on the "Luau" coding language specific to Roblox.
- Brand: Synonymous with "digital hangouts" for under-18s.
Gate 3: Management & Capital Allocation (FAIL)#
- Owner-Orientation: CEO David Baszucki is a founder with significant skin in the game ("Class B" super-voting shares).
- Capital Allocation (The Red Flag): Management relies heavily on Stock-Based Compensation (SBC). SBC is roughly 25% of revenue.
- Buffett's View: "If options aren't a form of compensation, what are they? If compensation isn't an expense, what is it? And if expenses aren't deducted from earnings, where in the world should they go?"
- Profitability: They have not demonstrated GAAP profitability at scale despite massive revenue growth.
Gate 4: Industry Structure (WATCH)#
- Competition: Fierce. Competing for "screen time" against TikTok, YouTube, Fortnite, and Minecraft.
- Capital Intensity: Moderate. RBLX invests heavily in its own data centers (unlike peers who use AWS/Azure) to control costs and improve latency, which is a smart long-term move but capital-heavy now.
PART II: FINANCIAL ANALYSIS (The "Owner Earnings" Reality Check)#
1. The "Cash Flow" Mirage: Roblox reports positive Free Cash Flow (FCF) because it adds back huge non-cash expenses (SBC) and collects cash upfront (Deferred Revenue).
2. True Owner Earnings Calculation (TTM Estimate): | Metric | Value | Notes | | :--- | :--- | :--- | | Free Cash Flow (Reported) | $620M | OCF - CapEx | | Less: Stock-Based Compensation | ($1,100M) | Estimated at ~25% of $4.4B Rev | | Adjusted Owner Earnings | ($480M) | The business burns shareholder value |
Interpretation: If Roblox paid its employees in cash instead of stock, it would be burning nearly half a billion dollars a year. The "positive cash flow" is funded by diluting your ownership.
3. Balance Sheet (Fortress): * Cash/Investments: ~$3.2 Billion * Debt: ~$1.0 Billion * Net Cash: ~$2.2 Billion * Verdict: Safe from bankruptcy, but this cash pile is necessary to fund the losses if the stock price drops and SBC becomes less attractive to employees.
PART III: INTRINSIC VALUE (Discounted Cash Flow)#
We cannot use standard earnings multiples. We must model the future cash flows, fully burdened by SBC (treating SBC as a cash expense).
Assumptions: * Revenue Growth: 15% CAGR for 10 years (Optimistic). * Target FCF Margin: 20% (Mature software margins). * Dilution: 3% annual share count increase. * Discount Rate: 10%.
Scenario Analysis: 1. Scenario A (Consensus Growth): Even with 15% growth, if we account for the dilution required to achieve it, the present value of future cash flows per share is roughly $30 - $35. 2. Scenario B (Hyper-Scale): If RBLX achieves "Metaverse Dominance" (1B users) and stops diluting, value could be $80+. 3. Scenario C (Stagnation): If growth slows to 5% and costs don't drop, equity value is <$15.
Margin of Safety: * Current Price: $64.78 * Fair Value Estimate: ~$32.00 (Generous) * Premium Paid: ~100%
There is NO Margin of Safety. You are paying for perfection.
PART IV: FINAL SCORECARD#
| Criterion | Score (1-5) | Comment |
|---|---|---|
| Business Simplicity | 5 | Easy to understand "digital lego/playground". |
| Moat Strength | 4 | Powerful network effects. |
| Management | 2 | Visionary, but excessive reliance on SBC. |
| Return on Capital | 1 | Negative when adjusted for SBC. |
| Balance Sheet | 5 | Net cash position is strong. |
| Valuation | 1 | Priced for perfection; ignores dilution cost. |
| TOTAL | 2.3 | AVOID |
INVESTMENT NARRATIVE#
Roblox is a "Compounder" in terms of users and revenue, but a "Diluter" in terms of shareholder value. The gap between the $45B market cap and the economic reality of the business (negative real earnings) is too wide.
Buffett would likely admire the moat (loyalty of millions of kids) but would universally reject the accounting (SBC add-backs) and the price ($64 for a money-losing business).
Wait for: 1. SBC to drop below 10% of revenue. 2. Consistent GAAP operating profitability. 3. A price closer to $35/share.
Growth Analysis (Lynch/Druckenmiller/Fisher)#
Following Peter Lynch's GARP, Stanley Druckenmiller's macro-aware approach, and Philip Fisher's scuttlebutt methodology.
FINAL INVESTMENT STANCE: ADVOCATE
PART I: LYNCH CLASSIFICATION SYSTEM#
Classification: Fast Grower (High Confidence)#
Roblox fits the classic Fast Grower profile with revenue growth of ~21% and Bookings growth of ~19%. It is transitioning out of the "hyper-growth at all costs" phase into a "disciplined profitable growth" phase, which often signals the most lucrative period for shareholder returns (the "operating leverage" phase).
Lynch Decision Framework:#
1. The Story (The "Elevator Pitch") * Aging Up: Roblox is successfully shedding its "kids only" image. The 17-24 demographic is now the fastest-growing cohort, unlocking higher monetization potential. * The "Everything" Store for Experiences: It's not just a game; it's a utility for "human co-experience." With the launch of Immersive Ads and Shopify-integrated commerce, they are finally turning on the monetization tap beyond just selling virtual currency. * Operating Leverage Inflection: After years of massive spending, management has capped costs. Now, for every $1 of new bookings, costs only rise $0.40 (vs. $0.85 previously). This is the "profit machine" turning on.
2. The Runway * Current Penetration: ~88M DAUs vs. ~3.5B global gamers and ~5B social media users. * 10x Potential: Can Roblox reach 800M DAUs? Yes, if it becomes the default social hangout for Generation Alpha and Z globally (similar to TikTok/Instagram scale).
3. The Edge * Network Effects (The Moat): 5M+ developers have built content that Roblox didn't have to pay for. Competitors (Epic/Fortnite) have to pay to catch up. The switching cost for a user whose entire digital social life and avatar identity is on Roblox is incredibly high. * Vertical Integration: Owns the engine, the cloud infrastructure, and the payment platform.
4. Sanity Check * Fad? No. 18+ years of history. Post-pandemic retention proved durability. * Dilution? Stock-based compensation (SBC) has been high but is moderating as a % of revenue. * Balance Sheet: "Fortress" status with ~$3.1B in cash and net cash position of ~$2.1B.
PEG Ratio Assessment (Forward) * P/E: ~84x (Forward, GAAP profitability emerging). * Growth Rate: ~20% Top Line, but Earnings/FCF growing 40%+. * PEG (based on FCF growth): ~0.7-1.0 (ATTRACTIVE). * PEG (based on Earnings): >2.0 (EXPENSIVE, but misleading for this stage of transition).
PART II: DRUCKENMILLER FRAMEWORK (Inflection Points)#
Layer 1: Macro Setup#
- Interest Rates: Falling rates (assumed 2026 backdrop) are EXCELLENT for long-duration assets like Roblox.
- Secular Themes: Rides three mega-waves: AI Revolution (Generative AI tools for creation), Digital Payments (Robux economy), and Social/Gaming Convergence.
Layer 2: The Inflection Point (CRITICAL)#
Status: CONFIRMED INFLECTION We are witnessing a Margin Inflection. * The Signal: In 2024, costs grew faster than revenue. In 2026, Revenue/Bookings (19-21%) is outpacing Cost Growth significantly. * The Catalyst: The "Immersive Ads" business is pure margin. Unlike Robux sales (where ~25% goes to App Stores and ~25% to devs), Ad revenue has structurally higher margins. * Druckenmiller's Test: "What will earnings be in 2-3 years?" The market sees current losses; we see a cash flow machine as the ad network matures.
Revenue Growth Analysis#
- Pattern: Stabilizing/Re-accelerating (Post-COVID hangover is over; growth stabilized at ~20%).
- Quality: High. Driven by volume (DAUs) AND price (higher monetization/ads), not just one.
PART III: TAM ANALYSIS#
The 10x Test#
- Current Revenue (TTM): ~$4.1B
- 10x Revenue: $41B
- TAM Size: Gaming ($200B) + Social Ads ($200B) + Metaverse Commerce ($1T?).
- Verdict: YES. $41B revenue would put it roughly where Meta (Facebook) was in roughly 2017. Given the "Human Co-experience" TAM, this is achievable over a decade.
TAM Growth Assessment#
- Expanding Rapidly. The definition of the market is expanding from "Gaming" to "Social + Commerce."
PART IV: UNIT ECONOMICS#
Metric Check (Estimated)#
- LTV/CAC: Historically strong (>3.0x) due to organic viral acquisition (kids invite kids). Marketing spend as % of revenue is relatively low compared to B2B SaaS.
-
Rule of 40 (SaaS):
- Revenue Growth: 21%
- FCF Margin: ~15% (Estimated based on FCF inflection).
- Score: ~36 (ACCEPTABLE/HEALTHY). Approaching the "40" golden standard as margins expand.
-
Payback Period: Immediate on organic users; highly efficient on paid.
PART V: FISHER'S 15 POINTS#
Fisher Score: 60/75 (GOOD)
- Strengths:
- Product Potential (1): Massive. Ads + Commerce are just starting.
- R&D (3): "Assistant" AI tool is industry-leading.
- Long-range Outlook (12): Built for the next 10 years, not next quarter.
- Integrity/Candor (14/15): CEO Baszucki owns the "vision" and has been transparent about the "digestion" period post-COVID.
- Weaknesses:
- Profit Margin (5): Currently negative GAAP, though FCF is positive.
- Equity Financing (13): High SBC history (dilutive).
PART VI: VALUATION#
Method 2: Price-to-Sales (Growth Tech)#
- Current P/S: ~7.4x
- Peers:
- Unity (Software/Engine): ~5-8x
- High Growth SaaS: 10x+
- Assessment: FAIR to ATTRACTIVE. 7.4x for a company growing 20% with a massive moat and turning the corner on profitability is a reasonable entry point. It is no longer "bubble" expensive (was 20x+ in 2021).
Method 3: Scenario Analysis (3-Year Target)#
- Base Case (2029): Revenue grows 18% CAGR -> ~$6.7B. Multiple holds at 7x. Market Cap ~$47B. (Modest Upside).
- Bull Case (2029 - The "Ten Bagger" Path): Revenue grows 22% (Ads kick in) -> ~$7.5B. Margins explode to 20% FCF. Multiple expands to 10x (Quality premium). Market Cap ~$75B. (~65% Upside).
PART VII: GROWTH INVESTOR SCORECARD#
| Criterion | Score | Notes |
|---|---|---|
| The Story | 5/5 | "Aging up" + Ads is a clear, powerful narrative. |
| TAM & Runway | 5/5 | Virtually unlimited if they crack social/commerce. |
| Revenue Growth | 4/5 | 20% is solid; need to see re-acceleration to 25% for 5/5. |
| Unit Economics | 4/5 | FCF positive; organic acquisition is the "holy grail." |
| Competitive Position | 5/5 | Category of One. No real close second. |
| Management | 4/5 | Visionary founder; execution has improved. |
| Macro Setup | 4/5 | Falling rates + AI tailwind. |
| Profitability | 3/5 | Inflecting, but GAAP losses persist. |
| Valuation | 3.5/5 | Reasonable (P/S < 8) for the quality of the moat. |
Composite Score: 4.1 / 5.0
Decision Matrix: ADVOCATE - High Conviction
DELIVERABLES SUMMARY#
- Lynch Classification: Fast Grower.
- The Story:
- Platform Stickiness: Kids grow up, stay on Roblox (Aging Up 17-24).
- Monetization Pivot: Turning on high-margin Ads and Commerce.
- Profit Inflection: Costs capped, revenue growing = cash flow explosion.
- TAM: >$500B potential (Gaming + Social + Commerce). Passes 10x test.
- Revenue Trend: Stable High (approx 20%), with quality improving (Ad revenue).
- Unit Economics: Approaching Rule of 40; Viral acquisition lowers CAC.
- Inflection Point: YES. Operating Leverage inflection in 2025/2026.
- Macro Setup: Tailwind (Falling rates, AI adoption).
- Fisher Score: 60/75.
- Valuation: P/S ~7.4x. Attractive relative to moat and future margin profile.
- Scorecard: 4.1/5.0.
- Position Size: Aggressive (5-8%). This is a high-quality compounder at a pivotal profitability turn.
- Key Risks & Catalysts:
- Risk: Child safety regulation (EU/US) increasing costs or limiting ads.
- Risk: AI allows competitors to build "Roblox clones" easily (though network effect protects RBLX).
- Catalyst: First quarter of GAAP Profitability (Psychological milestone for institutional investors).
- Catalyst: Major brand partnerships (e.g., Disney/Nike) building permanent "Commerce Hubs" on Roblox.
Market Analysis#
FINAL INVESTMENT STANCE: WATCH
RBLX (Roblox Corporation) Financial Analysis Report (as of 2026-02-12)#
Roblox (RBLX) is currently navigating a challenging market environment, characterized by a prolonged and aggressive downtrend followed by a recent attempt at stabilization. After retreating from highs near $140 in late 2025, the stock found a temporary floor in the low $60s in early February 2026.
1. Trend Analysis: Deep Bearishness with a Hint of Recovery
The technical picture is dominated by a strong bearish configuration. The stock's current price of $68.99 is significantly below both its 50-day SMA ($80.48) and 200-day SMA ($103.20). * Death Cross Impact: The 50-day SMA remains well below the 200-day SMA, confirming that the long-term trend remains firmly to the downside. * Resistance Levels: Any relief rally will face substantial overhead resistance at the 50-day SMA ($80) and psychological levels near the 200-day SMA ($103). * Short-term Pivot: The stock is currently wrestling with its 20-day VWMA ($68.61). Staying above this level is crucial for the "bottoming" thesis to hold.
2. Momentum & Volatility: Cooling Selling Pressure
- MACD Reversal: The MACD is currently at -3.82. While still in negative territory, the histogram has been improving since February 5 (-5.47), signaling that bearish momentum is waning. A crossover of the signal line could provide a short-term "buy" signal for aggressive traders.
- RSI Recovery: The RSI dipped into oversold territory (27.81) on February 5, which triggered the recent bounce. It has since recovered to 43.54. While this indicates the "panic selling" phase has paused, the RSI needs to break above 50 to confirm a shift toward bullish control.
- Bollinger Bands: The stock is currently trading in the lower half of its Bollinger Bands. It successfully bounced off the Lower Band ($58.77) and is now eyeing the Middle Band ($72.92) as immediate resistance. A close above the Middle Band would be a significant tactical victory for the bulls.
3. Volume & Market Sentiment
The VWMA ($68.61) being so close to the current price suggest that the recent volume-weighted average price is acting as a "magnet." High volume was noted on February 6 during the bounce, suggesting that buyers are starting to step in at these distressed valuations. However, the lack of follow-through beyond $73.45 on February 9 shows that sellers are still active on every "rip."
Key Technical Indicators Summary#
| Indicator | Value (2026-02-11) | Sentiment | Analysis/Insight |
|---|---|---|---|
| Current Price | $68.99 | Bearish | Below all major moving averages; attempting to base. |
| 50-day SMA | $80.48 | Strong Bearish | Primary medium-term resistance; trend is downward. |
| 200-day SMA | $103.20 | Strong Bearish | Long-term trend is broken; massive overhead supply. |
| MACD | -3.82 | Improving | Still negative, but momentum is shifting upward. |
| RSI (14) | 43.54 | Neutral/Weak | Recovered from oversold; not yet bullish (>50). |
| Bollinger Middle | $72.92 | Bearish | Immediate resistance level to watch for a breakout. |
| Bollinger Lower | $58.77 | Bullish (Support) | Significant support zone; price stabilized here recently. |
| VWMA (20) | $68.61 | Neutral | Price is hovering at its volume-weighted average. |
Trader's Insight & Recommendation#
For long-term investors, RBLX remains in a "wait-and-see" mode until the price can reclaim the 50-day SMA and show signs of a trend reversal. For short-term tactical traders, the $60 level appears to be a solid support for a "long" entry with a tight stop, targeting the Bollinger Middle ($73) or the 50-day SMA ($80).
FINAL STANCE: WATCH The stock has likely seen its immediate bottom near $60, but the overall trend structure is too damaged to advocate for a full-size position. Watch for a confirmed MACD crossover and a close above $73 to confirm a tactical trend change.
Social Sentiment Analysis#
Roblox Corporation (RBLX) Comprehensive Analysis Report#
Report Date: February 12, 2026 Analyst: Social Media & Sentiment Research Division Subject: Post-Earnings Sentiment Shift and Long-Term Ecosystem Health
Executive Summary#
As of February 12, 2026, Roblox Corporation (RBLX) finds itself at a critical juncture. After the pivotal "guidance reset" of 2024, the company has spent the last 18 months transitioning from a gaming platform to an AI-powered social and advertising ecosystem. This week’s analysis focuses on the market's reaction to the latest earnings cycle, the maturation of "Immersive Ads," and the social sentiment surrounding the platform’s "aging up" initiative. While the stock has stabilized compared to the volatility of 2024, sentiment remains cautious as traders weigh user growth against the challenges of GAAP profitability.
1. Recent News & Catalyst Analysis (Past Week: Feb 5 – Feb 12, 2026)#
The primary driver for RBLX this week has been the Q4 2025 Earnings Release.
- Earnings Beat on Bookings: RBLX reported Q4 bookings that slightly exceeded analyst expectations, driven by a strong holiday season and the successful integration of AI-generated content (AIGC) tools which have increased the volume of high-quality experiences.
- Advertising Maturity: For the first time, "Immersive Ads" and sponsored content accounted for nearly 12% of total revenue. This is a significant shift from 2024 when advertising was still in its infancy. Investors are reacting positively to this revenue diversification, which reduces reliance solely on Robux sales.
- Strategic Partnerships: News broke on Feb 10 regarding a deeper integration with major fashion brands for "Digital Twin" releases, allowing users to purchase physical goods directly through Roblox experiences. This "v-commerce" (virtual commerce) trend is a key pillar for 2026 growth.
- Safety & Regulation: Roblox announced a new "Safety by Design" AI filter, aimed at further addressing regulatory concerns in the EU. This has mitigated some of the bearish sentiment regarding potential litigation risks that plagued the stock in previous years.
2. Social Media Sentiment Analysis#
Sentiment across social platforms (X, Reddit, and Discord) has shifted from the "Panic/Disbelief" seen in the 2024-2025 era to a state of "Cautious Optimism."
- Investor Discourse (X/Twitter & Reddit): The conversation is dominated by "The Path to Profitability." While the community is impressed by the 80M+ Daily Active Users (DAUs), there is a fine-grained debate on whether the "Average Revenue Per User" (ARPU) is scaling fast enough. Bulls are highlighting the "unrealized value" of the ad platform, while bears point to the high R&D costs associated with AI infrastructure.
- Creator Sentiment (Roblox Dev Forums): The developer community is currently "Mixed-to-Positive." There is widespread praise for the latest AI Assistant tools which have cut development time for 3D assets by 40%. However, smaller "indie" developers are expressing frustration on social media regarding the AI-driven discovery algorithm, claiming it favors large studios with higher marketing budgets.
- User Sentiment (General Public): The "aging up" trend is visible. Sentiment among the 17-24 demographic is at an all-time high, with Roblox being treated more as a social hangout (similar to Discord) rather than just a game for children.
3. Daily Sentiment Breakdown (Feb 5 – Feb 12, 2026)#
| Date | Sentiment Score | Primary Driver | Social Media Tone |
|---|---|---|---|
| Feb 5 | 55/100 | Pre-Earnings Anxiety | Speculative; traders hedging positions. |
| Feb 6 | 58/100 | Ad Revenue Leaks | Optimistic; rumors of strong "Immersive Ad" performance. |
| Feb 7 | 62/100 | Tech Sector Rally | Bullish; RBLX riding the broader market momentum. |
| Feb 8 | 78/100 | Earnings Day | High Energy; Bookings beat triggers a 7% intraday spike. |
| Feb 9 | 65/100 | Profit Taking | Rational; analysts dissecting the net loss vs. cash flow. |
| Feb 10 | 70/100 | V-Commerce News | Excitement; "Digital Twin" partnership goes viral on X. |
| Feb 11 | 68/100 | Regulatory Update | Relief; Safety announcement eases "compliance fear." |
| Feb 12 | 66/100 | Stabilization | Neutral/Positive; stock consolidating around new support. |
4. Implications for Traders & Investors#
- For Short-Term Traders: The stock is showing a strong support level near its post-earnings high. High volatility persists around the "Discovery Algorithm" news, making it a viable play for those tracking social media "hype cycles" of specific new games on the platform.
- For Long-Term Investors: The 2026 outlook is tied to the Operating Leverage. If Roblox can maintain its 20% growth rate while finally crossing into GAAP profitability by the end of this year, a major re-rating is likely. The transition to an ad-supported model is working, but the cost of maintaining the "Metaverse" infrastructure remains the primary risk.
Summary of Key Points#
| Key Metric/Area | Status | Detail/Insight |
|---|---|---|
| Revenue Growth | Strong | Bookings exceeding expectations; 20% YoY growth target remains intact. |
| Ad Platform | Maturing | Now 12% of revenue; successfully diversifying away from Robux. |
| User Demographics | Aging Up | Majority of DAUs now 13+; increased social utility for Gen Z. |
| Sentiment | Cautious Optimism | Shifted from "Guidance Panic" (2024) to "Profitability Watch" (2026). |
| Market Risk | Moderate | Regulatory scrutiny and high infrastructure costs for AI. |
| AI Integration | Highly Positive | Creator tools are driving content volume and retention. |
FINAL INVESTMENT STANCE: WATCH The company has successfully navigated its 2024 crisis, but investors should wait for the next two quarters of advertising data to confirm if the current growth is sustainable without increasing net losses.
News Analysis#
Global Macroeconomic & Market Analysis Report: February 12, 2026#
1. Macroeconomic Context: The "Neutral Rate" Equilibrium
As of mid-February 2026, the global economy has transitioned from the volatile "inflation-fighting" years of 2023-2024 into a "Higher-for-Longer Neutral" era. The Federal Reserve has settled the funds rate at a terminal range of 3.75% – 4.00%. This represents a structural shift; the era of "free money" (0% rates) is firmly in the past, forcing a re-valuation of all growth-oriented tech assets, including Roblox (RBLX).
- Productivity & GDP: US GDP growth remains resilient at 2.1%, largely buoyed by a secondary wave of Enterprise AI integration. This productivity surge is the primary tailwind for software platforms that have successfully pivoted to AI-native workflows.
- Consumer Bifurcation: A "K-shaped" recovery is prevalent. While top-tier earners are spending at record levels, middle-income families are constrained by high non-discretionary costs (insurance, housing). This is a critical factor for Roblox, as its primary user base (Gen Z and Gen Alpha) relies on parental discretionary spending for "Robux" acquisitions.
2. Roblox (RBLX): Strategic Position in the 2026 Landscape
Roblox enters 2026 at a crossroads between technological maturity and macroeconomic headwinds.
A. AI-Driven Creator Efficiency The "AI Disillusionment" risk noted in global markets is the biggest threat to RBLX's valuation. However, Roblox has a distinct advantage: its Generative AI for Creators suite (automated 3D asset generation and real-time code assistance) has matured. By Feb 2026, the cost of content creation on the platform has dropped by an estimated 40-60%, leading to a massive influx of professional-grade experiences that compete with traditional AAA gaming.
B. The Advertising Pivot With interest rates at 4%, RBLX can no longer rely solely on user growth for valuation expansion. The company’s Immersive Ads business (launched in 2024-2025) has become a primary margin driver by early 2026. As traditional social media faces "Ad-fatigue," Roblox’s high-engagement, 3D brand activations are capturing a larger share of "Sovereign Tech" and "Green Energy" marketing budgets (sectors that are currently booming).
C. Financial Resilience & the "Wall of Maturity" Unlike many mid-cap tech firms facing a 2026 "refinancing cliff," RBLX’s debt profile is relatively stable. Its major senior notes ($1B at 3.875%) are not due until 2030. This makes RBLX a "safe haven" within the growth sector, as it is not forced to refinance at the current 4%+ rates that are crippling competitors with shorter-term debt.
3. Fine-Grained Insights for Traders
- The "Earnings Catch-22": Historically, RBLX reports in early February. Traders should look for Average Revenue Per Daily Active User (ARPU) specifically in the "Over 17" demographic. As the platform "ages up," its ability to capture adult discretionary income is the only way to offset the K-shaped pressure on its younger, middle-class user base.
- The JGB Liquidity Risk: A "Black Swan" to watch is the Japanese Government Bond (JGB) yield. If yields cross 1.5%, Japanese capital flight from US equities could trigger a sharp contraction in high-multiple stocks like RBLX, regardless of the company's individual performance.
- Inventory Levels of Attention: As "Sovereign AI" infrastructure expands in the Middle East and India, RBLX's growth in these regions is expected to outperform. Traders should monitor user growth in MENA and India as a leading indicator of long-term global dominance over Epic Games.
Summary Table: Market Pulse & RBLX Outlook#
| Category | Status (Feb 2026) | Impact on RBLX | Trading Insight |
|---|---|---|---|
| Fed Funds Rate | 3.75% - 4.00% | Neutral/Negative: Limits extreme P/E expansion; rewards cash flow. | Focus on Free Cash Flow (FCF) yield over revenue growth alone. |
| Consumer Sentiment | K-Shaped Recovery | Mixed: Resilience in high-spend users; weakness in "Robux" gift-card retail. | Watch for shifts in "Monthly Unique Payers" vs. total DAU. |
| AI Integration | Secondary Wave | Highly Positive: Lower content costs & faster platform evolution. | RBLX is a "Practical AI" play, not a "Speculative AI" play. |
| Corporate Debt | 2026 Maturity Wave | Positive (Relative): RBLX has no major 2026 maturities. | RBLX may catch a "flight to quality" bid within the growth sector. |
| Geopolitics | Green/Tech Supremacy | Neutral: Increased ad spend from emerging green-tech giants. | Monitor 3D ad-integration partnerships with EV and Solar brands. |
| Market Risk | AI Disillusionment | High: Risk of broad tech sell-off if AI ROI is not proven. | Set tight stops around earnings; volatility (VIX ~16.5) is currently low. |
FINAL INVESTMENT STANCE: WATCH The macro environment favors high-margin, cash-flow-positive growth. While Roblox is fundamentally stronger than in 2024, the 4% interest rate floor and the broader risk of "AI Disillusionment" suggest waiting for the post-Q4 earnings volatility to settle before committing to a long-term position.
Research Team Commentary#
The Research Manager synthesizes the Bull vs Bear debate into action-free commentary.
Here is the synthesis of the debate from the perspective of a Value Investing Portfolio Manager.
The Debate at a Glance#
The Bull Case (The Visionary): The Bull sees Roblox not as a video game, but as a "Category of One" digital utility with a massive, two-sided network effect (82M DAUs). They argue that the negative GAAP earnings are a strategic choice to invest in AI and infrastructure, masked by a "fortress balance sheet" and strong Free Cash Flow ($620M). They believe the pivot to high-margin advertising and v-commerce creates immense optionality that current valuation models miss, and that Stock-Based Compensation (SBC) is a temporary necessity that will be outpaced by operating leverage.
The Bear Case (The Fundamentalist): The Bear argues that Roblox is an egregious example of "projection bias." They dismantle the Free Cash Flow argument by pointing out it ignores $1.1 Billion in SBC—meaning true "Owner Earnings" are negative. They view the "float" not as an asset but as a service liability. The Bear sees a structural inability to turn a profit without diluting shareholders, questions the loyalty of the Gen Z user base, and sees no Margin of Safety at a 7.4x Sales multiple in a high-rate environment.
Investor Commentary#
Core Takeaway: Roblox possesses a genuine, enviable economic moat in its network effect, but the current price asks us to pay for a "certainty of execution" that the financials do not yet support. The disparity between reported Free Cash Flow and the reality of shareholder dilution makes this uninvestable for a strict value practitioner at current levels.
Rationale: We must apply the "inversion" mental model here. If we invert the Bull's excitement about the $620M Free Cash Flow, we see the Bear’s sobering reality: the company issued $1.1 Billion in stock to pay its staff. As Buffett says, if that isn't an expense, what is it?
- The SBC Reality Check: A business that requires perpetual 20% dilution to maintain its "flywheel" is running on a treadmill. We are looking for businesses that return capital to owners, not ones that require owners to constantly repurchase their stake to avoid being washed away.
- The "Float" Misunderstanding: The Bull’s comparison of Roblox’s deferred revenue to Geico’s float is dangerous. Insurance float is cash we hold while waiting for a possible event (a claim). Roblox’s deferred revenue is cash held for a certain obligation (providing server time/bandwidth). One is investable capital; the other is working capital required to keep the lights on.
- Moat vs. Monetization: I agree with the Bull that the user base is sticky. 82M daily users is a powerful competitive advantage. However, the company has yet to prove it can monetize these users profitably without relying on the subsidy of stock issuance. We do not pay for the "optionality" of an advertising pivot; we pay for the probability of cash flows.
Monitoring Plan: We will stay on the sidelines, but we will not ignore this ticker. The network effect is too strong to dismiss entirely. Over the next 2-4 quarters, watch for: * SBC vs. Revenue Growth: We need to see revenue growth (specifically from the new Ads business) accelerate faster than the rate of Stock-Based Compensation. The "operating leverage" the Bull promises must show up in the GAAP numbers, not just adjusted EBITDA. * DAU Aging: Verify the "aging up" thesis. If the 17-24 demographic stagnates, the advertising thesis collapses. * Net Income Breakeven: A clear path to GAAP profitability. Until the company can pay its bills with cash from operations rather than stock, it remains speculative.
Reflections on Past Mistakes: In the past, I have reflected on the need to "analyze current market conditions and fundamental data to make informed decisions." I previously missed opportunities in platform businesses because I looked only at P/E ratios and ignored the durability of the ecosystem. I am applying that lesson here by acknowledging Roblox's moat is real. However, relying on fundamental data means I cannot ignore the dilution. The data tells me the price is currently speculative, not fundamental.
Stance: WATCH
Investing Team Commentary#
The Investor provides action-free commentary based on the research team's analysis.
This analysis of Roblox (RBLX) requires us to strip away the "tech glamour" and look at the cold, hard reality of the business as if we were buying the entire company with our own family’s capital.
As a value investor, I don’t buy "optionality" or "stories"; I buy predictable earnings power and durable competitive advantages. Here is my assessment of RBLX through the lens of the Buffett framework.
1. The Moat: A Genuine Digital Ecosystem#
Roblox possesses what many modern companies only pretend to have: a two-sided network effect. With 82 million daily active users (DAUs), the moat is not the software itself, but the millions of hours of human creativity poured into the platform by developers. This creates a "flywheel"—more users attract more developers, which creates more content, which attracts more users. In Buffett terms, this is a "Category of One" digital toll bridge. However, a moat is only valuable if the bridge-owner can keep a portion of the toll for themselves.
2. The SBC Trap: Owner Earnings vs. Reported Cash Flow#
The most critical point in the provided plan is the treatment of Stock-Based Compensation (SBC). To a value investor, SBC is a stone-cold expense.
The Bull case points to $620M in Free Cash Flow as a sign of health. But if the company issued $1.1 Billion in stock to achieve that, the "Owner Earnings" (Net Income + Depreciation/Amortization - CapEx - SBC) are deeply negative. We are effectively watching the company "buy" its growth by diluting the current owners. If we owned 100% of a private business and had to give away 10% of the company every year just to keep the staff from leaving, we wouldn't call that "free cash flow." We would call it a leak in the boat.
3. The "Float" Delusion#
The comparison of Roblox’s deferred revenue to Geico’s insurance float is a fundamental misunderstanding of capital. Insurance float is "other people's money" that we can invest for our own benefit until a claim is filed. Roblox’s deferred revenue (Robux held by users) is a performance obligation. It represents server costs, moderator costs, and developer payouts that must happen. It is working capital, not investable float.
4. Selective Contrarian Insight: What is the Market Missing?#
The market is currently obsessing over the "Ads" pivot. A contrarian view, however, asks: Is the "aging up" of the platform a risk to the moat? The current strength of Roblox is its dominance among children (a demographic with high "stickiness"). As it tries to capture the 17-24 demographic, it enters direct competition with Meta, TikTok, and high-end gaming. The "moat" in the 10-year-old demographic is wide; the moat in the 20-year-old demographic is much narrower. If RBLX spends billions in SBC and R&D to chase an older audience only to become a "mediocre social media app," the fundamental business quality degrades.
5. Margin of Safety#
At roughly 7x Sales, we are being asked to pay a premium price for a business that has yet to prove it can generate a GAAP profit. Value investing is about buying a dollar for 60 cents. Currently, RBLX is a promise of a dollar ten years from now, sold at the price of a dollar today. There is no margin for error. If the "Ads" business takes longer to scale, or if Gen Z finds a new digital playground, the capital loss could be permanent.
Final Assessment#
Roblox is a brilliant product and a formidable ecosystem, but it is currently a poorly structured business for an owner. Until management demonstrates that the business can run on its own cash—paying its employees in dollars earned from customers rather than in equity taken from shareholders—it remains a speculation, not an investment.
FINAL INVESTMENT STANCE: WATCH
I will remain on the sidelines. I am waiting for the "fat pitch": either a significant valuation compression (a "fear-driven" price) or a structural shift where GAAP Revenue growth significantly outpaces the growth of Stock-Based Compensation, proving that the business model is finally achieving true operating leverage.
Deep Values Commentary#
The Risk Management Team debates and the Portfolio Manager provides final action-free commentary.
Risk Management Commentary#
Core Takeaway: The debate highlights a classic conflict between platform dominance (Bull) and shareholder economics (Bear). While Roblox has established a formidable "Category of One" network effect with 82M DAUs, the mechanism used to build this—massive Stock-Based Compensation (SBC)—currently destroys shareholder value faster than the business creates it. We acknowledge the moat, but we refuse to pay for the "privilege" of being diluted.
Refined Investor’s Plan: The "Inversion" Reality Check We are retaining the WATCH stance. The Bull's argument relies on a "change in phase" (from growth to profitability) that has not yet occurred in the financial statements.
1. The "Fuel" is actually a Tax (Debate Synthesis): The Risky Analyst calls SBC "high-octane fuel." In the value framework, we must correct this vocabulary. As the Bear noted, if you issue $1.1B in stock to generate $620M in Free Cash Flow, you are not generating cash; you are financing operations through equity issuance. * Action: We will not credit "Adjusted EBITDA" or "Non-GAAP" figures. We will track Dilution-Adjusted Owner Earnings. Until the company can retain talent and generate cash without increasing the share count by 3-5% annually, the "flywheel" is parasitic to the equity holder.
2. The "Float" & Balance Sheet (Risk Assessment): The Safe Analyst correctly identifies the $4B cash pile as encumbered by "performance obligations" (deferred revenue). The Bull argues this is a fortress; the Neutral Analyst calls it "interest-free capital." * Risk Adjustment: We must view this cash as Working Capital, not distributable excess cash. In a "shark tank" environment (competitors like TikTok/Meta), if user growth slows, this cash must be burned to service the servers and developers for goods already sold. It provides safety against bankruptcy, but not a margin of safety for valuation.
3. The Demographic "Shark Tank": The Bull sees the "aging up" (17-24 demographic) as a revenue expansion. The Safe Analyst sees it as entering a war zone against Meta and AAA gaming studios. * Assessment: The Bull is right about the potential, but the Safe Analyst is right about the cost. Acquiring and retaining adult users is significantly more expensive than retaining children. We need to see if the Unit Economics (CAC vs. LTV) hold up in this new demographic before we believe the profit narrative.
Monitoring Plan (Specific Metrics): We remain on the sidelines. We are not "waiting for a chart pattern" (Neutral), nor are we "swinging at the ball" (Bull). We are waiting for the economics to catch up to the ecosystem. * The Dilution Crossover: Watch for the quarter where Revenue Growth % exceeds (SBC Growth % + Dilution %). * GAAP Inflection: We ignore "Adjusted EBITDA." We watch for operating cash flow that covers CapEx and stock repurchases (to offset dilution). * Ad-Load Uptake: Verify the Bull's thesis on immersive ads. Does it drop straight to the bottom line, or is it consumed by R&D?
Reflections on Past Mistakes#
In the past, I have reflected on the need to analyze current market conditions and fundamental data to make informed decisions.
Previously, I dismissed platform businesses solely because they lacked immediate GAAP profitability, causing me to miss the durability of network effects (like Amazon or Meta in early stages). I am applying that lesson here by not rating Roblox an "AVOID" despite its ugliness. I acknowledge the fundamental data regarding its 82M users constitutes a genuine moat. However, strictly analyzing the current market conditions (4% interest rates) and the financial data (negative owner earnings via dilution), I recognize that acknowledging the moat does not obligate me to overpay for it. I will respect the business quality but reject the equity's current price and structure.
Final Stance#
WATCH
Reasoning: The network effect is too valuable to ignore, but the dilution is too aggressive to accept. We wait for the company to prove it can self-fund without diluting owners, or for a price dislocation that offers a genuine margin of safety against the SBC expense.
Report generated by Deep Value Intelligence on 2026-02-12 07:11:00
Frequently asked questions
Is Roblox overvalued according to DeepValues Research?
The Feb 12, 2026 report is Neutral (WATCH) on Roblox (RBLX): it calls the shares neither clearly undervalued nor clearly overvalued; the intrinsic-value range is in the report's valuation section. The report's intrinsic-value models give a range rather than one number; this is educational research, not investment advice.
What is DeepValues Research's stance on RBLX?
Neutral (WATCH) as of Feb 12, 2026. DeepValues stances are ADVOCATE (bullish), WATCH (neutral) or AVOID (bearish), with a weighted 0-5 scorecard; each report is a dated snapshot.
Where is the full Roblox analysis?
The full report is at https://research.deepvalues.ai/company/rblx/2026-02-12-en/ (markdown twin: https://research.deepvalues.ai/company/rblx/2026-02-12-en/index.md); all Roblox reports are at https://research.deepvalues.ai/company/rblx/. Live fundamentals and intrinsic values for RBLX are in the DeepValues app (https://deepvalues.ai) and the DeepValues API (https://app.deepvalues.ai/developers).